ATTENTION: For Those who are serious about Getting Pre-Qualified FAST!
Bill Rapp, Mortgage Originator: NMLS 228246
"Brokers Are Better.
Better Pricing, Better Service!"
Subscribe To My List Below To Get Your Mortgage Quote Now!
Simply enter your name and email below:
WITH PROVEN STRATEGIES & PROVEN RESULTS
HERE'S WHAT MY CLIENTS SAY:
What People Are Saying:
Excellent Service
Bill is an exceptional loan officer. He helped us to purchase our home with very personal and professional service. He helped us navigate the whole process from start to closing without any problems. We didn't think we're qualified to purchase a house, but Bill went above and beyond to find a way to help us achieve our goal. He always responded very quickly with our requests, he would come back with different options with comparison chart to clearly indicate how much we need for down payment, monthly payments, interest rates, closing costs etc.
We would highly recommend Bill to anyone in need of lending services. In fact, we have already recommended Bill to one of our friends on purchasing a house.
--- David Chan - Houston, TX
Bank Statement Lending!
William Rapp of Network Funding, L. P. was very professional and I felt comfortable in dealing with him. I will definitely recommend him to family and friends.
--- Ian F - Missouri City, TX
Professionalism - Expert In Home Style Loan
Bill is an expert in the topic, his explanations and online material make a difference and he is always there from the beginning to the end. He is committed to make thing happen.
--- Felipe Caldern & Carolina Angel Gutierrez
Great Service!
Bill Rapp's handling of our loan (even though out of state) was unparalleled to any service I have been through prior, including 3 different real estate transactions and multiple refinances. Extremely quick close, with great options and flexibility for my families needs. All around A+
--- Chris & Beth Sheehan - San Jose, CA
Knowledgeable and Responsive!
Bill was a pleasure to work with and he made the loan process fairly easy. He answered all questions I had very quickly and was straight forward in doing it. I would recommend Bill to others.
--- Wes Brady - Richmond, TX
Very professional and always returned our calls!
Bill takes a lot of pride in his job and is very dependable. They were very patient and understanding. He went out of his way and explained all my questions and concerns. They were very professional and returned my phone calls and emails. He did a great job and I fully recommend him.
--- Therese, Malcom & Shirley Teixeira - Katy, TX
Great Job!
Bill helped us out from beginning to end of loan process. The loan closed in a timely manner as Bill worked hard with bank to get our to the final steps.
--- Kamal & Theresa Wilson - Hartford, CT
Avid Problem-Solver and Absolute Pleasure to Work With!
Bill Rapp worked very hard to ensure that we closed our loan and were able to move into our new home. He always had alternatives to any problems we encountered while closing. He worked with us from the beginning identifying solutions to any problems that we were having. He was an absolute pleasure to work with!
--- Nikita Rayani & Sanit Tejani - Houston, TX
Awesome to work with!
Being a first-time buyer I came in with lots of questions and concerns. Bill was always available for any questions I had and answered everything to my satisfaction. Bill made the loan process so painless that I could still concentrate on other things. We ended up closing early which made things even better. If you are in need of a lender and want someone who is very approachable and stays on top of your loan then Bill is your guy.
--- Cesar Raya - Richmond, TX
Loan Declined by my bank, and he saved the day!
Bill, did an amazing job helping me close on my house. He took the reigns and reassured me the best route to take to help close. He was accountable, thorough and trustworthy. I will continue to work with Network Funding, L.P. when it comes to home buying in the future because of the quality of service Bill gave.
--- Jacob Smith - Boerne, TX
Bill Rapp Will Definitely Make It Happen!
Bill is the most kind, patient and helpful person I have ever known. He answers his phone calls and emails promptly. You can ask him a million questions, and he will answer each and every one of them. Before I started working with Bill, I had been turned down for a home loan, because of some past credit issues I had, plus I was a single mother. However, once I started working with Bill, he was able to quickly get me a home loan, with a good interest rate. I would recommend that you call him, as he will help you.
--- Corinne Wilson - Roselle, NJ
Knowledgeable, Honest, Trustworthy, and Reliable!
"I will definitely keep you in mind. If anyone I know needs financing, I will send them your way!"
--- Jon & Andrea Saleem, CRPC Financial Advisor - Houston, TX
Best Dam Mortgage Guy a man could know!
"Hands down the best loan experience to date!"
--- Gabe & Chelsea Jackson - Pearland, TX
Phenomenal, Hard Working and Never Quits!
Had a stupid foreclosure that could have been avoided if ex’s attny would have sent my buy out offer. So Bill was able to push this through with a 4 year foreclosure. He worked his butt off, was very diligent with his communication; and was very professional talking to me even when I was screaming and/or crying at him. Highly recommend this lender. He really go to the ends of the earth to help you!
--- Liz Keeter - Harlingen, TX
Exceptional customer service!
Bill is the most kind, patient and helpful person I have ever known. He answers his phone calls and emails promptly. You can ask him a million questions, and he will answer each and every one of them. Before I started working with Bill, I had been turned down for a home loan, because of some past credit issues I had, plus I was a single mother. However, once I started working with Bill, he was able to quickly get me a home loan, with a good interest rate. I would recommend that you call him, as he will help you.
--- Isha Lopez & Mauricio Garcia - Houston, TX
Service with a capitol S
Bill went above and beyond at every turn. He worked late on Saturday, he worked late all the time. We wanted to close ASAP and he really helped make it happen for us.
--- Jeff & Wendy Heger - Houston, TX
Best Buying Experience!
I would would highly recommend going with Network Funding LP. As a first time home buyer I didn't know what to expect. Bill Rapp was very helpful in answering all my questions and guided me through all ghe steps. I couldn't have asked for a better buying experience!
--- Tabitha Turner - Humble, TX
Would recommend him and use him again!
Very involved and professional . Kept me informed and up to date on everything that was going on Went with me closing and was very helpful and knowledgeable.
--- Kathy Ward - Houston, TX
Great experience!
Well I meet bill back in December 2016 he got recommended by my real estate agent we had a house in sight and started the process to get approved but we fail due to my work history and credit bill told me not to give up and put me in contact with a credit repair company they help me bring my score up and bill walk me thru the process of getting a new line so this time around we got approved before looking for our house after we found it we still had a couple of hick up but with bills help on Sunday 6-18-17 to be exact Father's Day bill called me to give me the great news that we had got approved and the closing date was as scheduled bill was more than just a lender to my family he became a friend and I'm alway going to have him in mind for any other financial situation.
--- Alejandres Felimon - Richmond, TX
I really liked his attitude!
I wouldn't usually say this but the way he had handled my mortgage was really pleasant. I personally enjoyed the time spent with him while we discussed feasible rates. He's a great man with a great personality and he offered really low interests as well. Definitely recommend him to others.
--- Tom Troiano - Atlantic City, NJ
He's nothing short of a miracle!
I'm a self-employed businessman and had him figure out the mortgage of the house after 30% down payment. The interest rates I received were incredibly low given what I had thought of earlier. One other important thing to note was that I hadn't really taken any loans earlier, so I had no credit history. He helped me out with all that as well so I can't really call him anything else but a miracle.
--- Fran Suarez - Cleveland, OH
He's really helpful!
I made a bid to him and the very same day he gave me an offer which I couldn't resist. It was too intimidating with those incredibly low interest rates and all, thoroughly recommend him.
--- Kenny Mickle - Houston, TX
Expeditious!
Bill was very expeditious and made it real easy going through the loan process. I felt he was on top of things.
I deal with investment properties and will more than likely call on him again.
--- Wayne King - Pensacola, FL
Bill was great!
Bill made us feel like a friend all the way thru the process. He was patient and explained everything he needed clearly. He was available ANYTIME we had questions or needed more information. Hopefully we won’t go thru this process again anytime soon, but if we do - we’d choose Bill! =)
--- Barbra & Nick Grimmer - Austin, TX
Great broker!
Bill was a great broker to work with. As first time home buyers we had many questions about the process, Bill took the time to help us even calling us back on weekends with answers. I would not hesitate to recommend him to anyone looking for a broker to work with.
--- Murray & Lisa Turner - Pensacola, FL
Outstanding service!
I couldn't have been more pleased with Bill's level of service. He made what is typically a lengthy, arduous process far quicker and easier at every turn. I'm extremely comfortable recommending Bill to friends and family, and will definitely utilize his services again!
--- Jim Lipari - Austin, TX
Step-by-Step Guide to the VA Loan Process
6 Easy Steps to a VA Loan
For many borrowers, applying for any kind of mortgage may seem daunting.
But, when broken down, this rundown of 6 steps to getting a VA loan is easy to understand.
1. Select a VA-approved Lender
On the surface, it might appear that any lender will do. However, if you dig a little deeper, you may discover that not all lenders are the same. First, only lenders approved by the U.S. Department of Veterans Affairs can originate VA mortgages. Secondly, some lenders focus primarily on conventional loans, while others concentrate almost exclusively on the VA loan program for military clients. Using a VA specialty lender with extensive knowledge about the VA loan process vs. a lender who only funds a few VA mortgages a year may translate into an easier and quicker loan process. To connect with a VA specialty lender, please click here.
2. Obtain a Certificate of Eligibility (COE)
An experienced lender can help you obtain what’s called a Certificate of Eligibility (COE). The COE will prove that you meet initial eligibility standards for VA loan benefits. It will also let the lender know how much entitlement you can receive, which is the amount the Department of Veterans Affairs will guarantee on your VA loan. To get your COE, you’ll need to give your lender a bit of information about your military service. Usually, a COE can be acquired online instantly through a lender’s portal or through the eBenefits portal on the va.gov website. Those servicemembers or surviving spouses whose COEs cannot be obtained online will have to get theirs by mail. A VA lender or the VA can help direct you to the right resource for your specific situation.
3. Pre-Qualify for Your Loan Amount
Pre-qualifying is important, but not required. By choosing to complete this step you can save some time and potential surprises later in the process. To pre-qualify for your loan amount, you’ll have a candid conversation with your VA loan professional about your income, credit history, employment, marital status and other factors. Giving your lender complete details during the pre-qualifying step can help prevent surprises later during underwriting. The pre-qualifying step can also reveal areas that need improvement before you can be approved, such as credit or debt-to-income ratio. While a prequalification letter gives you a ballpark price range for house hunting, it does not guarantee that you will be approved for a loan, and your lender will later have to verify the information you provide. To get a loan requires later final approval by underwriting once all documents have been received and reviewed (see Step 5).
4. Go House Hunting & Find Home
The fourth step is usually one borrowers enjoy because they get to look at homes they might consider buying. Working with a real estate professional who specializes in the VA process can help you get the most out of your benefits. This is true because the VA allows certain fees and costs to be paid by the seller (if both you and the seller agree), and a knowledgeable agent will know this and help you negotiate seller-paid fees. Once you’ve got a signed purchase agreement, you can move forward in the VA loan process.
5. Lender Processes Application
& Orders VA Appraisal
A signed purchase contract is the document you’ll need to finish your initial application. Once your lender has the contract, they will order the VA appraisal. Here again, not just any appraiser will do. Only a professional who is certified to perform appraisals to VA standards can evaluate the home being considered for VA financing. The VA appraiser will make sure the price you’ve agreed to pay for the home corresponds with the current value. Another very important part of the VA appraisal is to inspect the home to make sure it meets the VA minimum property requirements (VA MPRs). However, the VA appraisal does not take the place of a home inspection, which focuses on code violations, defects and the condition of the property. While many borrowers have heard horror stories about the length of the VA appraisal process, the Department of Veterans Affairs gives the appraisers 10 days from order to completion barring extenuating circumstances. While you’re waiting for appraisal documents, you’ll be busy submitting documents of your own to your VA-approved lender to show you have the ability to qualify for the loan. If the home passes appraisal for value and VA minimum property requirements, and it’s verified by the lender that you qualify for your loan, the underwriter will give his or her stamp of approval.
6. Close on Your Loan and Move In
After being approved by the underwriter, all that is left to do is close and move in. During closing, the property legally transfers from the former owner to you. Closing is a step that requires you to sign documents that confirm you understand and agree to the terms of the loan. You will need to provide proof of homeowners insurance and, if required, pay closing costs. Once you’ve signed all your closing documents, you’ll get the keys to your new home.
While these steps may not happen in the order above or be a required part (such as prequalification)*, they represent the typical process for the applicant in obtaining a VA purchase loan. Your lender may need to take other steps. For more information about VA loans, contact an experienced VA-approved lender.
My best advice to you is to call Bill Rapp, the Mortgage Viking, today to discuss your options 281-222-0433.
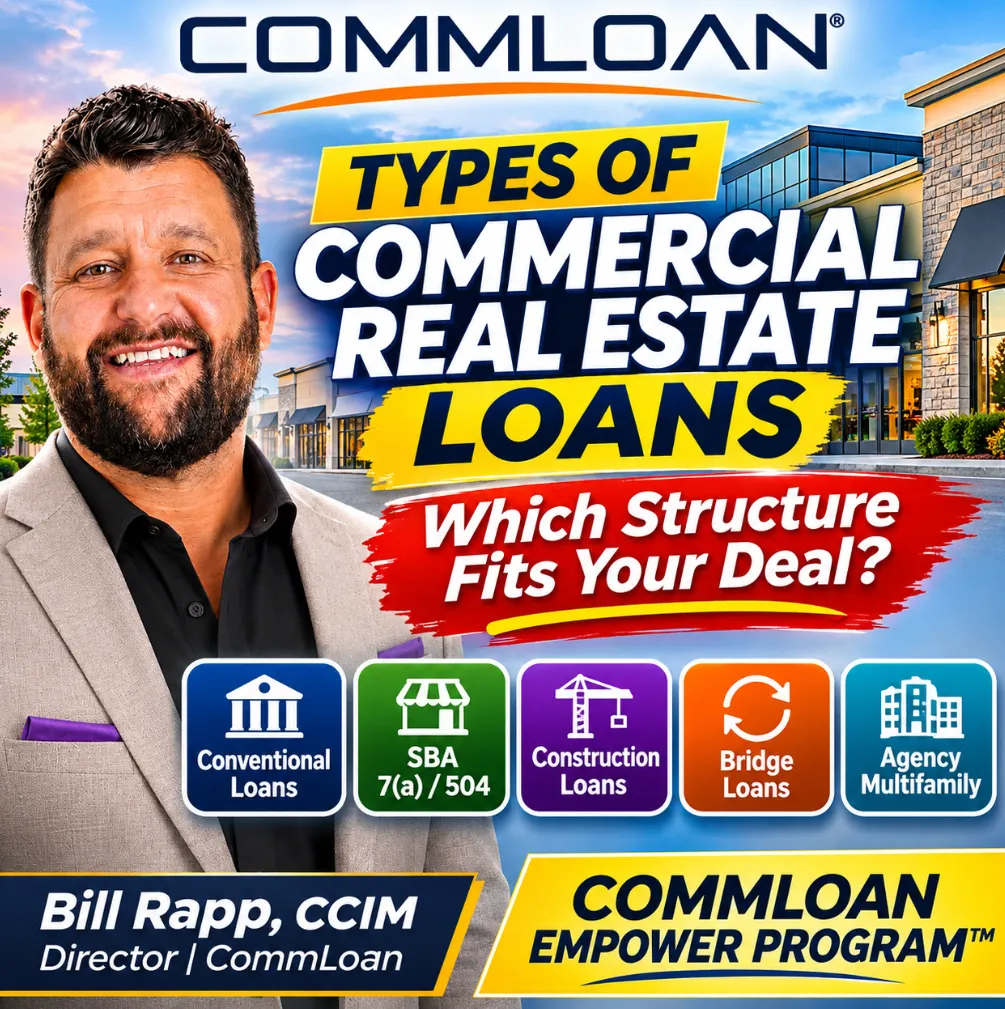
🏢 Types of Commercial Real Estate Loans: Which Is Best? 💰
🏢 Types of Commercial Real Estate Loans: Which Is Best? 💰
💵 Commercial Real Estate Loan Types Explained 🏦
________________________________________________________________________________
🏢 Types of Commercial Real Estate Loans: Which Structure Fits Your Deal?
Choosing the right commercial real estate loan can be just as important as choosing the right property.
A commercial loan that works perfectly for a stabilized apartment complex may be completely wrong for a vacant retail center, an owner-occupied medical building, or a ground-up industrial development.
Yet many borrowers begin their financing search with one question:
“What's the interest rate?”
That's an important question, but it's rarely the best place to start.
The more valuable question is: Which commercial real estate loan structure best supports my property, cash flow, investment strategy, and exit plan?
Understanding the different types of commercial real estate loans can help investors and business owners avoid unnecessary financing costs, maturity risks, restrictive loan terms, and missed opportunities.
In this guide, we'll examine the most common commercial financing options, explain how lenders evaluate transactions, and help you identify the structure that may fit your next deal.
What Are the Main Types of Commercial Real Estate Loans?
Commercial real estate financing is not a one-size-fits-all product. Lenders offer different programs depending on the property type, occupancy, borrower qualifications, and intended use of the funds.
Here are eight common financing categories.
1. Conventional Commercial Real Estate Loans
Conventional bank and credit union loans are commonly used to purchase or refinance stabilized commercial properties. They may offer competitive pricing and flexible relationship-based underwriting, but can require strong financials, guarantees, and periodic refinancing.
Best for: Established businesses and investors with stable cash flow.
2. SBA 7(a) and SBA 504 Loans
SBA financing supports eligible owner-occupied business real estate. SBA 7(a) can combine property acquisition with eligible business needs, while SBA 504 is commonly used for major fixed assets such as buildings and equipment.
Best for: Eligible small businesses purchasing or expanding their facilities.
Bel Red Apartments - Dimensional Building Consultants - Bellevue, WA
3. Agency Multifamily Loans
Fannie Mae and Freddie Mac multifamily programs finance eligible income-producing apartment properties, generally with five or more units. Depending on the program, they may offer long amortization, fixed rates, and nonrecourse structures with customary carveouts.
Best for: Qualifying stabilized multifamily investments.
Retail Site Selection in 2026: Why Rapid Disqualification Is Your Greatest Competitive Advantage
4. Commercial Bridge Loans
Bridge financing provides temporary capital for properties undergoing acquisition, renovation, lease-up, or repositioning. These loans often carry higher costs and shorter maturities than permanent financing.
Best for: Transitional properties with a credible stabilization or sale strategy.
What Makes Steel Warehouse Construction Superior to Wood and Concrete - showhoobuilding.com
5. Commercial Construction Loans
Construction financing funds eligible development costs through a draw process tied to project progress. Lenders evaluate the budget, sponsor experience, contractor, contingency, schedule, and takeout financing.
Best for: Ground-up development and major construction projects.
340 S Stiles St, Linden, NJ 07036 - Industrial for Lease | LoopNet
6. CMBS Loans
Commercial mortgage-backed securities loans are typically used for qualifying income-producing properties and are structured for securitization. They can offer attractive terms but often have strict servicing, defeasance, or prepayment provisions.
Best for: Qualifying stabilized investment properties where long-term financing terms align with the hold strategy.
Investor Friendly Real Estate Agent | How Top Agents Attract Investors — Take Action Realty Group
7. DSCR-Based Commercial Loans
These programs emphasize a property's ability to generate sufficient net operating income to service its debt. They may be offered by banks, debt funds, or other commercial lenders.
Best for: Income-producing investment properties with supportable debt service coverage.
How to Obtain an Encumbrance Certificate in Bengaluru? | Brigade Group
8. Private Money and Hard Money Loans
Private lenders may provide asset-based financing for transactions that cannot meet conventional underwriting or timing requirements. These loans typically have higher costs and require a clear repayment strategy.
Best for: Time-sensitive, unconventional, or short-term investment opportunities.
Commercial Loan Comparison: Which Structure Fits?
Loan type | Typical transaction | Primary consideration |
Conventional bank | Stabilized commercial asset | Borrower strength and cash flow |
SBA 7(a) | Owner-occupied business property | SBA eligibility and business repayment |
SBA 504 | Eligible fixed-asset acquisition | Occupancy and project eligibility |
Agency multifamily | Stabilized apartments | NOI, occupancy and agency criteria |
Bridge | Value-add or transitional | Exit and refinance risk |
Construction | Development project | Completion and takeout risk |
CMBS | Stabilized investment asset | Servicing and prepayment restrictions |
DSCR-based | Income-producing property | Debt coverage and leverage |
Private money | Nontraditional or urgent deal | Cost, collateral and exit |
These are general categories, not guaranteed loan programs or terms. Several categories overlap: a conventional, agency, or CMBS loan can also be underwritten using DSCR.
How Do Commercial Real Estate Lenders Evaluate a Deal?
Before selecting a commercial loan structure, borrowers should understand the underwriting metrics that influence financing.
Loan-to-Value Ratio (LTV)
LTV measures the loan amount relative to the property's appraised value.
For example, a $3 million loan against a $4 million property represents 75% LTV.
\[ \text{LTV}=\frac{\text{Loan Amount}}{\text{Property Value}}\times100 \]
Higher leverage may reduce the borrower's initial equity requirement, but can increase lender risk and limit available programs.
Debt Service Coverage Ratio (DSCR)
DSCR measures the property's ability to cover annual debt service.
\[ \text{DSCR}=\frac{\text{Net Operating Income}}{\text{Annual Debt Service}} \]
A property generating $300,000 in annual NOI with $240,000 in annual debt payments has a DSCR of 1.25x.
That means the property generates $1.25 in NOI for every $1.00 of scheduled debt service.
Many conventional commercial programs target coverage around 1.20x–1.30x, although requirements vary significantly by asset class, lender, amortization, and transaction risk.
Debt Yield
Debt yield measures annual NOI as a percentage of the loan principal.
\[ \text{Debt Yield}=\frac{\text{NOI}}{\text{Loan Amount}}\times100 \]
For a $3 million loan supported by $300,000 in NOI, debt yield equals 10%.
Unlike DSCR, debt yield does not directly depend on interest rate or amortization assumptions.
Borrower Liquidity and Experience
Lenders also evaluate cash reserves, net worth, credit history, management experience, existing debt, and the borrower's ability to manage unexpected expenses.
A strong property does not automatically qualify for every loan program.
Fixed-Rate vs. Floating-Rate Commercial Loans
Commercial borrowers should consider how interest rate structure affects both near-term cash flow and long-term risk.
Fixed-rate loans provide more predictable payments during the fixed-rate period. They may be attractive for long-term investment holds, although some products impose substantial prepayment penalties.
Floating-rate loans adjust according to a benchmark such as SOFR plus a contractual spread. They may provide flexibility but expose the borrower to rising debt service unless an effective hedge or rate cap is in place.
The best choice depends on the expected hold period, refinancing strategy, rate risk tolerance, and overall loan terms.
Balloon Payments: A Critical Commercial Financing Risk
Many commercial mortgages have a shorter contractual term than their amortization period.
For example, a loan may have a five-year term with payments calculated using a 25-year amortization schedule.
At the end of year five, the remaining principal becomes due.
This is called a balloon payment.
If interest rates rise, property values decline, or NOI deteriorates, refinancing may become difficult.
Borrowers should understand their loan maturity and evaluate the potential refinance balance before closing.
Real-World Example: Financing a $4 Million Commercial Property
Consider two investors evaluating commercial properties at the same purchase price.
ILLUSTRATIVE FINANCING COMPARISON
Property A
Stabilized Retail Center
$4.0M
Purchase price
Potential structure
Conventional Bank
75% LTV · $3.0M loan
$1.0M equity before costs
Property B
Vacant Retail Center
$4.0M
Purchase price
Potential structure
Bridge Financing
65% LTV · $2.6M loan
$1.4M equity before costs
Hypothetical terms for educational comparison only; actual proceeds may be constrained by DSCR, debt yield, costs, and lender underwriting.
Property A generates consistent income from established tenants. Its stable cash flow may support a conventional commercial mortgage.
Property B has substantial vacancy and requires renovations before reaching stabilized occupancy. A conventional lender may not finance the transaction at the desired leverage.
A bridge lender may be willing to consider the property based on its current condition, business plan, sponsor strength, and projected stabilized value.
However, Property B's investor must account for renovation costs, leasing commissions, carrying expenses, interest reserves, and the ability to refinance after stabilization.
The key takeaway is that identical purchase prices do not mean identical financing strategies.
Five Questions to Ask Before Choosing a Commercial Loan
1.Is the property stabilized or transitional? Stable NOI supports different financing options than a vacant or underperforming asset.
2.Will the property be owner-occupied or investment-owned? This distinction is especially important for SBA eligibility.
3.How long do I plan to own the property? Loan maturity, prepayment penalties, and refinance risk should align with the hold period.
4.How much equity and liquidity can I contribute? The minimum down payment is not necessarily the total cash needed to close.
5.What is my repayment or exit strategy? A successful financing structure must work beyond the closing date.
Why Working With a Commercial Loan Advisor Matters
Commercial lending is fragmented.
Different banks, credit unions, agency lenders, debt funds, SBA lenders, and private capital providers have different lending criteria.
A lender that is highly competitive for multifamily financing may have limited appetite for hotels, medical offices, vacant retail, or industrial outdoor storage.
That is where a commercial mortgage advisor can add value.
At CommLoan, we use the CUPID™ commercial mortgage marketplace to help evaluate borrower requirements and identify potential financing sources based on the transaction.
Rather than assuming that one bank's terms represent the entire market, the objective is to evaluate structures across relevant lending options.
This process can help borrowers compare:
Interest rates, fees, and total financing costs
Loan proceeds and equity requirements
Amortization, maturity, and balloon exposure
Recourse and guarantee provisions
Prepayment restrictions and exit flexibility
Property-specific underwriting requirements
The goal is not simply to obtain a loan approval. It is to identify a financing structure aligned with the investment or business plan.
Final Thoughts: The Right Loan Is More Than the Lowest Rate
The best commercial real estate loan is not necessarily the one advertising the lowest interest rate.
A lower-rate loan with restrictive prepayment provisions or an unfavorable maturity can be more expensive over the life of the investment than a more flexible alternative.
Whether you are acquiring a shopping center, purchasing an owner-occupied warehouse, refinancing an apartment complex, or repositioning a distressed commercial property, the financing structure should support the strategy.
Start with the property, the numbers, and the exit plan. Then find the capital that fits.
Ready to Compare Commercial Financing Options?
I'm Bill Rapp, CCIM, Director with CommLoan. I work with commercial real estate investors and business owners to evaluate financing strategies for acquisitions, refinancing, and development projects.
Explore your commercial financing options through the CommLoan marketplace.
Top of Form
Bottom of Form
Bill Rapp, CCIM
Director | CommLoan
📞 281-222-0433
📧 [email protected]
🌐 https://billrapp.commloan.com/
🌐 https://HoustonCommercialMortgage.com/
Commercial Real Estate Financing Nationwide
https://billrapp.commloan.com/
https://author.billrapponline.com/
https://www.amazon.com/dp/B0F32Z5BH2
https://veed.cello.so/FOmzTty6oi9
https://buymeacoffee.com/vikingente3
https://creplaybookseries.billrapponline.com
https://creplaybook.billrapponline.com/
©Bill Rapp, CCIM - Director - CommLoan
Main Office:
Medallion Funds
[email protected]
11920 Southern Highlands PKWY Suite 302Las Vegas, NV 89141
Texas Complaint and Recovery Fund Notice
All Rights Reserved Copyright © 2021 - Bill Rapp The Mortgage Viking | NMLS #228246