ATTENTION: For Those who are serious about Getting Pre-Qualified FAST!
Bill Rapp, Mortgage Originator: NMLS 228246
"Brokers Are Better.
Better Pricing, Better Service!"
Subscribe To My List Below To Get Your Mortgage Quote Now!
Simply enter your name and email below:
WITH PROVEN STRATEGIES & PROVEN RESULTS
HERE'S WHAT MY CLIENTS SAY:
What People Are Saying:
Excellent Service
Bill is an exceptional loan officer. He helped us to purchase our home with very personal and professional service. He helped us navigate the whole process from start to closing without any problems. We didn't think we're qualified to purchase a house, but Bill went above and beyond to find a way to help us achieve our goal. He always responded very quickly with our requests, he would come back with different options with comparison chart to clearly indicate how much we need for down payment, monthly payments, interest rates, closing costs etc.
We would highly recommend Bill to anyone in need of lending services. In fact, we have already recommended Bill to one of our friends on purchasing a house.
--- David Chan - Houston, TX
Bank Statement Lending!
William Rapp of Network Funding, L. P. was very professional and I felt comfortable in dealing with him. I will definitely recommend him to family and friends.
--- Ian F - Missouri City, TX
Professionalism - Expert In Home Style Loan
Bill is an expert in the topic, his explanations and online material make a difference and he is always there from the beginning to the end. He is committed to make thing happen.
--- Felipe Caldern & Carolina Angel Gutierrez
Great Service!
Bill Rapp's handling of our loan (even though out of state) was unparalleled to any service I have been through prior, including 3 different real estate transactions and multiple refinances. Extremely quick close, with great options and flexibility for my families needs. All around A+
--- Chris & Beth Sheehan - San Jose, CA
Knowledgeable and Responsive!
Bill was a pleasure to work with and he made the loan process fairly easy. He answered all questions I had very quickly and was straight forward in doing it. I would recommend Bill to others.
--- Wes Brady - Richmond, TX
Very professional and always returned our calls!
Bill takes a lot of pride in his job and is very dependable. They were very patient and understanding. He went out of his way and explained all my questions and concerns. They were very professional and returned my phone calls and emails. He did a great job and I fully recommend him.
--- Therese, Malcom & Shirley Teixeira - Katy, TX
Great Job!
Bill helped us out from beginning to end of loan process. The loan closed in a timely manner as Bill worked hard with bank to get our to the final steps.
--- Kamal & Theresa Wilson - Hartford, CT
Avid Problem-Solver and Absolute Pleasure to Work With!
Bill Rapp worked very hard to ensure that we closed our loan and were able to move into our new home. He always had alternatives to any problems we encountered while closing. He worked with us from the beginning identifying solutions to any problems that we were having. He was an absolute pleasure to work with!
--- Nikita Rayani & Sanit Tejani - Houston, TX
Awesome to work with!
Being a first-time buyer I came in with lots of questions and concerns. Bill was always available for any questions I had and answered everything to my satisfaction. Bill made the loan process so painless that I could still concentrate on other things. We ended up closing early which made things even better. If you are in need of a lender and want someone who is very approachable and stays on top of your loan then Bill is your guy.
--- Cesar Raya - Richmond, TX
Loan Declined by my bank, and he saved the day!
Bill, did an amazing job helping me close on my house. He took the reigns and reassured me the best route to take to help close. He was accountable, thorough and trustworthy. I will continue to work with Network Funding, L.P. when it comes to home buying in the future because of the quality of service Bill gave.
--- Jacob Smith - Boerne, TX
Bill Rapp Will Definitely Make It Happen!
Bill is the most kind, patient and helpful person I have ever known. He answers his phone calls and emails promptly. You can ask him a million questions, and he will answer each and every one of them. Before I started working with Bill, I had been turned down for a home loan, because of some past credit issues I had, plus I was a single mother. However, once I started working with Bill, he was able to quickly get me a home loan, with a good interest rate. I would recommend that you call him, as he will help you.
--- Corinne Wilson - Roselle, NJ
Knowledgeable, Honest, Trustworthy, and Reliable!
"I will definitely keep you in mind. If anyone I know needs financing, I will send them your way!"
--- Jon & Andrea Saleem, CRPC Financial Advisor - Houston, TX
Best Dam Mortgage Guy a man could know!
"Hands down the best loan experience to date!"
--- Gabe & Chelsea Jackson - Pearland, TX
Phenomenal, Hard Working and Never Quits!
Had a stupid foreclosure that could have been avoided if ex’s attny would have sent my buy out offer. So Bill was able to push this through with a 4 year foreclosure. He worked his butt off, was very diligent with his communication; and was very professional talking to me even when I was screaming and/or crying at him. Highly recommend this lender. He really go to the ends of the earth to help you!
--- Liz Keeter - Harlingen, TX
Exceptional customer service!
Bill is the most kind, patient and helpful person I have ever known. He answers his phone calls and emails promptly. You can ask him a million questions, and he will answer each and every one of them. Before I started working with Bill, I had been turned down for a home loan, because of some past credit issues I had, plus I was a single mother. However, once I started working with Bill, he was able to quickly get me a home loan, with a good interest rate. I would recommend that you call him, as he will help you.
--- Isha Lopez & Mauricio Garcia - Houston, TX
Service with a capitol S
Bill went above and beyond at every turn. He worked late on Saturday, he worked late all the time. We wanted to close ASAP and he really helped make it happen for us.
--- Jeff & Wendy Heger - Houston, TX
Best Buying Experience!
I would would highly recommend going with Network Funding LP. As a first time home buyer I didn't know what to expect. Bill Rapp was very helpful in answering all my questions and guided me through all ghe steps. I couldn't have asked for a better buying experience!
--- Tabitha Turner - Humble, TX
Would recommend him and use him again!
Very involved and professional . Kept me informed and up to date on everything that was going on Went with me closing and was very helpful and knowledgeable.
--- Kathy Ward - Houston, TX
Great experience!
Well I meet bill back in December 2016 he got recommended by my real estate agent we had a house in sight and started the process to get approved but we fail due to my work history and credit bill told me not to give up and put me in contact with a credit repair company they help me bring my score up and bill walk me thru the process of getting a new line so this time around we got approved before looking for our house after we found it we still had a couple of hick up but with bills help on Sunday 6-18-17 to be exact Father's Day bill called me to give me the great news that we had got approved and the closing date was as scheduled bill was more than just a lender to my family he became a friend and I'm alway going to have him in mind for any other financial situation.
--- Alejandres Felimon - Richmond, TX
I really liked his attitude!
I wouldn't usually say this but the way he had handled my mortgage was really pleasant. I personally enjoyed the time spent with him while we discussed feasible rates. He's a great man with a great personality and he offered really low interests as well. Definitely recommend him to others.
--- Tom Troiano - Atlantic City, NJ
He's nothing short of a miracle!
I'm a self-employed businessman and had him figure out the mortgage of the house after 30% down payment. The interest rates I received were incredibly low given what I had thought of earlier. One other important thing to note was that I hadn't really taken any loans earlier, so I had no credit history. He helped me out with all that as well so I can't really call him anything else but a miracle.
--- Fran Suarez - Cleveland, OH
He's really helpful!
I made a bid to him and the very same day he gave me an offer which I couldn't resist. It was too intimidating with those incredibly low interest rates and all, thoroughly recommend him.
--- Kenny Mickle - Houston, TX
Expeditious!
Bill was very expeditious and made it real easy going through the loan process. I felt he was on top of things.
I deal with investment properties and will more than likely call on him again.
--- Wayne King - Pensacola, FL
Bill was great!
Bill made us feel like a friend all the way thru the process. He was patient and explained everything he needed clearly. He was available ANYTIME we had questions or needed more information. Hopefully we won’t go thru this process again anytime soon, but if we do - we’d choose Bill! =)
--- Barbra & Nick Grimmer - Austin, TX
Great broker!
Bill was a great broker to work with. As first time home buyers we had many questions about the process, Bill took the time to help us even calling us back on weekends with answers. I would not hesitate to recommend him to anyone looking for a broker to work with.
--- Murray & Lisa Turner - Pensacola, FL
Outstanding service!
I couldn't have been more pleased with Bill's level of service. He made what is typically a lengthy, arduous process far quicker and easier at every turn. I'm extremely comfortable recommending Bill to friends and family, and will definitely utilize his services again!
--- Jim Lipari - Austin, TX
Step-by-Step Guide to the VA Loan Process
6 Easy Steps to a VA Loan
For many borrowers, applying for any kind of mortgage may seem daunting.
But, when broken down, this rundown of 6 steps to getting a VA loan is easy to understand.
1. Select a VA-approved Lender
On the surface, it might appear that any lender will do. However, if you dig a little deeper, you may discover that not all lenders are the same. First, only lenders approved by the U.S. Department of Veterans Affairs can originate VA mortgages. Secondly, some lenders focus primarily on conventional loans, while others concentrate almost exclusively on the VA loan program for military clients. Using a VA specialty lender with extensive knowledge about the VA loan process vs. a lender who only funds a few VA mortgages a year may translate into an easier and quicker loan process. To connect with a VA specialty lender, please click here.
2. Obtain a Certificate of Eligibility (COE)
An experienced lender can help you obtain what’s called a Certificate of Eligibility (COE). The COE will prove that you meet initial eligibility standards for VA loan benefits. It will also let the lender know how much entitlement you can receive, which is the amount the Department of Veterans Affairs will guarantee on your VA loan. To get your COE, you’ll need to give your lender a bit of information about your military service. Usually, a COE can be acquired online instantly through a lender’s portal or through the eBenefits portal on the va.gov website. Those servicemembers or surviving spouses whose COEs cannot be obtained online will have to get theirs by mail. A VA lender or the VA can help direct you to the right resource for your specific situation.
3. Pre-Qualify for Your Loan Amount
Pre-qualifying is important, but not required. By choosing to complete this step you can save some time and potential surprises later in the process. To pre-qualify for your loan amount, you’ll have a candid conversation with your VA loan professional about your income, credit history, employment, marital status and other factors. Giving your lender complete details during the pre-qualifying step can help prevent surprises later during underwriting. The pre-qualifying step can also reveal areas that need improvement before you can be approved, such as credit or debt-to-income ratio. While a prequalification letter gives you a ballpark price range for house hunting, it does not guarantee that you will be approved for a loan, and your lender will later have to verify the information you provide. To get a loan requires later final approval by underwriting once all documents have been received and reviewed (see Step 5).
4. Go House Hunting & Find Home
The fourth step is usually one borrowers enjoy because they get to look at homes they might consider buying. Working with a real estate professional who specializes in the VA process can help you get the most out of your benefits. This is true because the VA allows certain fees and costs to be paid by the seller (if both you and the seller agree), and a knowledgeable agent will know this and help you negotiate seller-paid fees. Once you’ve got a signed purchase agreement, you can move forward in the VA loan process.
5. Lender Processes Application
& Orders VA Appraisal
A signed purchase contract is the document you’ll need to finish your initial application. Once your lender has the contract, they will order the VA appraisal. Here again, not just any appraiser will do. Only a professional who is certified to perform appraisals to VA standards can evaluate the home being considered for VA financing. The VA appraiser will make sure the price you’ve agreed to pay for the home corresponds with the current value. Another very important part of the VA appraisal is to inspect the home to make sure it meets the VA minimum property requirements (VA MPRs). However, the VA appraisal does not take the place of a home inspection, which focuses on code violations, defects and the condition of the property. While many borrowers have heard horror stories about the length of the VA appraisal process, the Department of Veterans Affairs gives the appraisers 10 days from order to completion barring extenuating circumstances. While you’re waiting for appraisal documents, you’ll be busy submitting documents of your own to your VA-approved lender to show you have the ability to qualify for the loan. If the home passes appraisal for value and VA minimum property requirements, and it’s verified by the lender that you qualify for your loan, the underwriter will give his or her stamp of approval.
6. Close on Your Loan and Move In
After being approved by the underwriter, all that is left to do is close and move in. During closing, the property legally transfers from the former owner to you. Closing is a step that requires you to sign documents that confirm you understand and agree to the terms of the loan. You will need to provide proof of homeowners insurance and, if required, pay closing costs. Once you’ve signed all your closing documents, you’ll get the keys to your new home.
While these steps may not happen in the order above or be a required part (such as prequalification)*, they represent the typical process for the applicant in obtaining a VA purchase loan. Your lender may need to take other steps. For more information about VA loans, contact an experienced VA-approved lender.
My best advice to you is to call Bill Rapp, the Mortgage Viking, today to discuss your options 281-222-0433.
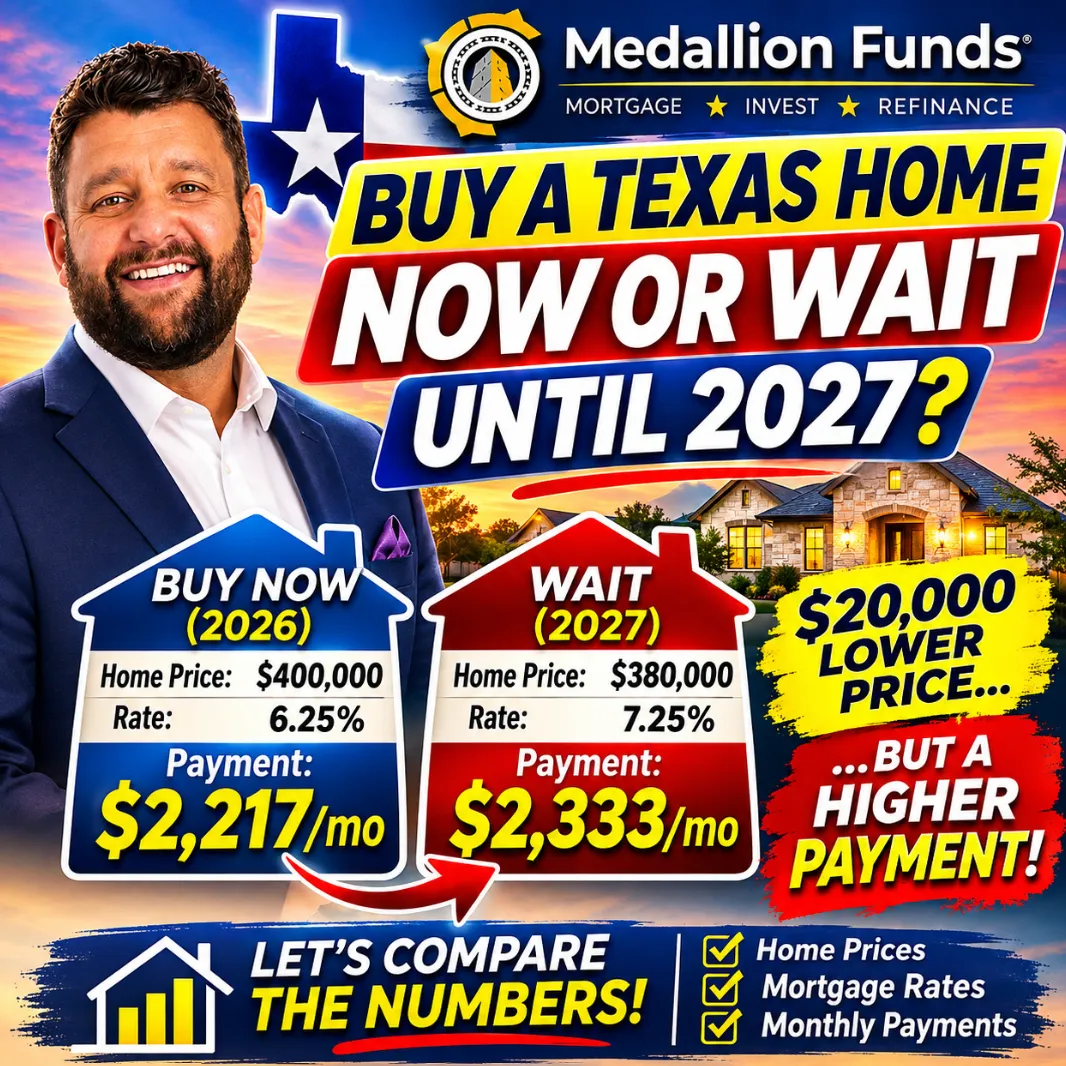
🏡 Texas Housing Market 2027: Buy Now or Wait?
🏡 Texas Housing Market 2027: Buy Now or Wait?
🚨 Texas Home Prices Fall, Mortgage Rates Rise: Now What?
______________________________________________________________________________
🏡 Texas Housing Market 2027: Should You Buy Now or Wait?
What happens if Texas home prices fall in 2027, but mortgage rates rise? The answer could change your homebuying strategy.
For homebuyers across Houston, Katy, Fulshear, Dallas, Austin, San Antonio, and other Texas markets, one question continues to dominate conversations:
Should I buy a house now or wait until 2027?
Some buyers expect home prices to decline. Others believe mortgage rates will fall, creating better affordability. But what happens if the market moves in opposite directions?
Imagine buying a home for less money next year, only to discover that your monthly mortgage payment is actually higher.
That scenario is entirely possible.
I'm Bill Rapp, CCIM, Capital Advisor with Medallion Funds. I work with homebuyers, homeowners, and real estate investors to evaluate mortgage financing options and make informed real estate decisions.
Let's examine the numbers behind buying a Texas home in late 2026 versus waiting until 2027.
Texas Housing Market Outlook: What Could Happen in 2027?
Texas housing markets are not moving in perfect synchronization.
Houston, Dallas–Fort Worth, Austin, and San Antonio have different housing inventories, employment trends, construction activity, and neighborhood-level supply-and-demand conditions.
Three factors will be particularly important heading into 2027:
1. Housing inventory: More available homes can give buyers additional negotiating leverage, particularly when properties remain listed longer.
2. Mortgage interest rates: Even relatively small rate changes can materially affect purchasing power and monthly payments.
3. Local home prices: Prices may soften in some neighborhoods while remaining stable or increasing in others.
The key is understanding that lower home prices do not automatically translate into more affordable homeownership.
Buy Now vs. Wait Until 2027: The $400,000 Texas Home Example
Let's compare two hypothetical purchasing scenarios.
Scenario A: Buy a Texas Home in 2026
Assume you purchase a home with these terms:
·Purchase price: $400,000
·Down payment: 10%, or $40,000
·Mortgage amount: $360,000
·Interest rate: 6.25%
·Loan term: 30-year fixed
Your estimated monthly principal and interest payment would be approximately $2,217.
Scenario B: Wait Until 2027
Now imagine home prices decline by 5%, but mortgage rates increase to 7.25%.
·Purchase price: $380,000
·Down payment: 10%, or $38,000
·Mortgage amount: $342,000
·Interest rate: 7.25%
·Loan term: 30-year fixed
Your estimated monthly principal and interest payment would be approximately $2,333.
Despite paying $20,000 less for the property, you would have a monthly principal and interest payment approximately $116 higher.
That's roughly $1,392 more per year.
These are illustrative scenarios, not predictions or current rate quotes. Actual payments depend on the loan terms, borrower qualifications, and applicable financing costs.
Why Mortgage Rates Matter More Than Many Buyers Realize
When shopping for a home, buyers naturally focus on the purchase price.
But mortgage rates influence how much that home costs to finance.
A higher rate can offset the benefit of a lower purchase price, especially when financing most of the purchase.
Conversely, lower mortgage rates can sometimes improve affordability even when home prices remain unchanged.
The important distinction is between purchase price, monthly payment, and total cost of ownership.
All three matter.
A lower price can reduce the down payment and potentially the property tax assessment over time. But a higher mortgage rate can increase financing expenses substantially.
That is why buyers should compare complete financing scenarios instead of making decisions based on headlines.
What If Texas Home Prices and Mortgage Rates Both Fall?
This would generally be a favorable scenario for buyers.
For example, imagine that a $400,000 home declines to $380,000 while mortgage rates decrease from 6.25% to 5.75%.
With 10% down, the new mortgage amount would be $342,000.
The estimated monthly principal and interest payment would decline to approximately $1,996.
That represents a reduction of roughly $221 per month compared with the original $400,000 purchase scenario.
However, there is another consideration.
If lower mortgage rates attract more buyers into the market, competition could increase.
More competition may lead to fewer seller concessions, shorter negotiation windows, and upward pressure on prices in desirable neighborhoods.
Waiting can create opportunities, but it also introduces uncertainty.
Texas Property Taxes and Insurance: The Hidden Affordability Factors
In Texas, the mortgage payment is only part of the homeownership equation.
Buyers must also evaluate:
·Property taxes and applicable exemptions
·Homeowners insurance premiums
·Flood insurance where appropriate or required
·Mortgage insurance, if applicable
·HOA fees
·Maintenance and repair expenses
For example, a $400,000 property with an illustrative effective property tax rate of 2% would generate approximately $8,000 in annual property taxes before considering exemptions or other adjustments.
That is approximately $667 per month.
Property tax rates, taxable values, exemptions, and special assessments vary significantly by location.
Insurance costs can also vary based on property characteristics, roof condition, claims history, and weather exposure.
In areas such as Katy, Fulshear, Richmond, and West Houston, buyers should evaluate the property's specific tax districts, potential MUD assessments, and insurance requirements before making an offer.
The best mortgage decision considers the complete monthly housing expense—not just principal and interest.
Should Move-Up Buyers Wait Until 2027?
Move-up buyers face an additional challenge.
They are not simply purchasing a new home. They may also be selling an existing property and replacing an older mortgage with a new one.
Suppose you purchased your current home several years ago with a 3% mortgage rate.
Selling that property and purchasing a larger home with a higher-rate mortgage could substantially increase your monthly payment.
But mortgage rates are not the only factor.
You may need additional bedrooms, a better location, more space for your family, or a home that better accommodates your lifestyle.
Before deciding to move, evaluate:
Your existing equity: How much money will remain after paying off your mortgage and selling expenses?
Your replacement mortgage: What would the new monthly payment look like after applying your available equity?
Your current interest rate: How much additional financing expense would you incur by replacing your existing mortgage?
Your timeline: Is the move optional, or does your household need different housing now?
For some homeowners, waiting makes financial sense.
For others, the lifestyle benefits and availability of a suitable property may justify moving sooner.
Can You Buy Now and Refinance Later?
Potentially, but refinancing should never be treated as guaranteed.
If mortgage rates decline after purchasing, homeowners may have an opportunity to refinance into a lower rate.
However, refinancing depends on several factors:
·Future mortgage rates
·Credit and income qualifications
·Property value and available equity
·Closing costs
·Loan program requirements
A refinance can also restart or extend the repayment period, which may increase total interest costs even when the monthly payment falls.
Buy based on a payment you can comfortably afford today—not one that requires a future refinance to work.
Mortgage Strategies That Could Help Texas Homebuyers
At Medallion Funds, we help buyers evaluate mortgage options based on their financial circumstances.
Depending on eligibility and program availability, those options may include:
Conventional mortgages: Financing options for qualified borrowers, including certain low-down-payment programs.
FHA loans: Government-insured mortgages with flexible qualifying criteria for eligible buyers.
VA loans: Valuable financing options for eligible veterans, active-duty service members, and certain surviving spouses.
Doctor and dentist loans: Specialized programs that may offer flexible down payment or student loan treatment for qualifying medical professionals.
Jumbo mortgages: Financing for higher-priced homes that exceed applicable conforming loan limits.
Bank statement loans: Alternative income documentation programs that may benefit qualified self-employed borrowers.
Seller concessions and temporary rate buydowns: Negotiated structures that may help eligible buyers manage upfront costs or initial payments, subject to program restrictions.
The right financing structure can sometimes have a greater impact on your purchasing decision than attempting to predict the market.
Five Questions to Ask Before Buying a Texas Home
Before deciding whether to buy now or wait until 2027, ask yourself:
1.Can I comfortably afford the complete monthly payment today?
2.Do I have sufficient cash for my down payment, closing costs, and emergency reserves?
3.How long do I realistically expect to own this home?
4.What happens to my budget if insurance, taxes, or maintenance costs increase?
5.Am I buying because the property fits my needs, or because I am trying to time the market?
These questions help separate a sound financial decision from speculation about future prices and rates.
Final Verdict: Buy Now or Wait Until 2027?
There is no universal answer.
Buying now may make sense if you find the right property, have stable income, can comfortably afford the payment, and expect to remain in the home long enough to justify the transaction costs.
Waiting may make sense if you need to improve your credit, build additional savings, reduce debt, or gain greater financial stability.
The biggest mistake is assuming that falling home prices will automatically make homes more affordable.
A cheaper home with a higher mortgage rate can cost more every month.
Instead of trying to predict the perfect time to buy, focus on the purchase price, financing structure, complete housing expense, and long-term ownership strategy.
Ready to Compare Your Mortgage Options?
I'm Bill Rapp, CCIM, Capital Advisor with Medallion Funds.
Whether you're buying your first Texas home, relocating, or considering a move-up purchase, I can help you evaluate financing options and compare realistic monthly payment scenarios.
Bill Rapp
Partner & Director of Capital Advisory | Medallion Funds
Commercial Lending Nationwide
Residential Lending in AL, CA, CO, NV & TXBottom of Form
📞 Call or Text: 281-222-0433
🌐 Website: https://billrapponline.com
🎥 Subscribe to Mortgage Viking: https://www.youtube.com/@billrapp-medallion-funds
https://www.billrapponline.com/
https://findamortgagebroker.com/Profile/WilliamRappJr28883
https://billrapp.commloan.com/
https://billrapponline.com/financingfuturescre-houston-katy
https://houstoncommercialmortgage.com/
https://author.billrapponline.com
https://doctorvideo.billrapponline.com/
https://veteransvideo.billrapponline.com/
https://mortgageviking.billrapponline.com/
https://fha203h.billrapponline.com/
https://renovationvideo.billrapponline.com
https://medallionfunds.com/bill-rapp/
https://www.amazon.com/dp/B0F32Z5BH2
https://veed.cello.so/FOmzTty6oi9
https://buymeacoffee.com/vikingente3
https://creplaybookseries.billrapponline.com
https://creplaybook.billrapponline.com/
© Bill Rapp, Medallion Funds LLC, Director of Capital Advisory
Main Office:
Medallion Funds
[email protected]
11920 Southern Highlands PKWY Suite 302Las Vegas, NV 89141
Texas Complaint and Recovery Fund Notice
All Rights Reserved Copyright © 2021 - Bill Rapp The Mortgage Viking | NMLS #228246