ATTENTION: For Those who are serious about Getting Pre-Qualified FAST!
Bill Rapp, Mortgage Originator: NMLS 228246
"Brokers Are Better.
Better Pricing, Better Service!"
Subscribe To My List Below To Get Your Mortgage Quote Now!
Simply enter your name and email below:
WITH PROVEN STRATEGIES & PROVEN RESULTS
HERE'S WHAT MY CLIENTS SAY:
What People Are Saying:
Excellent Service
Bill is an exceptional loan officer. He helped us to purchase our home with very personal and professional service. He helped us navigate the whole process from start to closing without any problems. We didn't think we're qualified to purchase a house, but Bill went above and beyond to find a way to help us achieve our goal. He always responded very quickly with our requests, he would come back with different options with comparison chart to clearly indicate how much we need for down payment, monthly payments, interest rates, closing costs etc.
We would highly recommend Bill to anyone in need of lending services. In fact, we have already recommended Bill to one of our friends on purchasing a house.
--- David Chan - Houston, TX
Bank Statement Lending!
William Rapp of Network Funding, L. P. was very professional and I felt comfortable in dealing with him. I will definitely recommend him to family and friends.
--- Ian F - Missouri City, TX
Professionalism - Expert In Home Style Loan
Bill is an expert in the topic, his explanations and online material make a difference and he is always there from the beginning to the end. He is committed to make thing happen.
--- Felipe Caldern & Carolina Angel Gutierrez
Great Service!
Bill Rapp's handling of our loan (even though out of state) was unparalleled to any service I have been through prior, including 3 different real estate transactions and multiple refinances. Extremely quick close, with great options and flexibility for my families needs. All around A+
--- Chris & Beth Sheehan - San Jose, CA
Knowledgeable and Responsive!
Bill was a pleasure to work with and he made the loan process fairly easy. He answered all questions I had very quickly and was straight forward in doing it. I would recommend Bill to others.
--- Wes Brady - Richmond, TX
Very professional and always returned our calls!
Bill takes a lot of pride in his job and is very dependable. They were very patient and understanding. He went out of his way and explained all my questions and concerns. They were very professional and returned my phone calls and emails. He did a great job and I fully recommend him.
--- Therese, Malcom & Shirley Teixeira - Katy, TX
Great Job!
Bill helped us out from beginning to end of loan process. The loan closed in a timely manner as Bill worked hard with bank to get our to the final steps.
--- Kamal & Theresa Wilson - Hartford, CT
Avid Problem-Solver and Absolute Pleasure to Work With!
Bill Rapp worked very hard to ensure that we closed our loan and were able to move into our new home. He always had alternatives to any problems we encountered while closing. He worked with us from the beginning identifying solutions to any problems that we were having. He was an absolute pleasure to work with!
--- Nikita Rayani & Sanit Tejani - Houston, TX
Awesome to work with!
Being a first-time buyer I came in with lots of questions and concerns. Bill was always available for any questions I had and answered everything to my satisfaction. Bill made the loan process so painless that I could still concentrate on other things. We ended up closing early which made things even better. If you are in need of a lender and want someone who is very approachable and stays on top of your loan then Bill is your guy.
--- Cesar Raya - Richmond, TX
Loan Declined by my bank, and he saved the day!
Bill, did an amazing job helping me close on my house. He took the reigns and reassured me the best route to take to help close. He was accountable, thorough and trustworthy. I will continue to work with Network Funding, L.P. when it comes to home buying in the future because of the quality of service Bill gave.
--- Jacob Smith - Boerne, TX
Bill Rapp Will Definitely Make It Happen!
Bill is the most kind, patient and helpful person I have ever known. He answers his phone calls and emails promptly. You can ask him a million questions, and he will answer each and every one of them. Before I started working with Bill, I had been turned down for a home loan, because of some past credit issues I had, plus I was a single mother. However, once I started working with Bill, he was able to quickly get me a home loan, with a good interest rate. I would recommend that you call him, as he will help you.
--- Corinne Wilson - Roselle, NJ
Knowledgeable, Honest, Trustworthy, and Reliable!
"I will definitely keep you in mind. If anyone I know needs financing, I will send them your way!"
--- Jon & Andrea Saleem, CRPC Financial Advisor - Houston, TX
Best Dam Mortgage Guy a man could know!
"Hands down the best loan experience to date!"
--- Gabe & Chelsea Jackson - Pearland, TX
Phenomenal, Hard Working and Never Quits!
Had a stupid foreclosure that could have been avoided if ex’s attny would have sent my buy out offer. So Bill was able to push this through with a 4 year foreclosure. He worked his butt off, was very diligent with his communication; and was very professional talking to me even when I was screaming and/or crying at him. Highly recommend this lender. He really go to the ends of the earth to help you!
--- Liz Keeter - Harlingen, TX
Exceptional customer service!
Bill is the most kind, patient and helpful person I have ever known. He answers his phone calls and emails promptly. You can ask him a million questions, and he will answer each and every one of them. Before I started working with Bill, I had been turned down for a home loan, because of some past credit issues I had, plus I was a single mother. However, once I started working with Bill, he was able to quickly get me a home loan, with a good interest rate. I would recommend that you call him, as he will help you.
--- Isha Lopez & Mauricio Garcia - Houston, TX
Service with a capitol S
Bill went above and beyond at every turn. He worked late on Saturday, he worked late all the time. We wanted to close ASAP and he really helped make it happen for us.
--- Jeff & Wendy Heger - Houston, TX
Best Buying Experience!
I would would highly recommend going with Network Funding LP. As a first time home buyer I didn't know what to expect. Bill Rapp was very helpful in answering all my questions and guided me through all ghe steps. I couldn't have asked for a better buying experience!
--- Tabitha Turner - Humble, TX
Would recommend him and use him again!
Very involved and professional . Kept me informed and up to date on everything that was going on Went with me closing and was very helpful and knowledgeable.
--- Kathy Ward - Houston, TX
Great experience!
Well I meet bill back in December 2016 he got recommended by my real estate agent we had a house in sight and started the process to get approved but we fail due to my work history and credit bill told me not to give up and put me in contact with a credit repair company they help me bring my score up and bill walk me thru the process of getting a new line so this time around we got approved before looking for our house after we found it we still had a couple of hick up but with bills help on Sunday 6-18-17 to be exact Father's Day bill called me to give me the great news that we had got approved and the closing date was as scheduled bill was more than just a lender to my family he became a friend and I'm alway going to have him in mind for any other financial situation.
--- Alejandres Felimon - Richmond, TX
I really liked his attitude!
I wouldn't usually say this but the way he had handled my mortgage was really pleasant. I personally enjoyed the time spent with him while we discussed feasible rates. He's a great man with a great personality and he offered really low interests as well. Definitely recommend him to others.
--- Tom Troiano - Atlantic City, NJ
He's nothing short of a miracle!
I'm a self-employed businessman and had him figure out the mortgage of the house after 30% down payment. The interest rates I received were incredibly low given what I had thought of earlier. One other important thing to note was that I hadn't really taken any loans earlier, so I had no credit history. He helped me out with all that as well so I can't really call him anything else but a miracle.
--- Fran Suarez - Cleveland, OH
He's really helpful!
I made a bid to him and the very same day he gave me an offer which I couldn't resist. It was too intimidating with those incredibly low interest rates and all, thoroughly recommend him.
--- Kenny Mickle - Houston, TX
Expeditious!
Bill was very expeditious and made it real easy going through the loan process. I felt he was on top of things.
I deal with investment properties and will more than likely call on him again.
--- Wayne King - Pensacola, FL
Bill was great!
Bill made us feel like a friend all the way thru the process. He was patient and explained everything he needed clearly. He was available ANYTIME we had questions or needed more information. Hopefully we won’t go thru this process again anytime soon, but if we do - we’d choose Bill! =)
--- Barbra & Nick Grimmer - Austin, TX
Great broker!
Bill was a great broker to work with. As first time home buyers we had many questions about the process, Bill took the time to help us even calling us back on weekends with answers. I would not hesitate to recommend him to anyone looking for a broker to work with.
--- Murray & Lisa Turner - Pensacola, FL
Outstanding service!
I couldn't have been more pleased with Bill's level of service. He made what is typically a lengthy, arduous process far quicker and easier at every turn. I'm extremely comfortable recommending Bill to friends and family, and will definitely utilize his services again!
--- Jim Lipari - Austin, TX
Step-by-Step Guide to the VA Loan Process
6 Easy Steps to a VA Loan
For many borrowers, applying for any kind of mortgage may seem daunting.
But, when broken down, this rundown of 6 steps to getting a VA loan is easy to understand.
1. Select a VA-approved Lender
On the surface, it might appear that any lender will do. However, if you dig a little deeper, you may discover that not all lenders are the same. First, only lenders approved by the U.S. Department of Veterans Affairs can originate VA mortgages. Secondly, some lenders focus primarily on conventional loans, while others concentrate almost exclusively on the VA loan program for military clients. Using a VA specialty lender with extensive knowledge about the VA loan process vs. a lender who only funds a few VA mortgages a year may translate into an easier and quicker loan process. To connect with a VA specialty lender, please click here.
2. Obtain a Certificate of Eligibility (COE)
An experienced lender can help you obtain what’s called a Certificate of Eligibility (COE). The COE will prove that you meet initial eligibility standards for VA loan benefits. It will also let the lender know how much entitlement you can receive, which is the amount the Department of Veterans Affairs will guarantee on your VA loan. To get your COE, you’ll need to give your lender a bit of information about your military service. Usually, a COE can be acquired online instantly through a lender’s portal or through the eBenefits portal on the va.gov website. Those servicemembers or surviving spouses whose COEs cannot be obtained online will have to get theirs by mail. A VA lender or the VA can help direct you to the right resource for your specific situation.
3. Pre-Qualify for Your Loan Amount
Pre-qualifying is important, but not required. By choosing to complete this step you can save some time and potential surprises later in the process. To pre-qualify for your loan amount, you’ll have a candid conversation with your VA loan professional about your income, credit history, employment, marital status and other factors. Giving your lender complete details during the pre-qualifying step can help prevent surprises later during underwriting. The pre-qualifying step can also reveal areas that need improvement before you can be approved, such as credit or debt-to-income ratio. While a prequalification letter gives you a ballpark price range for house hunting, it does not guarantee that you will be approved for a loan, and your lender will later have to verify the information you provide. To get a loan requires later final approval by underwriting once all documents have been received and reviewed (see Step 5).
4. Go House Hunting & Find Home
The fourth step is usually one borrowers enjoy because they get to look at homes they might consider buying. Working with a real estate professional who specializes in the VA process can help you get the most out of your benefits. This is true because the VA allows certain fees and costs to be paid by the seller (if both you and the seller agree), and a knowledgeable agent will know this and help you negotiate seller-paid fees. Once you’ve got a signed purchase agreement, you can move forward in the VA loan process.
5. Lender Processes Application
& Orders VA Appraisal
A signed purchase contract is the document you’ll need to finish your initial application. Once your lender has the contract, they will order the VA appraisal. Here again, not just any appraiser will do. Only a professional who is certified to perform appraisals to VA standards can evaluate the home being considered for VA financing. The VA appraiser will make sure the price you’ve agreed to pay for the home corresponds with the current value. Another very important part of the VA appraisal is to inspect the home to make sure it meets the VA minimum property requirements (VA MPRs). However, the VA appraisal does not take the place of a home inspection, which focuses on code violations, defects and the condition of the property. While many borrowers have heard horror stories about the length of the VA appraisal process, the Department of Veterans Affairs gives the appraisers 10 days from order to completion barring extenuating circumstances. While you’re waiting for appraisal documents, you’ll be busy submitting documents of your own to your VA-approved lender to show you have the ability to qualify for the loan. If the home passes appraisal for value and VA minimum property requirements, and it’s verified by the lender that you qualify for your loan, the underwriter will give his or her stamp of approval.
6. Close on Your Loan and Move In
After being approved by the underwriter, all that is left to do is close and move in. During closing, the property legally transfers from the former owner to you. Closing is a step that requires you to sign documents that confirm you understand and agree to the terms of the loan. You will need to provide proof of homeowners insurance and, if required, pay closing costs. Once you’ve signed all your closing documents, you’ll get the keys to your new home.
While these steps may not happen in the order above or be a required part (such as prequalification)*, they represent the typical process for the applicant in obtaining a VA purchase loan. Your lender may need to take other steps. For more information about VA loans, contact an experienced VA-approved lender.
My best advice to you is to call Bill Rapp, the Mortgage Viking, today to discuss your options 281-222-0433.
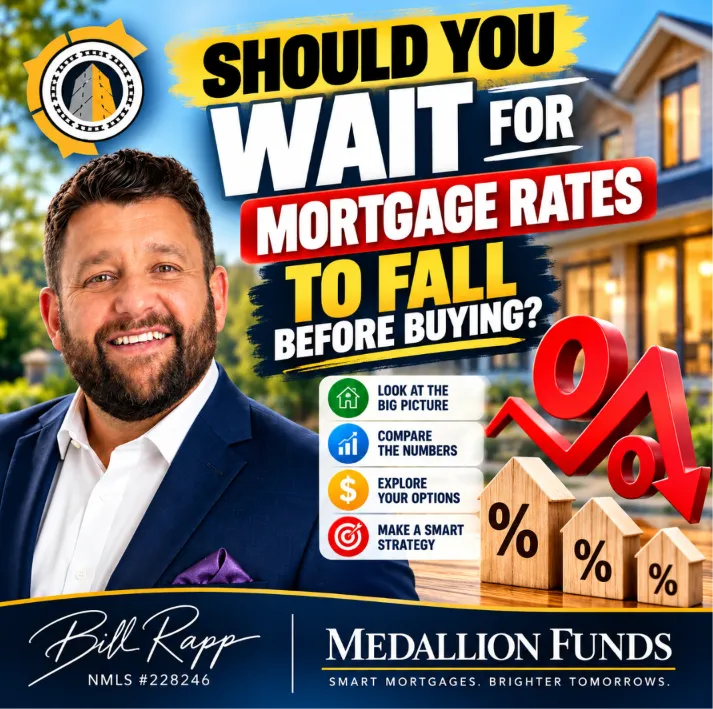
🏡 Should You Wait for Mortgage Rates to Fall Before Buying a Home? The Real Cost of Waiting 📉
🏡 Should You Wait for Mortgage Rates to Fall Before Buying a Home? The Real Cost of Waiting 📉
📉 Mortgage Rates in 2026: Buy a House Now or Wait for Lower Interest Rates? 🏠
______________________________________________________________________________
🏡 Should You Wait for Mortgage Rates to Fall Before Buying a Home? The Real Cost of Waiting 📉
If you're thinking about buying a home in 2026, there's probably one question running through your mind:
Should I buy a house now, or wait for mortgage rates to drop?
It's a reasonable question. Mortgage interest rates directly influence your monthly payment, purchasing power, and long-term borrowing costs.
But here's what many buyers overlook: Waiting for lower mortgage rates doesn't necessarily mean you'll get a better deal on a home.
Home prices, housing inventory, buyer competition, your personal finances, and your long-term goals all influence whether buying now or waiting makes financial sense.
At Medallion Funds, I help homebuyers evaluate their financing options and develop mortgage strategies that fit their circumstances—not simply react to interest rate headlines.
Let's examine the factors that matter most.
1. 📉 Will Mortgage Rates Fall in 2026?
Mortgage rates are influenced by several economic factors, including:
·Inflation and inflation expectations
·U.S. Treasury yields
·Federal Reserve monetary policy
·Economic growth and employment conditions
·Mortgage-backed securities markets
·Lender pricing and risk considerations
One common misconception is that mortgage rates automatically decline whenever the Federal Reserve cuts its benchmark interest rate.
That's not necessarily true.
Fixed mortgage rates are more closely connected to longer-term bond markets and mortgage-backed securities pricing than to the Fed's short-term policy rate.
Even if the Federal Reserve reduces rates, mortgage rates could remain relatively stable—or increase—depending on market expectations.
The bottom line? Nobody can consistently predict the exact direction or timing of mortgage rates.
Rather than attempting to time the market perfectly, buyers should evaluate the financial implications of purchasing under today's available terms.
2. 🏠 What Happens to Home Prices When Mortgage Rates Drop?
Lower mortgage rates generally improve purchasing power.
That sounds like great news for buyers—and it can be.
However, there's another side to the equation.
When borrowing becomes more affordable, more potential buyers may enter the housing market.
Depending on available inventory, that additional demand can create:
·More competition for desirable properties
·Multiple-offer situations
·Fewer seller concessions
·Greater pressure on home prices
·Less negotiating leverage for buyers
Imagine you're shopping for a home in Katy, Texas.
Today, a seller might be willing to negotiate on price, contribute toward closing costs, or offer a mortgage rate buydown.
If mortgage rates decline and buyer activity increases, those incentives could become harder to negotiate.
Of course, lower rates don't guarantee higher home prices. Employment conditions, housing supply, local economic trends, and affordability also influence the market.
The important point is that mortgage rates and home prices must be evaluated together.
3. 💰 The Real Numbers: Buying Now vs. Waiting
Let's compare two hypothetical homebuying scenarios.
Scenario A: Buy Today
Assume you're purchasing a home with the following terms:
·Purchase price: $400,000
·Down payment: 10% ($40,000)
·Mortgage amount: $360,000
·Interest rate: 6.50%
·Loan term: 30-year fixed
Your estimated monthly principal and interest payment would be approximately $2,275.
Scenario B: Wait for Rates to Fall
Now assume you wait one year.
Mortgage rates decline to 5.75%, but the home's price increases by 5%.
Your new financing scenario becomes:
·Purchase price: $420,000
·Down payment: 10% ($42,000)
·Mortgage amount: $378,000
·Interest rate: 5.75%
·Loan term: 30-year fixed
Your estimated monthly principal and interest payment would be approximately $2,206.
Side-by-Side Comparison
Factor | Buy Now | Wait One Year |
Home price | $400,000 | $420,000 |
Down payment | $40,000 | $42,000 |
Loan amount | $360,000 | $378,000 |
Interest rate | 6.50% | 5.75% |
Monthly principal & interest | $2,275 | $2,206 |
Difference | — | $69 less/month |
In this hypothetical example, waiting produces a lower monthly principal and interest payment.
But the buyer also pays $20,000 more for the property and needs an additional $2,000 for the down payment.
If the buyer currently rents, another year of rent payments may also influence the overall financial comparison.
And if home prices stay flat or decline instead, waiting could produce a better result.
The lesson: There is no universal financial winner. The numbers depend on what actually happens in your market.
These examples are illustrative, not current rate quotes. Payments exclude property taxes, homeowners insurance, mortgage insurance, HOA dues, and closing costs. Actual loan terms and eligibility vary.
4. 🔄 Can You Buy Now and Refinance Later?
One strategy buyers often consider is purchasing a home they can comfortably afford today and refinancing if interest rates become more favorable.
That can be a reasonable approach, provided the initial mortgage makes financial sense on its own.
For example, consider a $360,000 mortgage at 6.50%.
The initial monthly principal and interest payment is approximately $2,275.
If the borrower later qualifies to refinance the remaining balance at 5.50% with a new 30-year term, the payment could decline.
However, refinancing is not automatic or guaranteed.
Several factors determine whether refinancing makes sense:
·Future mortgage rates
·Remaining loan balance
·Property value and equity
·Credit and income qualifications
·Closing costs and lender fees
·The new loan term
·How long you intend to own the property
A refinance can reduce the monthly payment while extending the repayment period, potentially increasing total interest over time.
You should also calculate the refinance break-even point.
For example, if refinancing costs $4,000 and produces $150 in monthly savings, the simple break-even period would be approximately 27 months.
That doesn't account for every financial factor, but it illustrates why refinancing should be evaluated strategically.
My recommendation is simple: Never buy a home today based on the assumption that you will definitely be able to refinance tomorrow.
5. 🤝 Seller Concessions May Be More Valuable Than Waiting
In some markets, buyers may have negotiating opportunities that become less available when demand increases.
These may include:
Seller-Paid Closing Costs
Depending on the mortgage program and applicable contribution limits, sellers may contribute toward eligible closing costs.
This can reduce the cash a buyer needs at closing.
Permanent Mortgage Rate Buydowns
An eligible seller or builder contribution may help pay discount points to obtain a lower interest rate.
Whether that investment is worthwhile depends on the upfront cost, monthly savings, and expected ownership period.
Temporary Rate Buydowns
Some loan programs permit temporary buydown structures, such as a 2-1 buydown.
With a 2-1 buydown, the borrower's effective payment rate is generally reduced by two percentage points in the first year and one percentage point in the second year before returning to the note rate.
Qualification is generally based on the full note rate, subject to program requirements.
A temporary buydown does not change the permanent note rate or guarantee a future refinance.
Builder Incentives
Some builders may offer eligible closing-cost assistance, financing incentives, or upgrades.
The key is to evaluate the total purchase price and financing terms rather than focusing exclusively on the advertised incentive.
6. 📊 Five Questions to Ask Before Deciding Whether to Wait
Before you postpone buying a home, ask yourself:
1. Can I comfortably afford the complete monthly payment today?
Consider principal, interest, property taxes, homeowners insurance, mortgage insurance, and HOA dues, where applicable.
2. How long do I plan to own the property?
Transaction costs and the expected holding period can significantly affect whether buying is financially attractive.
3. How much cash will I have left after closing?
Avoid exhausting emergency savings simply to become a homeowner.
4. What is happening in my local housing market?
National mortgage headlines cannot tell you whether sellers in Katy, Fulshear, or Greater Houston are negotiating.
5. What happens if mortgage rates don't fall?
Your purchasing decision should still be financially sustainable if interest rates remain elevated for several years.
These questions help transform an emotional decision into a financial strategy.
7. 🩺 Different Buyers Need Different Mortgage Strategies
There is no one-size-fits-all answer.
First-Time Homebuyers: Down payment assistance, FHA, conventional low-down-payment programs, and seller concessions may affect affordability.
Veterans and Eligible Military Borrowers: VA financing may offer zero-down-payment options for qualified borrowers, subject to entitlement, lender requirements, and other eligibility considerations.
Doctors and Dentists: Certain physician mortgage programs may offer specialized qualification or down payment options, depending on the lender.
Move-Up Buyers: Existing home equity, sale contingencies, and the costs of carrying two homes can influence the timing decision.
Self-Employed Borrowers: Income documentation, tax returns, business cash flow, and alternative loan programs may be more important than attempting to predict mortgage rates.
At Medallion Funds, the objective is to evaluate available financing programs based on the borrower's qualifications and financial goals.
8. 🏡 Should You Buy a House Now or Wait?
Buying now may make sense when:
·You have stable income and sufficient reserves.
·You find a home that meets your needs.
·The full monthly payment fits your budget.
·You expect to remain in the property long enough to justify transaction costs.
·You can negotiate favorable purchase terms.
Waiting may be the smarter decision when:
·Your monthly payment would strain your finances.
·You need to improve your credit or reduce debt.
·Your employment or relocation plans are uncertain.
·You lack adequate emergency savings.
·You're considering a purchase primarily because of fear of missing out.
There's nothing wrong with waiting when it improves your financial position.
But waiting solely because you expect mortgage rates to fall can introduce its own risks.
9. 📍 Buying a Home in Katy, Fulshear, or Greater Houston?
The Houston-area housing market includes established neighborhoods, new construction communities, and rapidly developing suburban areas.
Property taxes, insurance costs, HOA assessments, builder incentives, and local inventory can materially change the affordability calculation.
That's why a mortgage analysis should evaluate more than just the interest rate.
When I work with homebuyers, I want them to understand the full cost of ownership and the financing options available to them.
A well-structured mortgage should support your financial goals—not create unnecessary financial pressure.
Final Thoughts: Don't Try to Time the Perfect Mortgage Rate
The best time to buy a home isn't necessarily when mortgage rates reach their lowest point.
It's when the property, financing, affordability, and your personal circumstances align.
Rates may fall. Rates may rise. Home prices may change.
You cannot control the market.
But you can control how carefully you prepare, compare financing options, and evaluate the financial commitment.
Don't make your homebuying decision based on a prediction. Make it based on a plan.
📞 Let's Evaluate Your Homebuying Options
I'm Bill Rapp, CCIM, Director of Capital Advisory with Medallion Funds.
Whether you're buying your first home, moving up, purchasing new construction, or exploring specialized financing, I'd welcome the opportunity to help you understand your mortgage options.
Bill Rapp
Partner & Director of Capital Advisory | Medallion Funds
Commercial Lending Nationwide
Residential Lending in AL, CA, CO, NV & TXBottom of Form
https://www.billrapponline.com/
https://findamortgagebroker.com/Profile/WilliamRappJr28883
https://billrapp.commloan.com/
https://billrapponline.com/financingfuturescre-houston-katy
https://houstoncommercialmortgage.com/
https://author.billrapponline.com
https://doctorvideo.billrapponline.com/
https://veteransvideo.billrapponline.com/
https://mortgageviking.billrapponline.com/
https://fha203h.billrapponline.com/
https://renovationvideo.billrapponline.com
https://medallionfunds.com/bill-rapp/
https://www.amazon.com/dp/B0F32Z5BH2
https://veed.cello.so/FOmzTty6oi9
https://buymeacoffee.com/vikingente3
https://creplaybookseries.billrapponline.com
https://creplaybook.billrapponline.com/
© Bill Rapp, Medallion Funds LLC, Director of Capital Advisory
Main Office:
Medallion Funds
[email protected]
11920 Southern Highlands PKWY Suite 302Las Vegas, NV 89141
Texas Complaint and Recovery Fund Notice
All Rights Reserved Copyright © 2021 - Bill Rapp The Mortgage Viking | NMLS #228246