ATTENTION: For Those who are serious about Getting Pre-Qualified FAST!
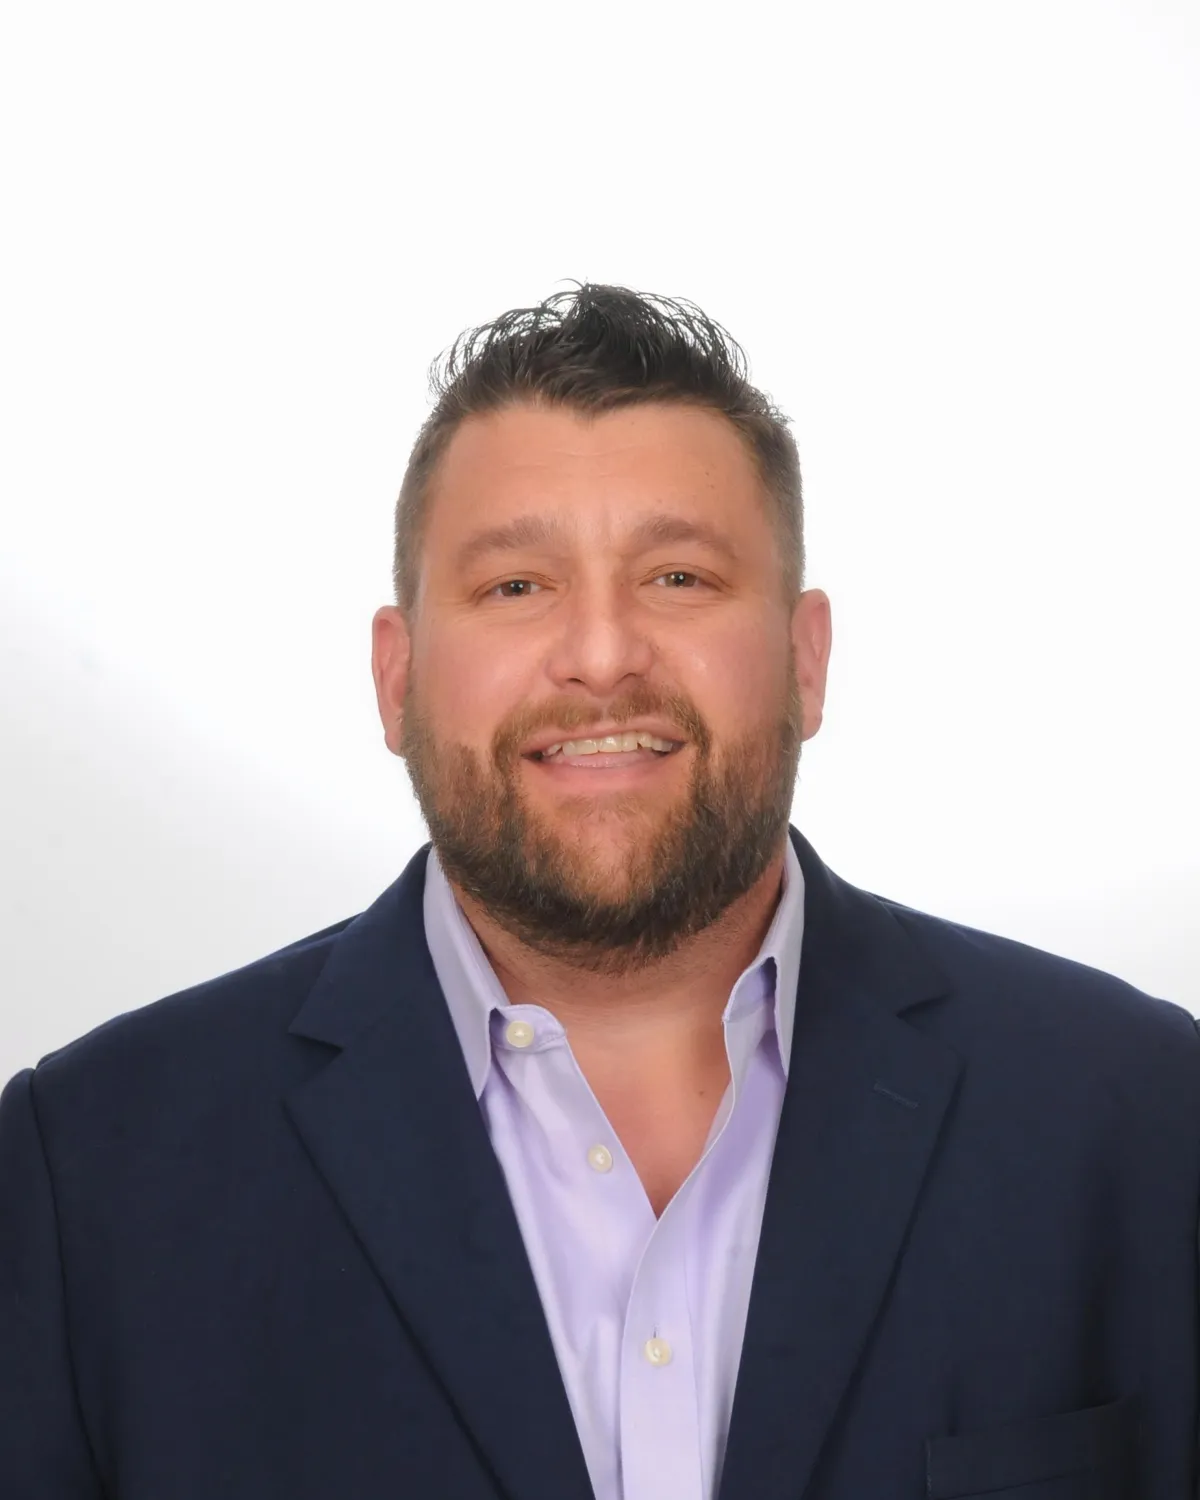
Bill Rapp, Mortgage Originator: NMLS 228246
"Brokers Are Better.
Better Pricing, Better Service!"
Subscribe To My List Below To Get Your Mortgage Quote Now!
Simply enter your name and email below:
WITH PROVEN STRATEGIES & PROVEN RESULTS
HERE'S WHAT MY CLIENTS SAY:
What People Are Saying:
Excellent Service
Bill is an exceptional loan officer. He helped us to purchase our home with very personal and professional service. He helped us navigate the whole process from start to closing without any problems. We didn't think we're qualified to purchase a house, but Bill went above and beyond to find a way to help us achieve our goal. He always responded very quickly with our requests, he would come back with different options with comparison chart to clearly indicate how much we need for down payment, monthly payments, interest rates, closing costs etc.
We would highly recommend Bill to anyone in need of lending services. In fact, we have already recommended Bill to one of our friends on purchasing a house.
--- David Chan - Houston, TX
Bank Statement Lending!
William Rapp of Network Funding, L. P. was very professional and I felt comfortable in dealing with him. I will definitely recommend him to family and friends.
--- Ian F - Missouri City, TX
Professionalism - Expert In Home Style Loan
Bill is an expert in the topic, his explanations and online material make a difference and he is always there from the beginning to the end. He is committed to make thing happen.
--- Felipe Caldern & Carolina Angel Gutierrez
Great Service!
Bill Rapp's handling of our loan (even though out of state) was unparalleled to any service I have been through prior, including 3 different real estate transactions and multiple refinances. Extremely quick close, with great options and flexibility for my families needs. All around A+
--- Chris & Beth Sheehan - San Jose, CA
Knowledgeable and Responsive!
Bill was a pleasure to work with and he made the loan process fairly easy. He answered all questions I had very quickly and was straight forward in doing it. I would recommend Bill to others.
--- Wes Brady - Richmond, TX
Very professional and always returned our calls!
Bill takes a lot of pride in his job and is very dependable. They were very patient and understanding. He went out of his way and explained all my questions and concerns. They were very professional and returned my phone calls and emails. He did a great job and I fully recommend him.
--- Therese, Malcom & Shirley Teixeira - Katy, TX
Great Job!
Bill helped us out from beginning to end of loan process. The loan closed in a timely manner as Bill worked hard with bank to get our to the final steps.
--- Kamal & Theresa Wilson - Hartford, CT
Avid Problem-Solver and Absolute Pleasure to Work With!
Bill Rapp worked very hard to ensure that we closed our loan and were able to move into our new home. He always had alternatives to any problems we encountered while closing. He worked with us from the beginning identifying solutions to any problems that we were having. He was an absolute pleasure to work with!
--- Nikita Rayani & Sanit Tejani - Houston, TX
Awesome to work with!
Being a first-time buyer I came in with lots of questions and concerns. Bill was always available for any questions I had and answered everything to my satisfaction. Bill made the loan process so painless that I could still concentrate on other things. We ended up closing early which made things even better. If you are in need of a lender and want someone who is very approachable and stays on top of your loan then Bill is your guy.
--- Cesar Raya - Richmond, TX
Loan Declined by my bank, and he saved the day!
Bill, did an amazing job helping me close on my house. He took the reigns and reassured me the best route to take to help close. He was accountable, thorough and trustworthy. I will continue to work with Network Funding, L.P. when it comes to home buying in the future because of the quality of service Bill gave.
--- Jacob Smith - Boerne, TX
Bill Rapp Will Definitely Make It Happen!
Bill is the most kind, patient and helpful person I have ever known. He answers his phone calls and emails promptly. You can ask him a million questions, and he will answer each and every one of them. Before I started working with Bill, I had been turned down for a home loan, because of some past credit issues I had, plus I was a single mother. However, once I started working with Bill, he was able to quickly get me a home loan, with a good interest rate. I would recommend that you call him, as he will help you.
--- Corinne Wilson - Roselle, NJ
Knowledgeable, Honest, Trustworthy, and Reliable!
"I will definitely keep you in mind. If anyone I know needs financing, I will send them your way!"
--- Jon & Andrea Saleem, CRPC Financial Advisor - Houston, TX
Best Dam Mortgage Guy a man could know!
"Hands down the best loan experience to date!"
--- Gabe & Chelsea Jackson - Pearland, TX
Phenomenal, Hard Working and Never Quits!
Had a stupid foreclosure that could have been avoided if ex’s attny would have sent my buy out offer. So Bill was able to push this through with a 4 year foreclosure. He worked his butt off, was very diligent with his communication; and was very professional talking to me even when I was screaming and/or crying at him. Highly recommend this lender. He really go to the ends of the earth to help you!
--- Liz Keeter - Harlingen, TX
Exceptional customer service!
Bill is the most kind, patient and helpful person I have ever known. He answers his phone calls and emails promptly. You can ask him a million questions, and he will answer each and every one of them. Before I started working with Bill, I had been turned down for a home loan, because of some past credit issues I had, plus I was a single mother. However, once I started working with Bill, he was able to quickly get me a home loan, with a good interest rate. I would recommend that you call him, as he will help you.
--- Isha Lopez & Mauricio Garcia - Houston, TX
Service with a capitol S
Bill went above and beyond at every turn. He worked late on Saturday, he worked late all the time. We wanted to close ASAP and he really helped make it happen for us.
--- Jeff & Wendy Heger - Houston, TX
Best Buying Experience!
I would would highly recommend going with Network Funding LP. As a first time home buyer I didn't know what to expect. Bill Rapp was very helpful in answering all my questions and guided me through all ghe steps. I couldn't have asked for a better buying experience!
--- Tabitha Turner - Humble, TX
Would recommend him and use him again!
Very involved and professional . Kept me informed and up to date on everything that was going on Went with me closing and was very helpful and knowledgeable.
--- Kathy Ward - Houston, TX
Great experience!
Well I meet bill back in December 2016 he got recommended by my real estate agent we had a house in sight and started the process to get approved but we fail due to my work history and credit bill told me not to give up and put me in contact with a credit repair company they help me bring my score up and bill walk me thru the process of getting a new line so this time around we got approved before looking for our house after we found it we still had a couple of hick up but with bills help on Sunday 6-18-17 to be exact Father's Day bill called me to give me the great news that we had got approved and the closing date was as scheduled bill was more than just a lender to my family he became a friend and I'm alway going to have him in mind for any other financial situation.
--- Alejandres Felimon - Richmond, TX
I really liked his attitude!
I wouldn't usually say this but the way he had handled my mortgage was really pleasant. I personally enjoyed the time spent with him while we discussed feasible rates. He's a great man with a great personality and he offered really low interests as well. Definitely recommend him to others.
--- Tom Troiano - Atlantic City, NJ
He's nothing short of a miracle!
I'm a self-employed businessman and had him figure out the mortgage of the house after 30% down payment. The interest rates I received were incredibly low given what I had thought of earlier. One other important thing to note was that I hadn't really taken any loans earlier, so I had no credit history. He helped me out with all that as well so I can't really call him anything else but a miracle.
--- Fran Suarez - Cleveland, OH
He's really helpful!
I made a bid to him and the very same day he gave me an offer which I couldn't resist. It was too intimidating with those incredibly low interest rates and all, thoroughly recommend him.
--- Kenny Mickle - Houston, TX
Expeditious!
Bill was very expeditious and made it real easy going through the loan process. I felt he was on top of things.
I deal with investment properties and will more than likely call on him again.
--- Wayne King - Pensacola, FL
Bill was great!
Bill made us feel like a friend all the way thru the process. He was patient and explained everything he needed clearly. He was available ANYTIME we had questions or needed more information. Hopefully we won’t go thru this process again anytime soon, but if we do - we’d choose Bill! =)
--- Barbra & Nick Grimmer - Austin, TX
Great broker!
Bill was a great broker to work with. As first time home buyers we had many questions about the process, Bill took the time to help us even calling us back on weekends with answers. I would not hesitate to recommend him to anyone looking for a broker to work with.
--- Murray & Lisa Turner - Pensacola, FL
Outstanding service!
I couldn't have been more pleased with Bill's level of service. He made what is typically a lengthy, arduous process far quicker and easier at every turn. I'm extremely comfortable recommending Bill to friends and family, and will definitely utilize his services again!
--- Jim Lipari - Austin, TX
Step-by-Step Guide to the VA Loan Process
6 Easy Steps to a VA Loan
For many borrowers, applying for any kind of mortgage may seem daunting.
But, when broken down, this rundown of 6 steps to getting a VA loan is easy to understand.
1. Select a VA-approved Lender
On the surface, it might appear that any lender will do. However, if you dig a little deeper, you may discover that not all lenders are the same. First, only lenders approved by the U.S. Department of Veterans Affairs can originate VA mortgages. Secondly, some lenders focus primarily on conventional loans, while others concentrate almost exclusively on the VA loan program for military clients. Using a VA specialty lender with extensive knowledge about the VA loan process vs. a lender who only funds a few VA mortgages a year may translate into an easier and quicker loan process. To connect with a VA specialty lender, please click here.
2. Obtain a Certificate of Eligibility (COE)
An experienced lender can help you obtain what’s called a Certificate of Eligibility (COE). The COE will prove that you meet initial eligibility standards for VA loan benefits. It will also let the lender know how much entitlement you can receive, which is the amount the Department of Veterans Affairs will guarantee on your VA loan. To get your COE, you’ll need to give your lender a bit of information about your military service. Usually, a COE can be acquired online instantly through a lender’s portal or through the eBenefits portal on the va.gov website. Those servicemembers or surviving spouses whose COEs cannot be obtained online will have to get theirs by mail. A VA lender or the VA can help direct you to the right resource for your specific situation.
3. Pre-Qualify for Your Loan Amount
Pre-qualifying is important, but not required. By choosing to complete this step you can save some time and potential surprises later in the process. To pre-qualify for your loan amount, you’ll have a candid conversation with your VA loan professional about your income, credit history, employment, marital status and other factors. Giving your lender complete details during the pre-qualifying step can help prevent surprises later during underwriting. The pre-qualifying step can also reveal areas that need improvement before you can be approved, such as credit or debt-to-income ratio. While a prequalification letter gives you a ballpark price range for house hunting, it does not guarantee that you will be approved for a loan, and your lender will later have to verify the information you provide. To get a loan requires later final approval by underwriting once all documents have been received and reviewed (see Step 5).
4. Go House Hunting & Find Home
The fourth step is usually one borrowers enjoy because they get to look at homes they might consider buying. Working with a real estate professional who specializes in the VA process can help you get the most out of your benefits. This is true because the VA allows certain fees and costs to be paid by the seller (if both you and the seller agree), and a knowledgeable agent will know this and help you negotiate seller-paid fees. Once you’ve got a signed purchase agreement, you can move forward in the VA loan process.
5. Lender Processes Application
& Orders VA Appraisal
A signed purchase contract is the document you’ll need to finish your initial application. Once your lender has the contract, they will order the VA appraisal. Here again, not just any appraiser will do. Only a professional who is certified to perform appraisals to VA standards can evaluate the home being considered for VA financing. The VA appraiser will make sure the price you’ve agreed to pay for the home corresponds with the current value. Another very important part of the VA appraisal is to inspect the home to make sure it meets the VA minimum property requirements (VA MPRs). However, the VA appraisal does not take the place of a home inspection, which focuses on code violations, defects and the condition of the property. While many borrowers have heard horror stories about the length of the VA appraisal process, the Department of Veterans Affairs gives the appraisers 10 days from order to completion barring extenuating circumstances. While you’re waiting for appraisal documents, you’ll be busy submitting documents of your own to your VA-approved lender to show you have the ability to qualify for the loan. If the home passes appraisal for value and VA minimum property requirements, and it’s verified by the lender that you qualify for your loan, the underwriter will give his or her stamp of approval.
6. Close on Your Loan and Move In
After being approved by the underwriter, all that is left to do is close and move in. During closing, the property legally transfers from the former owner to you. Closing is a step that requires you to sign documents that confirm you understand and agree to the terms of the loan. You will need to provide proof of homeowners insurance and, if required, pay closing costs. Once you’ve signed all your closing documents, you’ll get the keys to your new home.
While these steps may not happen in the order above or be a required part (such as prequalification)*, they represent the typical process for the applicant in obtaining a VA purchase loan. Your lender may need to take other steps. For more information about VA loans, contact an experienced VA-approved lender.
My best advice to you is to call Bill Rapp, the Mortgage Viking, today to discuss your options 281-222-0433.
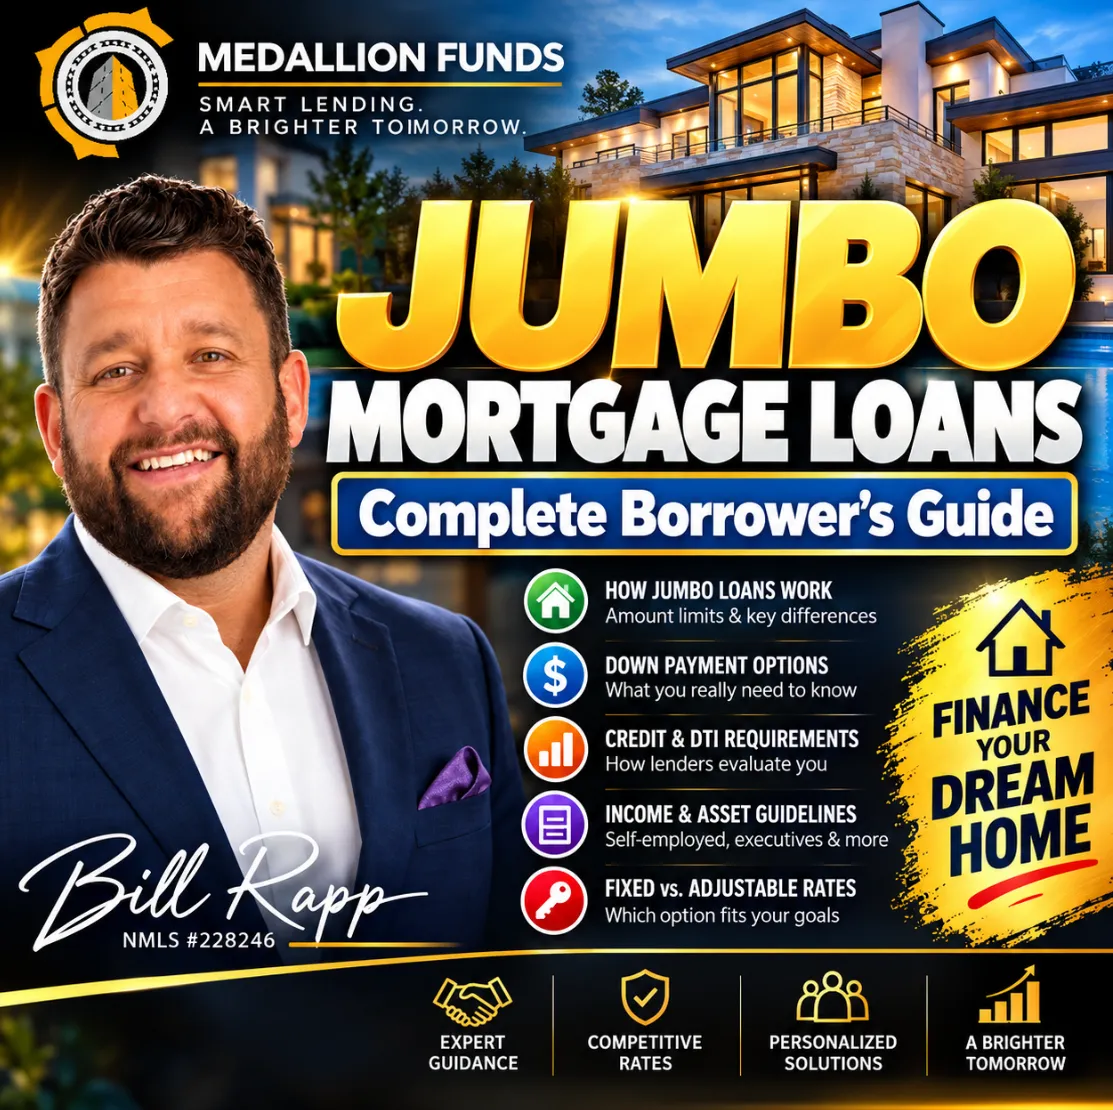
🏡 Jumbo Mortgage Loans: The Complete Borrower’s Guide to Financing a High-Value Home 💰
🏡 Jumbo Mortgage Loans: The Complete Borrower’s Guide to Financing a High-Value Home 💰
🔑 Jumbo Loans Explained: How to Qualify, Compare Options & Finance Your Dream Home 🏠
________________________________________________________________________________
Jumbo Mortgage Loans: Complete Borrower’s Guide
When the price of your dream home exceeds conventional conforming loan limits, a jumbo mortgage loan may provide the financing needed to complete the purchase.
Jumbo loans are designed for borrowers who need larger mortgage amounts than those permitted under conforming loan programs. They are commonly associated with luxury homes and expensive housing markets, but they can also be relevant for professionals, executives, business owners, investors purchasing a primary residence, and other borrowers buying higher-value properties.
Because jumbo mortgages represent larger credit exposures for lenders, qualifying can be different from obtaining a conventional conforming mortgage.
Understanding those differences before shopping for a home can make the financing process considerably easier.
What Is a Jumbo Mortgage Loan?
A jumbo mortgage is a home loan with an amount exceeding the applicable conforming loan limit for the property.
Conforming loans generally follow guidelines established for mortgages eligible for purchase by Fannie Mae or Freddie Mac. A mortgage above the applicable conforming limit is typically considered a non-conforming—or jumbo—loan.
Importantly, the applicable threshold can depend on the property location, number of units, and current year's loan limits.
Instead of assuming that a particular purchase price automatically requires jumbo financing, have your mortgage professional calculate the required loan amount and determine which financing category applies.
How Do Jumbo Loans Work?
The basic structure resembles other mortgages. You purchase or refinance a property, contribute the required equity or down payment, and finance the remainder with a mortgage.
The major difference is underwriting.
Because a jumbo lender may be taking on a substantially larger loan balance, underwriting standards can place additional emphasis on:
·Credit history and credit scores
·Debt-to-income ratio
·Income stability
·Employment or business income
·Liquid assets
·Post-closing reserves
·Down payment and loan-to-value ratio
·Property value and marketability
·Overall borrower financial strength
Jumbo underwriting is not necessarily about checking one additional box. Lenders frequently evaluate the borrower's entire financial profile.
How Much Down Payment Do You Need for a Jumbo Loan?
One of the biggest misconceptions about jumbo mortgages is that every borrower needs an enormous down payment.
There is no universal down-payment requirement for all jumbo loans.
Available loan-to-value ratios depend on factors including the lender, loan amount, occupancy, property type, credit profile and overall financial strength of the borrower.
Some borrowers may qualify for relatively high-LTV jumbo programs, while larger loan balances or more complex scenarios may require additional equity.
This is one reason working with a mortgage broker for jumbo loans can be valuable. Instead of evaluating a single institution's lending guidelines, a broker can explore available programs and determine which structures align with the transaction.
What Credit Score Do You Need for a Jumbo Mortgage?
Jumbo lenders typically place significant emphasis on credit quality, although there is no single credit-score requirement applicable to every program.
The larger the mortgage exposure, the more closely the lender may examine the borrower's overall credit history.
Beyond the score itself, underwriting may review:
·Payment history
·Mortgage history
·Revolving credit utilization
·Installment debt
·Recent credit inquiries
·Derogatory credit events
·Overall debt obligations
A strong score can help, but jumbo qualification usually involves more than the number shown on a credit report.
Debt-to-Income Ratio and Jumbo Loans
Your debt-to-income ratio (DTI) compares qualifying monthly debt obligations with qualifying monthly income.
For example, if a borrower has $15,000 in qualifying monthly income and $5,250 in applicable monthly obligations, the resulting DTI is 35%.
However, jumbo underwriting can become more nuanced for borrowers with bonuses, commissions, restricted stock, partnership income, business income, investment income, rental properties or other nontraditional compensation.
A borrower with substantial income and assets can still encounter underwriting challenges if the income cannot be documented according to a particular lender's guidelines.
This makes early financial review particularly important.
Why Cash Reserves Matter
A lender may want to know not only whether you can make the down payment and pay closing costs, but also how much liquidity remains after closing.
These funds are generally referred to as reserves.
Depending on the loan program, lenders may want borrowers to demonstrate sufficient assets to cover a specified number of months of mortgage-related obligations after closing.
Reserve requirements can become especially important for larger loan amounts, multiple financed properties, or more complex financial profiles.
That means your real cash requirement isn't necessarily just:
Down payment + closing costs.
You should also consider:
Down payment + closing costs + required reserves + remaining personal liquidity.
A well-structured mortgage shouldn't unnecessarily leave a borrower cash-poor immediately after purchasing the property.
Jumbo Loans for Self-Employed Borrowers
Business owners and self-employed professionals can qualify for jumbo mortgages, but income documentation is often one of the most important parts of the transaction.
Traditional underwriting may evaluate personal and business tax returns, K-1s, business financial statements and other documentation.
Depending on the available programs and borrower circumstances, alternative-documentation mortgage options may also exist.
The key is addressing income qualification before entering a purchase contract whenever possible.
If you're self-employed, don't wait until underwriting to discover how the lender will calculate your qualifying income.
Jumbo Mortgages for Doctors and Dentists
Physicians, dentists and other qualifying professionals can present unusual mortgage profiles.
A doctor might have excellent future earning potential while simultaneously carrying significant student debt or having relatively limited accumulated assets early in a career.
Certain professional mortgage programs may address some of these circumstances differently than standard jumbo financing.
Rather than automatically choosing a traditional jumbo mortgage, qualified medical professionals should compare available doctor mortgage and jumbo loan options based on their specific financial situation.
Jumbo Fixed-Rate vs. Adjustable-Rate Mortgages
Jumbo mortgages can potentially be structured as either fixed-rate or adjustable-rate loans, depending on available programs.
A fixed-rate mortgage provides a consistent interest rate for the life of the loan.
An adjustable-rate mortgage (ARM) generally offers an initial rate structure for a defined period before becoming subject to adjustment according to the loan's terms.
Neither structure is automatically right for every borrower.
The appropriate comparison should consider factors such as:
·How long you expect to own the property
·How long you expect to keep the mortgage
·Expected future income
·Liquidity
·Risk tolerance
·Potential refinancing plans
·Differences in current pricing
The lowest introductory rate shouldn't be evaluated in isolation from the rest of the loan structure.
Don't Shop for a Jumbo Mortgage by Interest Rate Alone
Rate matters—but it isn't the entire mortgage.
Two jumbo loans advertising similar rates could have very different economics.
Compare:
Interest rate: What rate applies to the loan?
APR: What does the annual percentage rate indicate about financing costs?
Points: Are you paying additional money upfront to obtain the quoted rate?
Lender fees: What origination or underwriting charges apply?
Loan structure: Is the loan fixed or adjustable?
Prepayment terms: Are there restrictions or costs relevant to your situation?
Cash-to-close: How much liquidity does the transaction consume?
Reserve requirements: How much money must remain after closing?
A mortgage should be evaluated as a complete financial structure rather than a single advertised rate.
Why Jumbo Borrowers Should Get Pre-Approved Early
Pre-approval is particularly important when purchasing a high-value property.
Before making an offer, you ideally want to understand:
1.Your realistic financing range.
2.Your estimated down payment.
3.Expected reserve requirements.
4.How your income will be calculated.
5.Potential documentation issues.
6.Which jumbo programs may fit your circumstances.
Early preparation can reduce surprises once you are under contract.
For self-employed borrowers, executives, physicians, real estate investors and borrowers with complex financial statements, early underwriting review can be especially valuable.
Documents to Prepare for Jumbo Mortgage Pre-Approval
Although requirements vary, borrowers should be prepared to provide documentation supporting income, employment, assets and credit.
Depending on the scenario, this could include recent pay statements, W-2s, tax returns, bank and investment statements, identification, mortgage statements, business documentation and information about other real estate owned.
If your finances are complicated, disclose that complexity upfront.
The objective isn't simply to get a quick pre-approval. It is to build a financing strategy that has been properly evaluated before you commit to a major real estate purchase.
How a Mortgage Broker Can Help With Jumbo Financing
Jumbo mortgage programs can vary significantly among lenders.
One institution might have a strong program for a straightforward W-2 borrower, while another could be more appropriate for a physician, business owner, investor or borrower with substantial assets but complicated taxable income.
At Medallion Funds, our objective is to evaluate the complete financing scenario—not simply quote a rate.
We can help borrowers explore mortgage structures based on factors including loan amount, property type, down payment, credit, income, liquidity and long-term objectives.
Final Thoughts: Build the Jumbo Mortgage Around Your Financial Strategy
A jumbo mortgage is a significant financial obligation. The objective should not be merely to obtain the largest loan available.
The better question is:
What mortgage structure best supports the home purchase while protecting your broader financial position?
Consider your rate, monthly payment, cash-to-close, reserves, liquidity and future plans together.
If you're considering purchasing or refinancing a high-value home, speak with Bill Rapp and Medallion Funds about your jumbo mortgage options.
Bill Rapp
Partner & Director of Capital Advisory | Medallion Funds
Commercial Lending Nationwide
Residential Lending in AL, CA, CO, NV & TXBottom of Form
https://www.billrapponline.com/
https://findamortgagebroker.com/Profile/WilliamRappJr28883
https://billrapp.commloan.com/
https://billrapponline.com/financingfuturescre-houston-katy
https://houstoncommercialmortgage.com/
https://author.billrapponline.com
https://doctorvideo.billrapponline.com/
https://veteransvideo.billrapponline.com/
https://mortgageviking.billrapponline.com/
https://fha203h.billrapponline.com/
https://renovationvideo.billrapponline.com
https://medallionfunds.com/bill-rapp/
https://www.amazon.com/dp/B0F32Z5BH2
https://veed.cello.so/FOmzTty6oi9
https://buymeacoffee.com/vikingente3
https://creplaybookseries.billrapponline.com
https://creplaybook.billrapponline.com/
© Bill Rapp, Medallion Funds LLC, Director of Capital Advisory
Main Office:
Medallion Funds
[email protected]
11920 Southern Highlands PKWY Suite 302Las Vegas, NV 89141
Texas Complaint and Recovery Fund Notice
All Rights Reserved Copyright © 2021 - Bill Rapp The Mortgage Viking | NMLS #228246