ATTENTION: For Those who are serious about Getting Pre-Qualified FAST!
Bill Rapp, Mortgage Originator: NMLS 228246
"Brokers Are Better.
Better Pricing, Better Service!"
Subscribe To My List Below To Get Your Mortgage Quote Now!
Simply enter your name and email below:
WITH PROVEN STRATEGIES & PROVEN RESULTS
HERE'S WHAT MY CLIENTS SAY:
What People Are Saying:
Excellent Service
Bill is an exceptional loan officer. He helped us to purchase our home with very personal and professional service. He helped us navigate the whole process from start to closing without any problems. We didn't think we're qualified to purchase a house, but Bill went above and beyond to find a way to help us achieve our goal. He always responded very quickly with our requests, he would come back with different options with comparison chart to clearly indicate how much we need for down payment, monthly payments, interest rates, closing costs etc.
We would highly recommend Bill to anyone in need of lending services. In fact, we have already recommended Bill to one of our friends on purchasing a house.
--- David Chan - Houston, TX
Bank Statement Lending!
William Rapp of Network Funding, L. P. was very professional and I felt comfortable in dealing with him. I will definitely recommend him to family and friends.
--- Ian F - Missouri City, TX
Professionalism - Expert In Home Style Loan
Bill is an expert in the topic, his explanations and online material make a difference and he is always there from the beginning to the end. He is committed to make thing happen.
--- Felipe Caldern & Carolina Angel Gutierrez
Great Service!
Bill Rapp's handling of our loan (even though out of state) was unparalleled to any service I have been through prior, including 3 different real estate transactions and multiple refinances. Extremely quick close, with great options and flexibility for my families needs. All around A+
--- Chris & Beth Sheehan - San Jose, CA
Knowledgeable and Responsive!
Bill was a pleasure to work with and he made the loan process fairly easy. He answered all questions I had very quickly and was straight forward in doing it. I would recommend Bill to others.
--- Wes Brady - Richmond, TX
Very professional and always returned our calls!
Bill takes a lot of pride in his job and is very dependable. They were very patient and understanding. He went out of his way and explained all my questions and concerns. They were very professional and returned my phone calls and emails. He did a great job and I fully recommend him.
--- Therese, Malcom & Shirley Teixeira - Katy, TX
Great Job!
Bill helped us out from beginning to end of loan process. The loan closed in a timely manner as Bill worked hard with bank to get our to the final steps.
--- Kamal & Theresa Wilson - Hartford, CT
Avid Problem-Solver and Absolute Pleasure to Work With!
Bill Rapp worked very hard to ensure that we closed our loan and were able to move into our new home. He always had alternatives to any problems we encountered while closing. He worked with us from the beginning identifying solutions to any problems that we were having. He was an absolute pleasure to work with!
--- Nikita Rayani & Sanit Tejani - Houston, TX
Awesome to work with!
Being a first-time buyer I came in with lots of questions and concerns. Bill was always available for any questions I had and answered everything to my satisfaction. Bill made the loan process so painless that I could still concentrate on other things. We ended up closing early which made things even better. If you are in need of a lender and want someone who is very approachable and stays on top of your loan then Bill is your guy.
--- Cesar Raya - Richmond, TX
Loan Declined by my bank, and he saved the day!
Bill, did an amazing job helping me close on my house. He took the reigns and reassured me the best route to take to help close. He was accountable, thorough and trustworthy. I will continue to work with Network Funding, L.P. when it comes to home buying in the future because of the quality of service Bill gave.
--- Jacob Smith - Boerne, TX
Bill Rapp Will Definitely Make It Happen!
Bill is the most kind, patient and helpful person I have ever known. He answers his phone calls and emails promptly. You can ask him a million questions, and he will answer each and every one of them. Before I started working with Bill, I had been turned down for a home loan, because of some past credit issues I had, plus I was a single mother. However, once I started working with Bill, he was able to quickly get me a home loan, with a good interest rate. I would recommend that you call him, as he will help you.
--- Corinne Wilson - Roselle, NJ
Knowledgeable, Honest, Trustworthy, and Reliable!
"I will definitely keep you in mind. If anyone I know needs financing, I will send them your way!"
--- Jon & Andrea Saleem, CRPC Financial Advisor - Houston, TX
Best Dam Mortgage Guy a man could know!
"Hands down the best loan experience to date!"
--- Gabe & Chelsea Jackson - Pearland, TX
Phenomenal, Hard Working and Never Quits!
Had a stupid foreclosure that could have been avoided if ex’s attny would have sent my buy out offer. So Bill was able to push this through with a 4 year foreclosure. He worked his butt off, was very diligent with his communication; and was very professional talking to me even when I was screaming and/or crying at him. Highly recommend this lender. He really go to the ends of the earth to help you!
--- Liz Keeter - Harlingen, TX
Exceptional customer service!
Bill is the most kind, patient and helpful person I have ever known. He answers his phone calls and emails promptly. You can ask him a million questions, and he will answer each and every one of them. Before I started working with Bill, I had been turned down for a home loan, because of some past credit issues I had, plus I was a single mother. However, once I started working with Bill, he was able to quickly get me a home loan, with a good interest rate. I would recommend that you call him, as he will help you.
--- Isha Lopez & Mauricio Garcia - Houston, TX
Service with a capitol S
Bill went above and beyond at every turn. He worked late on Saturday, he worked late all the time. We wanted to close ASAP and he really helped make it happen for us.
--- Jeff & Wendy Heger - Houston, TX
Best Buying Experience!
I would would highly recommend going with Network Funding LP. As a first time home buyer I didn't know what to expect. Bill Rapp was very helpful in answering all my questions and guided me through all ghe steps. I couldn't have asked for a better buying experience!
--- Tabitha Turner - Humble, TX
Would recommend him and use him again!
Very involved and professional . Kept me informed and up to date on everything that was going on Went with me closing and was very helpful and knowledgeable.
--- Kathy Ward - Houston, TX
Great experience!
Well I meet bill back in December 2016 he got recommended by my real estate agent we had a house in sight and started the process to get approved but we fail due to my work history and credit bill told me not to give up and put me in contact with a credit repair company they help me bring my score up and bill walk me thru the process of getting a new line so this time around we got approved before looking for our house after we found it we still had a couple of hick up but with bills help on Sunday 6-18-17 to be exact Father's Day bill called me to give me the great news that we had got approved and the closing date was as scheduled bill was more than just a lender to my family he became a friend and I'm alway going to have him in mind for any other financial situation.
--- Alejandres Felimon - Richmond, TX
I really liked his attitude!
I wouldn't usually say this but the way he had handled my mortgage was really pleasant. I personally enjoyed the time spent with him while we discussed feasible rates. He's a great man with a great personality and he offered really low interests as well. Definitely recommend him to others.
--- Tom Troiano - Atlantic City, NJ
He's nothing short of a miracle!
I'm a self-employed businessman and had him figure out the mortgage of the house after 30% down payment. The interest rates I received were incredibly low given what I had thought of earlier. One other important thing to note was that I hadn't really taken any loans earlier, so I had no credit history. He helped me out with all that as well so I can't really call him anything else but a miracle.
--- Fran Suarez - Cleveland, OH
He's really helpful!
I made a bid to him and the very same day he gave me an offer which I couldn't resist. It was too intimidating with those incredibly low interest rates and all, thoroughly recommend him.
--- Kenny Mickle - Houston, TX
Expeditious!
Bill was very expeditious and made it real easy going through the loan process. I felt he was on top of things.
I deal with investment properties and will more than likely call on him again.
--- Wayne King - Pensacola, FL
Bill was great!
Bill made us feel like a friend all the way thru the process. He was patient and explained everything he needed clearly. He was available ANYTIME we had questions or needed more information. Hopefully we won’t go thru this process again anytime soon, but if we do - we’d choose Bill! =)
--- Barbra & Nick Grimmer - Austin, TX
Great broker!
Bill was a great broker to work with. As first time home buyers we had many questions about the process, Bill took the time to help us even calling us back on weekends with answers. I would not hesitate to recommend him to anyone looking for a broker to work with.
--- Murray & Lisa Turner - Pensacola, FL
Outstanding service!
I couldn't have been more pleased with Bill's level of service. He made what is typically a lengthy, arduous process far quicker and easier at every turn. I'm extremely comfortable recommending Bill to friends and family, and will definitely utilize his services again!
--- Jim Lipari - Austin, TX
Step-by-Step Guide to the VA Loan Process
6 Easy Steps to a VA Loan
For many borrowers, applying for any kind of mortgage may seem daunting.
But, when broken down, this rundown of 6 steps to getting a VA loan is easy to understand.
1. Select a VA-approved Lender
On the surface, it might appear that any lender will do. However, if you dig a little deeper, you may discover that not all lenders are the same. First, only lenders approved by the U.S. Department of Veterans Affairs can originate VA mortgages. Secondly, some lenders focus primarily on conventional loans, while others concentrate almost exclusively on the VA loan program for military clients. Using a VA specialty lender with extensive knowledge about the VA loan process vs. a lender who only funds a few VA mortgages a year may translate into an easier and quicker loan process. To connect with a VA specialty lender, please click here.
2. Obtain a Certificate of Eligibility (COE)
An experienced lender can help you obtain what’s called a Certificate of Eligibility (COE). The COE will prove that you meet initial eligibility standards for VA loan benefits. It will also let the lender know how much entitlement you can receive, which is the amount the Department of Veterans Affairs will guarantee on your VA loan. To get your COE, you’ll need to give your lender a bit of information about your military service. Usually, a COE can be acquired online instantly through a lender’s portal or through the eBenefits portal on the va.gov website. Those servicemembers or surviving spouses whose COEs cannot be obtained online will have to get theirs by mail. A VA lender or the VA can help direct you to the right resource for your specific situation.
3. Pre-Qualify for Your Loan Amount
Pre-qualifying is important, but not required. By choosing to complete this step you can save some time and potential surprises later in the process. To pre-qualify for your loan amount, you’ll have a candid conversation with your VA loan professional about your income, credit history, employment, marital status and other factors. Giving your lender complete details during the pre-qualifying step can help prevent surprises later during underwriting. The pre-qualifying step can also reveal areas that need improvement before you can be approved, such as credit or debt-to-income ratio. While a prequalification letter gives you a ballpark price range for house hunting, it does not guarantee that you will be approved for a loan, and your lender will later have to verify the information you provide. To get a loan requires later final approval by underwriting once all documents have been received and reviewed (see Step 5).
4. Go House Hunting & Find Home
The fourth step is usually one borrowers enjoy because they get to look at homes they might consider buying. Working with a real estate professional who specializes in the VA process can help you get the most out of your benefits. This is true because the VA allows certain fees and costs to be paid by the seller (if both you and the seller agree), and a knowledgeable agent will know this and help you negotiate seller-paid fees. Once you’ve got a signed purchase agreement, you can move forward in the VA loan process.
5. Lender Processes Application
& Orders VA Appraisal
A signed purchase contract is the document you’ll need to finish your initial application. Once your lender has the contract, they will order the VA appraisal. Here again, not just any appraiser will do. Only a professional who is certified to perform appraisals to VA standards can evaluate the home being considered for VA financing. The VA appraiser will make sure the price you’ve agreed to pay for the home corresponds with the current value. Another very important part of the VA appraisal is to inspect the home to make sure it meets the VA minimum property requirements (VA MPRs). However, the VA appraisal does not take the place of a home inspection, which focuses on code violations, defects and the condition of the property. While many borrowers have heard horror stories about the length of the VA appraisal process, the Department of Veterans Affairs gives the appraisers 10 days from order to completion barring extenuating circumstances. While you’re waiting for appraisal documents, you’ll be busy submitting documents of your own to your VA-approved lender to show you have the ability to qualify for the loan. If the home passes appraisal for value and VA minimum property requirements, and it’s verified by the lender that you qualify for your loan, the underwriter will give his or her stamp of approval.
6. Close on Your Loan and Move In
After being approved by the underwriter, all that is left to do is close and move in. During closing, the property legally transfers from the former owner to you. Closing is a step that requires you to sign documents that confirm you understand and agree to the terms of the loan. You will need to provide proof of homeowners insurance and, if required, pay closing costs. Once you’ve signed all your closing documents, you’ll get the keys to your new home.
While these steps may not happen in the order above or be a required part (such as prequalification)*, they represent the typical process for the applicant in obtaining a VA purchase loan. Your lender may need to take other steps. For more information about VA loans, contact an experienced VA-approved lender.
My best advice to you is to call Bill Rapp, the Mortgage Viking, today to discuss your options 281-222-0433.
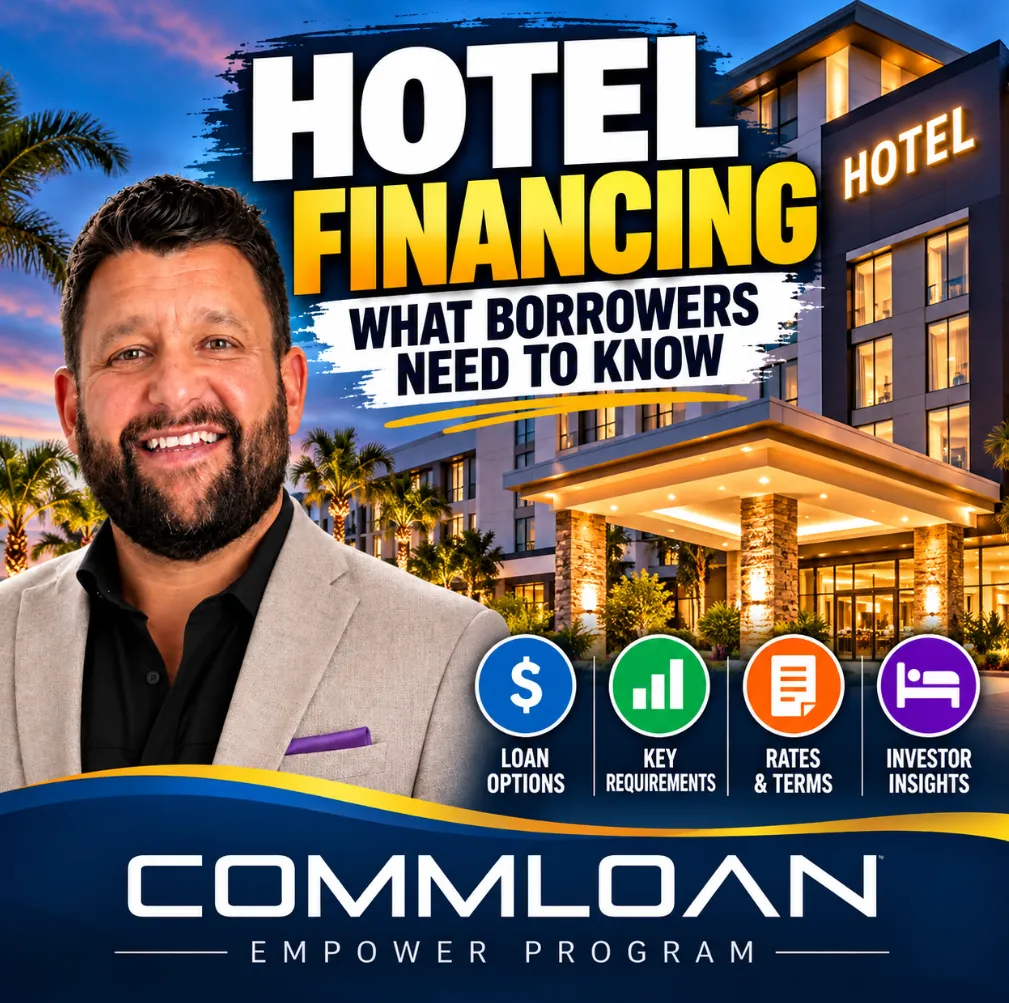
🏨 Hotel Financing Explained: What Every Borrower Needs to Know Before Applying for a Hotel Loan 💰
🏨 Hotel Financing Explained: What Every Borrower Needs to Know Before Applying for a Hotel Loan 💰
💵 Hotel Loans Made Simple: Financing Options, Down Payments & Lender Requirements 🏨
________________________________________________________________________________
Hotel Financing: What Borrowers Need to Know Before Applying for a Hotel Loan
Financing a hotel is different from financing a traditional commercial real estate investment. Hotels operate as both real estate assets and active businesses, making underwriting more complex than it is for many office, retail, industrial, or multifamily properties.
Whether you're purchasing an existing hotel, refinancing a hospitality property, renovating an underperforming asset, or developing a new hotel, understanding hotel financing requirements, loan structures, and lender expectations can help you secure the right capital.
At the CommLoan Empower Program, we help commercial real estate investors and business owners evaluate financing opportunities through a broad network of lenders.
Here's what borrowers need to know before pursuing hotel financing.
What Is Hotel Financing?
Hotel financing refers to commercial loans used to acquire, refinance, renovate, reposition, or construct hospitality properties.
Common property types include limited-service hotels, select-service hotels, full-service hotels, boutique hotels, extended-stay properties, and independent hotels.
Unlike conventional commercial real estate, hotel income depends on nightly room demand, occupancy, average daily room rates, operating efficiency, and competitive market conditions.
Because hospitality revenue can fluctuate significantly, lenders evaluate both the property's real estate value and its operational performance.
Types of Hotel Financing Available
1. Conventional Commercial Hotel Loans
Traditional banks and commercial lenders provide financing for established hotels with demonstrated operating histories.
These loans may offer competitive pricing to experienced operators with strong financial performance.
Typical considerations include:
·Historical operating income and cash flow
·Borrower liquidity and net worth
·Hotel franchise or brand affiliation
·Property condition and capital expenditure needs
·Market occupancy and demand trends
2. SBA Hotel Loans
Eligible owner-operated hotels may qualify for financing through SBA programs.
SBA 7(a) loans can support eligible acquisitions, refinancing, improvements, and certain business-related expenses, subject to program rules.
SBA 504 loans are generally designed for eligible long-term fixed-asset financing, including owner-occupied real estate and qualifying improvements.
Hotels must satisfy applicable SBA eligibility and occupancy requirements, including rules governing the operating business and property ownership structure.
SBA financing may be attractive to qualifying borrowers seeking lower down payments or longer amortization periods than certain conventional alternatives.
3. Hotel Bridge Loans
Bridge financing can be appropriate when a hotel requires significant renovation, operational improvement, or stabilization.
For example, an investor acquiring a hotel with below-market occupancy may use short-term financing while executing a property improvement plan.
Bridge loans typically involve higher financing costs and a defined exit strategy.
Borrowers should evaluate the projected refinance or sale carefully rather than assume stabilization will automatically produce permanent financing.
4. Hotel Construction Loans
Hotel construction financing supports ground-up development and, in some cases, major redevelopment.
Lenders may require:
·Detailed construction budgets and timelines
·Feasibility studies and market analysis
·Franchise agreements or brand commitments
·Developer and operator experience
·Equity contributions and contingency reserves
·A credible stabilization and permanent-financing strategy
Construction financing can involve staged advances and interest-only payments during development.
How Much Down Payment Do You Need for a Hotel Loan?
One of the most common questions borrowers ask is how much equity they need to purchase a hotel.
For preliminary planning, conventional hotel acquisitions may require approximately 25%–40% equity, although actual requirements vary substantially by lender, property, market, sponsor, and loan structure.
Certain eligible SBA transactions may require less, while bridge financing, construction, or distressed properties can require more.
For example, consider a $5 million hotel acquisition.
Equity contribution | Amount | Loan request |
25% | $1,250,000 | $3,750,000 |
30% | $1,500,000 | $3,500,000 |
35% | $1,750,000 | $3,250,000 |
These figures illustrate capital structures, not guaranteed lender approvals. Closing costs, reserves, renovations, and franchise-required improvements may increase the total equity needed.
Five Key Factors Hotel Lenders Evaluate
1. Debt Service Coverage Ratio (DSCR)
DSCR measures the property's ability to generate enough qualifying cash flow to cover debt service.
\[ DSCR=\frac{\text{Qualifying Cash Flow}}{\text{Annual Debt Service}} \]
For example, if a hotel's lender-adjusted cash flow is $650,000 and annual debt service is $500,000:
\[ DSCR=1.30x \]
That indicates $1.30 of qualifying cash flow for every $1.00 of debt service.
Lenders may require a DSCR around 1.25x–1.40x or higher, depending on the financing program and transaction. Some lenders also apply a debt-yield test.
2. Occupancy Rate
Occupancy measures the percentage of available room nights sold.
A hotel with 100 rooms selling an average of 70 rooms nightly has approximately 70% occupancy.
Lenders evaluate historical occupancy, seasonality, demand generators, and performance against competing hotels.
3. Average Daily Rate (ADR)
ADR represents average room revenue per occupied room.
Higher ADR can improve revenue, but only when supported by sustainable demand and occupancy.
4. Revenue Per Available Room (RevPAR)
RevPAR combines room pricing and occupancy into a single metric.
\[ RevPAR=ADR\times Occupancy \]
If ADR is $150 and occupancy is 70%, RevPAR equals $105.
RevPAR is particularly useful for evaluating a hotel's room-revenue productivity and comparing its performance with competitive properties.
5. Borrower Experience and Financial Strength
Hospitality lending is operationally intensive.
Lenders frequently examine the borrower's hotel management experience, liquidity, net worth, credit profile, operating partners, and ability to fund unexpected expenses.
An experienced management company may strengthen a financing proposal, although it does not necessarily replace sponsor requirements.
Why Hotel Cash Flow Matters More Than the Asking Price
A hotel may be worth $8 million based on a purchase contract or appraisal, but that does not automatically mean a lender will finance a particular percentage of that value.
Hotel loans are often constrained by several underwriting tests:
·Loan-to-value (LTV)
·Debt service coverage ratio (DSCR)
·Debt yield
·Borrower equity and liquidity
·Franchise and property improvement requirements
The lowest allowable loan amount resulting from these constraints may determine the maximum financing available.
The central question is not simply how much the hotel is worth. It's how much debt the hotel's sustainable cash flow can support.
Franchise Agreements and Property Improvement Plans
Many branded hotels operate under franchise agreements that impose operational and physical-property standards.
When a hotel changes ownership, the franchisor may require a Property Improvement Plan (PIP).
A PIP can involve guestroom renovations, furniture replacements, lobby upgrades, technology improvements, exterior improvements, and other brand-mandated work.
For borrowers, these obligations can materially change the total acquisition budget.
For example, a $6 million hotel purchase with a $1 million PIP may require significantly more capital than the purchase price alone suggests.
Lenders generally want to understand the PIP scope, costs, timing, available funding, and operational disruption before approving financing.
Documents Needed to Apply for a Hotel Loan
Preparing a complete financing package can help streamline lender review.
Typical documentation includes:
1.Current and historical operating statements, often three years when available.
2.Trailing 12-month financial statements.
3.Occupancy, ADR, and RevPAR reports.
4.STR or comparable competitive-set reports, when available.
5.Franchise agreement and applicable PIP.
6.Purchase contract or refinancing information.
7.Borrower financial statements and liquidity verification.
8.Business plan and management background.
9.Renovation or construction budgets, if applicable.
10.Property information, insurance, and existing debt details.
Additional tax returns, entity documents, and third-party reports may be requested.
Hotel Financing Mistakes to Avoid
Mistake #1: Shopping exclusively for the lowest interest rate. A lower rate may come with reduced proceeds, restrictive prepayment provisions, or an unfavorable maturity.
Mistake #2: Underestimating renovation expenses. Franchise PIPs and deferred maintenance can create significant capital requirements.
Mistake #3: Relying on projected occupancy without support. Lenders want credible assumptions grounded in actual market performance.
Mistake #4: Ignoring loan maturity and refinancing risk. A hotel that cannot meet permanent-loan underwriting requirements at maturity may require additional equity or a sale.
Mistake #5: Approaching lenders without a complete financial package. Missing operating statements, room metrics, or capital budgets can delay underwriting.
Why Work With a Commercial Mortgage Advisor?
Hotel financing is not a one-size-fits-all transaction.
Different lenders have different appetites for hospitality assets, franchise brands, loan sizes, markets, borrower profiles, and business plans.
Working with a commercial mortgage advisor can help borrowers compare loan structures, identify financing constraints, and evaluate multiple capital sources.
Through the CommLoan Empower Program, borrowers can explore financing opportunities using CommLoan's CUPID™ commercial lending platform and its network of 700+ lenders.
The objective is to identify financing that supports the property's operating performance, investment strategy, and long-term goals.
Final Thoughts: Structure the Financing Around the Hotel
Hotel financing requires more than a favorable appraisal or an attractive purchase price.
Successful borrowers understand their hotel's cash flow, operating performance, equity requirements, franchise obligations, and exit strategy before approaching lenders.
Whether you're acquiring your first hospitality property or expanding an established hotel portfolio, preparing the right information and evaluating financing alternatives can make a meaningful difference.
Ready to Explore Hotel Financing?
I'm Bill Rapp, CCIM, with the CommLoan Empower Program.
If you're purchasing, refinancing, renovating, or developing a hotel, let's evaluate the opportunity and determine what financing structure may fit your transaction.
Top of Form
Bottom of Form
Bill Rapp, CCIM
Director | CommLoan
📞 281-222-0433
📧 [email protected]
🌐 https://billrapp.commloan.com/
🌐 https://HoustonCommercialMortgage.com/
Commercial Real Estate Financing Nationwide
https://billrapp.commloan.com/
https://author.billrapponline.com/
https://www.amazon.com/dp/B0F32Z5BH2
https://veed.cello.so/FOmzTty6oi9
https://buymeacoffee.com/vikingente3
https://creplaybookseries.billrapponline.com
https://creplaybook.billrapponline.com/
©Bill Rapp, CCIM - Director - CommLoan
Main Office:
Medallion Funds
[email protected]
11920 Southern Highlands PKWY Suite 302Las Vegas, NV 89141
Texas Complaint and Recovery Fund Notice
All Rights Reserved Copyright © 2021 - Bill Rapp The Mortgage Viking | NMLS #228246