ATTENTION: For Those who are serious about Getting Pre-Qualified FAST!
Bill Rapp, Mortgage Originator: NMLS 228246
"Brokers Are Better.
Better Pricing, Better Service!"
Subscribe To My List Below To Get Your Mortgage Quote Now!
Simply enter your name and email below:
WITH PROVEN STRATEGIES & PROVEN RESULTS
HERE'S WHAT MY CLIENTS SAY:
What People Are Saying:
Excellent Service
Bill is an exceptional loan officer. He helped us to purchase our home with very personal and professional service. He helped us navigate the whole process from start to closing without any problems. We didn't think we're qualified to purchase a house, but Bill went above and beyond to find a way to help us achieve our goal. He always responded very quickly with our requests, he would come back with different options with comparison chart to clearly indicate how much we need for down payment, monthly payments, interest rates, closing costs etc.
We would highly recommend Bill to anyone in need of lending services. In fact, we have already recommended Bill to one of our friends on purchasing a house.
--- David Chan - Houston, TX
Bank Statement Lending!
William Rapp of Network Funding, L. P. was very professional and I felt comfortable in dealing with him. I will definitely recommend him to family and friends.
--- Ian F - Missouri City, TX
Professionalism - Expert In Home Style Loan
Bill is an expert in the topic, his explanations and online material make a difference and he is always there from the beginning to the end. He is committed to make thing happen.
--- Felipe Caldern & Carolina Angel Gutierrez
Great Service!
Bill Rapp's handling of our loan (even though out of state) was unparalleled to any service I have been through prior, including 3 different real estate transactions and multiple refinances. Extremely quick close, with great options and flexibility for my families needs. All around A+
--- Chris & Beth Sheehan - San Jose, CA
Knowledgeable and Responsive!
Bill was a pleasure to work with and he made the loan process fairly easy. He answered all questions I had very quickly and was straight forward in doing it. I would recommend Bill to others.
--- Wes Brady - Richmond, TX
Very professional and always returned our calls!
Bill takes a lot of pride in his job and is very dependable. They were very patient and understanding. He went out of his way and explained all my questions and concerns. They were very professional and returned my phone calls and emails. He did a great job and I fully recommend him.
--- Therese, Malcom & Shirley Teixeira - Katy, TX
Great Job!
Bill helped us out from beginning to end of loan process. The loan closed in a timely manner as Bill worked hard with bank to get our to the final steps.
--- Kamal & Theresa Wilson - Hartford, CT
Avid Problem-Solver and Absolute Pleasure to Work With!
Bill Rapp worked very hard to ensure that we closed our loan and were able to move into our new home. He always had alternatives to any problems we encountered while closing. He worked with us from the beginning identifying solutions to any problems that we were having. He was an absolute pleasure to work with!
--- Nikita Rayani & Sanit Tejani - Houston, TX
Awesome to work with!
Being a first-time buyer I came in with lots of questions and concerns. Bill was always available for any questions I had and answered everything to my satisfaction. Bill made the loan process so painless that I could still concentrate on other things. We ended up closing early which made things even better. If you are in need of a lender and want someone who is very approachable and stays on top of your loan then Bill is your guy.
--- Cesar Raya - Richmond, TX
Loan Declined by my bank, and he saved the day!
Bill, did an amazing job helping me close on my house. He took the reigns and reassured me the best route to take to help close. He was accountable, thorough and trustworthy. I will continue to work with Network Funding, L.P. when it comes to home buying in the future because of the quality of service Bill gave.
--- Jacob Smith - Boerne, TX
Bill Rapp Will Definitely Make It Happen!
Bill is the most kind, patient and helpful person I have ever known. He answers his phone calls and emails promptly. You can ask him a million questions, and he will answer each and every one of them. Before I started working with Bill, I had been turned down for a home loan, because of some past credit issues I had, plus I was a single mother. However, once I started working with Bill, he was able to quickly get me a home loan, with a good interest rate. I would recommend that you call him, as he will help you.
--- Corinne Wilson - Roselle, NJ
Knowledgeable, Honest, Trustworthy, and Reliable!
"I will definitely keep you in mind. If anyone I know needs financing, I will send them your way!"
--- Jon & Andrea Saleem, CRPC Financial Advisor - Houston, TX
Best Dam Mortgage Guy a man could know!
"Hands down the best loan experience to date!"
--- Gabe & Chelsea Jackson - Pearland, TX
Phenomenal, Hard Working and Never Quits!
Had a stupid foreclosure that could have been avoided if ex’s attny would have sent my buy out offer. So Bill was able to push this through with a 4 year foreclosure. He worked his butt off, was very diligent with his communication; and was very professional talking to me even when I was screaming and/or crying at him. Highly recommend this lender. He really go to the ends of the earth to help you!
--- Liz Keeter - Harlingen, TX
Exceptional customer service!
Bill is the most kind, patient and helpful person I have ever known. He answers his phone calls and emails promptly. You can ask him a million questions, and he will answer each and every one of them. Before I started working with Bill, I had been turned down for a home loan, because of some past credit issues I had, plus I was a single mother. However, once I started working with Bill, he was able to quickly get me a home loan, with a good interest rate. I would recommend that you call him, as he will help you.
--- Isha Lopez & Mauricio Garcia - Houston, TX
Service with a capitol S
Bill went above and beyond at every turn. He worked late on Saturday, he worked late all the time. We wanted to close ASAP and he really helped make it happen for us.
--- Jeff & Wendy Heger - Houston, TX
Best Buying Experience!
I would would highly recommend going with Network Funding LP. As a first time home buyer I didn't know what to expect. Bill Rapp was very helpful in answering all my questions and guided me through all ghe steps. I couldn't have asked for a better buying experience!
--- Tabitha Turner - Humble, TX
Would recommend him and use him again!
Very involved and professional . Kept me informed and up to date on everything that was going on Went with me closing and was very helpful and knowledgeable.
--- Kathy Ward - Houston, TX
Great experience!
Well I meet bill back in December 2016 he got recommended by my real estate agent we had a house in sight and started the process to get approved but we fail due to my work history and credit bill told me not to give up and put me in contact with a credit repair company they help me bring my score up and bill walk me thru the process of getting a new line so this time around we got approved before looking for our house after we found it we still had a couple of hick up but with bills help on Sunday 6-18-17 to be exact Father's Day bill called me to give me the great news that we had got approved and the closing date was as scheduled bill was more than just a lender to my family he became a friend and I'm alway going to have him in mind for any other financial situation.
--- Alejandres Felimon - Richmond, TX
I really liked his attitude!
I wouldn't usually say this but the way he had handled my mortgage was really pleasant. I personally enjoyed the time spent with him while we discussed feasible rates. He's a great man with a great personality and he offered really low interests as well. Definitely recommend him to others.
--- Tom Troiano - Atlantic City, NJ
He's nothing short of a miracle!
I'm a self-employed businessman and had him figure out the mortgage of the house after 30% down payment. The interest rates I received were incredibly low given what I had thought of earlier. One other important thing to note was that I hadn't really taken any loans earlier, so I had no credit history. He helped me out with all that as well so I can't really call him anything else but a miracle.
--- Fran Suarez - Cleveland, OH
He's really helpful!
I made a bid to him and the very same day he gave me an offer which I couldn't resist. It was too intimidating with those incredibly low interest rates and all, thoroughly recommend him.
--- Kenny Mickle - Houston, TX
Expeditious!
Bill was very expeditious and made it real easy going through the loan process. I felt he was on top of things.
I deal with investment properties and will more than likely call on him again.
--- Wayne King - Pensacola, FL
Bill was great!
Bill made us feel like a friend all the way thru the process. He was patient and explained everything he needed clearly. He was available ANYTIME we had questions or needed more information. Hopefully we won’t go thru this process again anytime soon, but if we do - we’d choose Bill! =)
--- Barbra & Nick Grimmer - Austin, TX
Great broker!
Bill was a great broker to work with. As first time home buyers we had many questions about the process, Bill took the time to help us even calling us back on weekends with answers. I would not hesitate to recommend him to anyone looking for a broker to work with.
--- Murray & Lisa Turner - Pensacola, FL
Outstanding service!
I couldn't have been more pleased with Bill's level of service. He made what is typically a lengthy, arduous process far quicker and easier at every turn. I'm extremely comfortable recommending Bill to friends and family, and will definitely utilize his services again!
--- Jim Lipari - Austin, TX
Step-by-Step Guide to the VA Loan Process
6 Easy Steps to a VA Loan
For many borrowers, applying for any kind of mortgage may seem daunting.
But, when broken down, this rundown of 6 steps to getting a VA loan is easy to understand.
1. Select a VA-approved Lender
On the surface, it might appear that any lender will do. However, if you dig a little deeper, you may discover that not all lenders are the same. First, only lenders approved by the U.S. Department of Veterans Affairs can originate VA mortgages. Secondly, some lenders focus primarily on conventional loans, while others concentrate almost exclusively on the VA loan program for military clients. Using a VA specialty lender with extensive knowledge about the VA loan process vs. a lender who only funds a few VA mortgages a year may translate into an easier and quicker loan process. To connect with a VA specialty lender, please click here.
2. Obtain a Certificate of Eligibility (COE)
An experienced lender can help you obtain what’s called a Certificate of Eligibility (COE). The COE will prove that you meet initial eligibility standards for VA loan benefits. It will also let the lender know how much entitlement you can receive, which is the amount the Department of Veterans Affairs will guarantee on your VA loan. To get your COE, you’ll need to give your lender a bit of information about your military service. Usually, a COE can be acquired online instantly through a lender’s portal or through the eBenefits portal on the va.gov website. Those servicemembers or surviving spouses whose COEs cannot be obtained online will have to get theirs by mail. A VA lender or the VA can help direct you to the right resource for your specific situation.
3. Pre-Qualify for Your Loan Amount
Pre-qualifying is important, but not required. By choosing to complete this step you can save some time and potential surprises later in the process. To pre-qualify for your loan amount, you’ll have a candid conversation with your VA loan professional about your income, credit history, employment, marital status and other factors. Giving your lender complete details during the pre-qualifying step can help prevent surprises later during underwriting. The pre-qualifying step can also reveal areas that need improvement before you can be approved, such as credit or debt-to-income ratio. While a prequalification letter gives you a ballpark price range for house hunting, it does not guarantee that you will be approved for a loan, and your lender will later have to verify the information you provide. To get a loan requires later final approval by underwriting once all documents have been received and reviewed (see Step 5).
4. Go House Hunting & Find Home
The fourth step is usually one borrowers enjoy because they get to look at homes they might consider buying. Working with a real estate professional who specializes in the VA process can help you get the most out of your benefits. This is true because the VA allows certain fees and costs to be paid by the seller (if both you and the seller agree), and a knowledgeable agent will know this and help you negotiate seller-paid fees. Once you’ve got a signed purchase agreement, you can move forward in the VA loan process.
5. Lender Processes Application
& Orders VA Appraisal
A signed purchase contract is the document you’ll need to finish your initial application. Once your lender has the contract, they will order the VA appraisal. Here again, not just any appraiser will do. Only a professional who is certified to perform appraisals to VA standards can evaluate the home being considered for VA financing. The VA appraiser will make sure the price you’ve agreed to pay for the home corresponds with the current value. Another very important part of the VA appraisal is to inspect the home to make sure it meets the VA minimum property requirements (VA MPRs). However, the VA appraisal does not take the place of a home inspection, which focuses on code violations, defects and the condition of the property. While many borrowers have heard horror stories about the length of the VA appraisal process, the Department of Veterans Affairs gives the appraisers 10 days from order to completion barring extenuating circumstances. While you’re waiting for appraisal documents, you’ll be busy submitting documents of your own to your VA-approved lender to show you have the ability to qualify for the loan. If the home passes appraisal for value and VA minimum property requirements, and it’s verified by the lender that you qualify for your loan, the underwriter will give his or her stamp of approval.
6. Close on Your Loan and Move In
After being approved by the underwriter, all that is left to do is close and move in. During closing, the property legally transfers from the former owner to you. Closing is a step that requires you to sign documents that confirm you understand and agree to the terms of the loan. You will need to provide proof of homeowners insurance and, if required, pay closing costs. Once you’ve signed all your closing documents, you’ll get the keys to your new home.
While these steps may not happen in the order above or be a required part (such as prequalification)*, they represent the typical process for the applicant in obtaining a VA purchase loan. Your lender may need to take other steps. For more information about VA loans, contact an experienced VA-approved lender.
My best advice to you is to call Bill Rapp, the Mortgage Viking, today to discuss your options 281-222-0433.
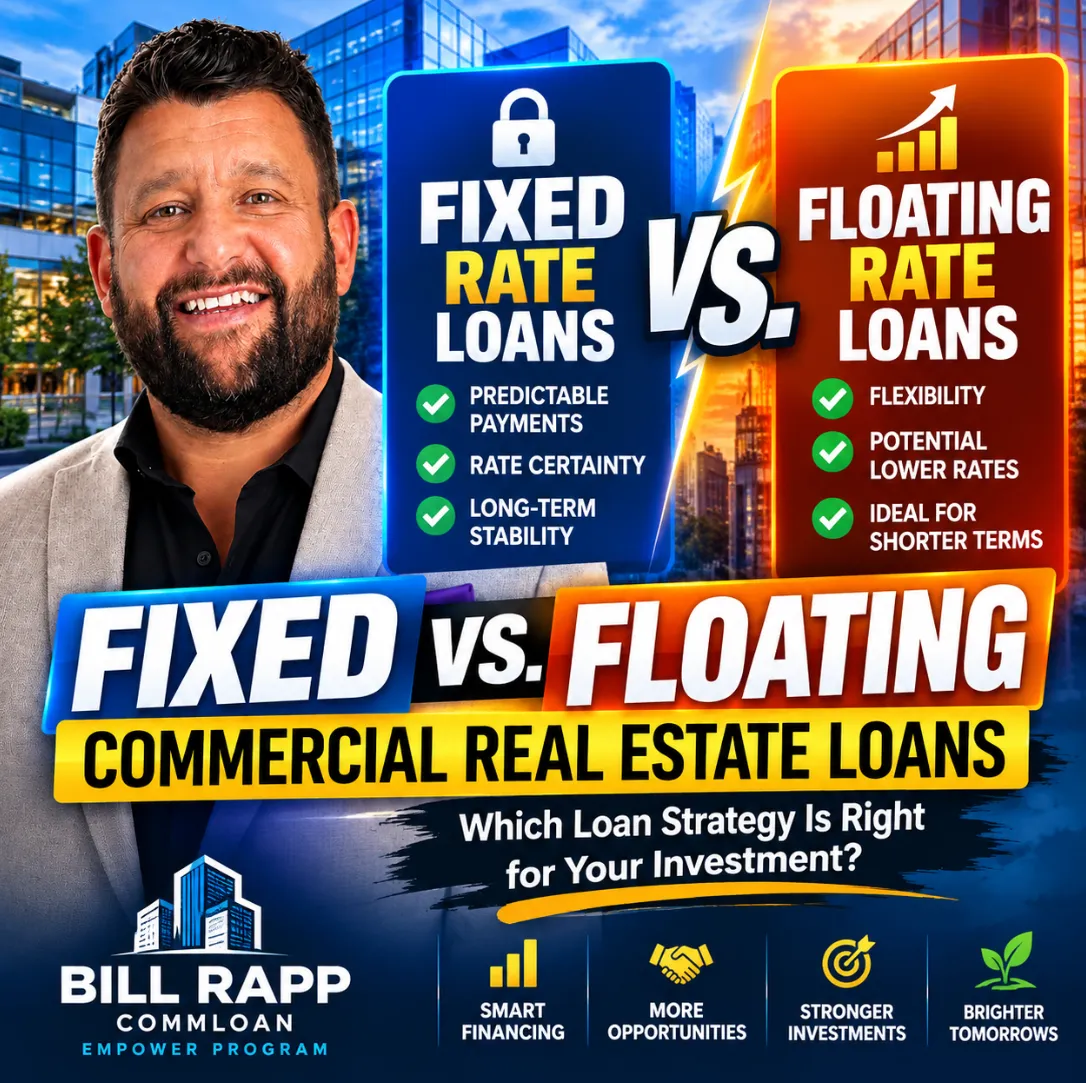
🏢 Fixed vs. Floating Commercial Real Estate Loans: Which Interest Rate Strategy Fits Your CRE Investment? 📈
🏢 Fixed vs. Floating Commercial Real Estate Loans: Which Interest Rate Strategy Fits Your CRE Investment? 📈
💰 Fixed Rate vs. Floating Rate CRE Loans: What Commercial Property Investors Need to Know 🔐
_______________________________________________________________________________
Fixed vs. Floating Commercial Real Estate Loans: Understanding the Difference
When financing commercial real estate, one of the most important decisions isn't simply which lender offers the lowest interest rate. You also need to understand how that interest rate behaves over the life of the loan.
Commercial real estate loans generally fall into two broad interest-rate structures: fixed-rate loans and floating-rate loans.
A fixed rate can provide payment certainty and protection against rising rates. A floating rate can provide flexibility and potentially allow a borrower to benefit if benchmark rates decline.
Neither structure is automatically better. The appropriate financing structure depends on the property, business plan, anticipated hold period, cash flow, risk tolerance, prepayment provisions, and capital strategy.
What Is a Fixed-Rate Commercial Real Estate Loan?
A fixed-rate commercial real estate loan locks the interest rate according to the terms of the loan.
If your loan carries a fixed interest rate, movements in market interest rates generally won't change your contractual rate during the fixed-rate period.
That creates one significant advantage: predictability.
Investors can more confidently forecast debt service and evaluate metrics such as:
·Debt Service Coverage Ratio (DSCR)
·Cash-on-cash return
·Break-even occupancy
·Property cash flow
·Investment distributions
This can be especially valuable for stabilized commercial properties expected to be held for several years.
Advantages of Fixed-Rate CRE Loans
The biggest benefit is interest-rate certainty.
If market rates increase after closing, the borrower's fixed contractual rate isn't repriced simply because benchmark rates moved higher.
Fixed-rate financing can therefore make sense when an investor prioritizes stable debt service and expects to hold an asset over a longer period.
It can also simplify underwriting projections because future debt-service obligations are more predictable.
But that stability can come with tradeoffs.
Some fixed-rate commercial mortgages have more restrictive prepayment provisions. Depending on the loan program, borrowers could encounter a prepayment penalty, yield-maintenance provision, defeasance requirement, or another form of exit cost.
That matters if you're planning to sell or refinance before maturity.
What Is a Floating-Rate Commercial Real Estate Loan?
A floating-rate commercial real estate loan has an interest rate that can adjust based on an underlying benchmark plus a lender spread.
A simplified structure might look like:
Benchmark Rate + Lender Spread = Borrower's Interest Rate
As the benchmark changes, the borrower's rate can change according to the loan documents.
That creates both opportunity and risk.
If applicable benchmark rates decline, borrowing costs may decline. If benchmark rates rise, however, debt service can increase.
For commercial property investors, that means floating-rate financing requires greater attention to interest-rate risk and property cash flow.
When Floating-Rate Financing Can Make Sense
Floating-rate loans are frequently associated with situations where flexibility matters.
Consider an investor purchasing a property that requires renovation, lease-up, repositioning, or another value-add strategy.
The investor might plan to:
Acquire → Improve → Stabilize → Refinance or Sell
If the anticipated investment period is relatively short, taking long-term fixed-rate financing with restrictive prepayment provisions may not align with the business plan.
A floating-rate bridge or transitional loan may provide a financing structure better aligned with the property's execution period.
The Risk Investors Cannot Ignore
The primary concern with floating-rate debt is straightforward:
Your debt service can increase.
Suppose a property's NOI remains relatively stable while its interest expense increases.
Higher debt service can reduce cash flow and weaken DSCR.
For example, imagine a property generates $300,000 of annual NOI.
If annual debt service is $200,000:
DSCR = $300,000 ÷ $200,000 = 1.50x
If higher floating rates push annual debt service to $240,000:
DSCR = $300,000 ÷ $240,000 = 1.25x
The property's NOI hasn't changed, but its debt-service cushion has narrowed substantially.
That can affect distributions, refinance options, covenant compliance, and potentially the amount of permanent debt available later.
Interest-Rate Caps Matter
One tool used with some floating-rate commercial loans is an interest-rate cap.
A rate cap can limit exposure to increases in an underlying benchmark according to the cap agreement.
Certain lenders may require borrowers to purchase a cap at closing, particularly on bridge and other floating-rate transactions.
Borrowers should understand the cap's:
·Strike rate
·Term
·Cost
·Notional amount
·Renewal requirements
The existence of a cap doesn't eliminate the need to analyze floating-rate risk.
Don't Choose a Loan Based Only on Today's Rate
One of the biggest commercial financing mistakes is comparing loans using only the quoted interest rate.
Imagine receiving two financing proposals.
Loan A offers a lower initial floating rate.
Loan B offers a somewhat higher fixed rate.
Loan A might initially appear cheaper. But what happens if rates rise? How long do you plan to hold the property? What happens if you sell in two years? Does Loan B carry a substantial prepayment cost?
The lowest rate on closing day isn't necessarily the lowest-cost financing strategy over your actual investment horizon.
Compare the Entire Capital Structure
Commercial real estate borrowers should evaluate several variables together rather than focusing on a single number.
Those variables include interest rate, amortization, loan term, fixed versus floating structure, recourse, prepayment provisions, lender fees, reserves, DSCR requirements, LTV, debt yield, rate caps and extension options.
A loan should ultimately support the business plan for the property.
Fixed Rate May Fit When...
A fixed-rate structure may align with investors who prioritize predictable debt service, stable long-term cash flow, protection against increasing interest rates, longer anticipated holding periods, and certainty in investment projections.
For example, an investor acquiring a fully stabilized multifamily, industrial, retail, or office property for a long-term hold may place significant value on payment stability.
Floating Rate May Fit When...
Floating-rate financing may align with strategies involving shorter anticipated holding periods, renovations, lease-up, transitional properties, bridge financing, future refinancing plans, or a need for greater exit flexibility.
The critical issue is whether the borrower and property can withstand adverse rate movements during the expected loan period.
Stress-Test the Loan Before Closing
Borrowers considering floating-rate financing should model more than the initial payment.
Ask:
What happens if the benchmark rate increases by 1%?
What about 2%?
Does the property still generate acceptable cash flow?
Does DSCR remain above the lender's required threshold?
How does a higher rate affect the eventual refinance?
That sensitivity analysis can reveal risks that aren't obvious from the initial term sheet.
Match the Debt to the Investment Strategy
The fixed-versus-floating decision ultimately comes back to one principle:
Match your financing strategy to your commercial real estate strategy.
A stabilized property with a long-term hold strategy has different financing needs than a transitional asset that an investor intends to renovate, stabilize and refinance within 24 months.
Commercial real estate financing shouldn't be treated as a commodity where the only objective is finding the lowest advertised rate.
The objective is finding debt that supports the investment plan while managing risk.
How the CommLoan Empower Program Can Help
Commercial real estate financing varies significantly by lender, property type, borrower profile and transaction structure.
Through the CommLoan Empower Program, I help commercial real estate investors and business owners evaluate financing alternatives and identify structures that fit the underlying transaction.
That includes looking beyond rate to evaluate factors such as leverage, DSCR, amortization, loan term, recourse, prepayment provisions, reserves, rate structure and exit strategy.
Because sometimes the better question isn't:
“What's the lowest rate?”
It's:
“Which loan structure best supports what I'm trying to accomplish with this property?”
Bill Rapp | CommLoan Empower Program
Commercial Real Estate Financing
Top of Form
Bottom of Form
Bill Rapp, CCIM
Director | CommLoan
📞 281-222-0433
📧 [email protected]
🌐 https://billrapp.commloan.com/
🌐 https://HoustonCommercialMortgage.com/
Commercial Real Estate Financing Nationwide
https://billrapp.commloan.com/
https://author.billrapponline.com/
https://www.amazon.com/dp/B0F32Z5BH2
https://veed.cello.so/FOmzTty6oi9
https://buymeacoffee.com/vikingente3
https://creplaybookseries.billrapponline.com
https://creplaybook.billrapponline.com/
©Bill Rapp, CCIM - Director - CommLoan
Main Office:
Medallion Funds
[email protected]
11920 Southern Highlands PKWY Suite 302Las Vegas, NV 89141
Texas Complaint and Recovery Fund Notice
All Rights Reserved Copyright © 2021 - Bill Rapp The Mortgage Viking | NMLS #228246