ATTENTION: For Those who are serious about Getting Pre-Qualified FAST!
Bill Rapp, Mortgage Originator: NMLS 228246
"Brokers Are Better.
Better Pricing, Better Service!"
Subscribe To My List Below To Get Your Mortgage Quote Now!
Simply enter your name and email below:
WITH PROVEN STRATEGIES & PROVEN RESULTS
HERE'S WHAT MY CLIENTS SAY:
What People Are Saying:
Excellent Service
Bill is an exceptional loan officer. He helped us to purchase our home with very personal and professional service. He helped us navigate the whole process from start to closing without any problems. We didn't think we're qualified to purchase a house, but Bill went above and beyond to find a way to help us achieve our goal. He always responded very quickly with our requests, he would come back with different options with comparison chart to clearly indicate how much we need for down payment, monthly payments, interest rates, closing costs etc.
We would highly recommend Bill to anyone in need of lending services. In fact, we have already recommended Bill to one of our friends on purchasing a house.
--- David Chan - Houston, TX
Bank Statement Lending!
William Rapp of Network Funding, L. P. was very professional and I felt comfortable in dealing with him. I will definitely recommend him to family and friends.
--- Ian F - Missouri City, TX
Professionalism - Expert In Home Style Loan
Bill is an expert in the topic, his explanations and online material make a difference and he is always there from the beginning to the end. He is committed to make thing happen.
--- Felipe Caldern & Carolina Angel Gutierrez
Great Service!
Bill Rapp's handling of our loan (even though out of state) was unparalleled to any service I have been through prior, including 3 different real estate transactions and multiple refinances. Extremely quick close, with great options and flexibility for my families needs. All around A+
--- Chris & Beth Sheehan - San Jose, CA
Knowledgeable and Responsive!
Bill was a pleasure to work with and he made the loan process fairly easy. He answered all questions I had very quickly and was straight forward in doing it. I would recommend Bill to others.
--- Wes Brady - Richmond, TX
Very professional and always returned our calls!
Bill takes a lot of pride in his job and is very dependable. They were very patient and understanding. He went out of his way and explained all my questions and concerns. They were very professional and returned my phone calls and emails. He did a great job and I fully recommend him.
--- Therese, Malcom & Shirley Teixeira - Katy, TX
Great Job!
Bill helped us out from beginning to end of loan process. The loan closed in a timely manner as Bill worked hard with bank to get our to the final steps.
--- Kamal & Theresa Wilson - Hartford, CT
Avid Problem-Solver and Absolute Pleasure to Work With!
Bill Rapp worked very hard to ensure that we closed our loan and were able to move into our new home. He always had alternatives to any problems we encountered while closing. He worked with us from the beginning identifying solutions to any problems that we were having. He was an absolute pleasure to work with!
--- Nikita Rayani & Sanit Tejani - Houston, TX
Awesome to work with!
Being a first-time buyer I came in with lots of questions and concerns. Bill was always available for any questions I had and answered everything to my satisfaction. Bill made the loan process so painless that I could still concentrate on other things. We ended up closing early which made things even better. If you are in need of a lender and want someone who is very approachable and stays on top of your loan then Bill is your guy.
--- Cesar Raya - Richmond, TX
Loan Declined by my bank, and he saved the day!
Bill, did an amazing job helping me close on my house. He took the reigns and reassured me the best route to take to help close. He was accountable, thorough and trustworthy. I will continue to work with Network Funding, L.P. when it comes to home buying in the future because of the quality of service Bill gave.
--- Jacob Smith - Boerne, TX
Bill Rapp Will Definitely Make It Happen!
Bill is the most kind, patient and helpful person I have ever known. He answers his phone calls and emails promptly. You can ask him a million questions, and he will answer each and every one of them. Before I started working with Bill, I had been turned down for a home loan, because of some past credit issues I had, plus I was a single mother. However, once I started working with Bill, he was able to quickly get me a home loan, with a good interest rate. I would recommend that you call him, as he will help you.
--- Corinne Wilson - Roselle, NJ
Knowledgeable, Honest, Trustworthy, and Reliable!
"I will definitely keep you in mind. If anyone I know needs financing, I will send them your way!"
--- Jon & Andrea Saleem, CRPC Financial Advisor - Houston, TX
Best Dam Mortgage Guy a man could know!
"Hands down the best loan experience to date!"
--- Gabe & Chelsea Jackson - Pearland, TX
Phenomenal, Hard Working and Never Quits!
Had a stupid foreclosure that could have been avoided if ex’s attny would have sent my buy out offer. So Bill was able to push this through with a 4 year foreclosure. He worked his butt off, was very diligent with his communication; and was very professional talking to me even when I was screaming and/or crying at him. Highly recommend this lender. He really go to the ends of the earth to help you!
--- Liz Keeter - Harlingen, TX
Exceptional customer service!
Bill is the most kind, patient and helpful person I have ever known. He answers his phone calls and emails promptly. You can ask him a million questions, and he will answer each and every one of them. Before I started working with Bill, I had been turned down for a home loan, because of some past credit issues I had, plus I was a single mother. However, once I started working with Bill, he was able to quickly get me a home loan, with a good interest rate. I would recommend that you call him, as he will help you.
--- Isha Lopez & Mauricio Garcia - Houston, TX
Service with a capitol S
Bill went above and beyond at every turn. He worked late on Saturday, he worked late all the time. We wanted to close ASAP and he really helped make it happen for us.
--- Jeff & Wendy Heger - Houston, TX
Best Buying Experience!
I would would highly recommend going with Network Funding LP. As a first time home buyer I didn't know what to expect. Bill Rapp was very helpful in answering all my questions and guided me through all ghe steps. I couldn't have asked for a better buying experience!
--- Tabitha Turner - Humble, TX
Would recommend him and use him again!
Very involved and professional . Kept me informed and up to date on everything that was going on Went with me closing and was very helpful and knowledgeable.
--- Kathy Ward - Houston, TX
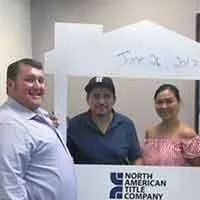
Great experience!
Well I meet bill back in December 2016 he got recommended by my real estate agent we had a house in sight and started the process to get approved but we fail due to my work history and credit bill told me not to give up and put me in contact with a credit repair company they help me bring my score up and bill walk me thru the process of getting a new line so this time around we got approved before looking for our house after we found it we still had a couple of hick up but with bills help on Sunday 6-18-17 to be exact Father's Day bill called me to give me the great news that we had got approved and the closing date was as scheduled bill was more than just a lender to my family he became a friend and I'm alway going to have him in mind for any other financial situation.
--- Alejandres Felimon - Richmond, TX
I really liked his attitude!
I wouldn't usually say this but the way he had handled my mortgage was really pleasant. I personally enjoyed the time spent with him while we discussed feasible rates. He's a great man with a great personality and he offered really low interests as well. Definitely recommend him to others.
--- Tom Troiano - Atlantic City, NJ
He's nothing short of a miracle!
I'm a self-employed businessman and had him figure out the mortgage of the house after 30% down payment. The interest rates I received were incredibly low given what I had thought of earlier. One other important thing to note was that I hadn't really taken any loans earlier, so I had no credit history. He helped me out with all that as well so I can't really call him anything else but a miracle.
--- Fran Suarez - Cleveland, OH
He's really helpful!
I made a bid to him and the very same day he gave me an offer which I couldn't resist. It was too intimidating with those incredibly low interest rates and all, thoroughly recommend him.
--- Kenny Mickle - Houston, TX
Expeditious!
Bill was very expeditious and made it real easy going through the loan process. I felt he was on top of things.
I deal with investment properties and will more than likely call on him again.
--- Wayne King - Pensacola, FL
Bill was great!
Bill made us feel like a friend all the way thru the process. He was patient and explained everything he needed clearly. He was available ANYTIME we had questions or needed more information. Hopefully we won’t go thru this process again anytime soon, but if we do - we’d choose Bill! =)
--- Barbra & Nick Grimmer - Austin, TX
Great broker!
Bill was a great broker to work with. As first time home buyers we had many questions about the process, Bill took the time to help us even calling us back on weekends with answers. I would not hesitate to recommend him to anyone looking for a broker to work with.
--- Murray & Lisa Turner - Pensacola, FL
Outstanding service!
I couldn't have been more pleased with Bill's level of service. He made what is typically a lengthy, arduous process far quicker and easier at every turn. I'm extremely comfortable recommending Bill to friends and family, and will definitely utilize his services again!
--- Jim Lipari - Austin, TX
Step-by-Step Guide to the VA Loan Process
6 Easy Steps to a VA Loan
For many borrowers, applying for any kind of mortgage may seem daunting.
But, when broken down, this rundown of 6 steps to getting a VA loan is easy to understand.
1. Select a VA-approved Lender
On the surface, it might appear that any lender will do. However, if you dig a little deeper, you may discover that not all lenders are the same. First, only lenders approved by the U.S. Department of Veterans Affairs can originate VA mortgages. Secondly, some lenders focus primarily on conventional loans, while others concentrate almost exclusively on the VA loan program for military clients. Using a VA specialty lender with extensive knowledge about the VA loan process vs. a lender who only funds a few VA mortgages a year may translate into an easier and quicker loan process. To connect with a VA specialty lender, please click here.
2. Obtain a Certificate of Eligibility (COE)
An experienced lender can help you obtain what’s called a Certificate of Eligibility (COE). The COE will prove that you meet initial eligibility standards for VA loan benefits. It will also let the lender know how much entitlement you can receive, which is the amount the Department of Veterans Affairs will guarantee on your VA loan. To get your COE, you’ll need to give your lender a bit of information about your military service. Usually, a COE can be acquired online instantly through a lender’s portal or through the eBenefits portal on the va.gov website. Those servicemembers or surviving spouses whose COEs cannot be obtained online will have to get theirs by mail. A VA lender or the VA can help direct you to the right resource for your specific situation.
3. Pre-Qualify for Your Loan Amount
Pre-qualifying is important, but not required. By choosing to complete this step you can save some time and potential surprises later in the process. To pre-qualify for your loan amount, you’ll have a candid conversation with your VA loan professional about your income, credit history, employment, marital status and other factors. Giving your lender complete details during the pre-qualifying step can help prevent surprises later during underwriting. The pre-qualifying step can also reveal areas that need improvement before you can be approved, such as credit or debt-to-income ratio. While a prequalification letter gives you a ballpark price range for house hunting, it does not guarantee that you will be approved for a loan, and your lender will later have to verify the information you provide. To get a loan requires later final approval by underwriting once all documents have been received and reviewed (see Step 5).
4. Go House Hunting & Find Home
The fourth step is usually one borrowers enjoy because they get to look at homes they might consider buying. Working with a real estate professional who specializes in the VA process can help you get the most out of your benefits. This is true because the VA allows certain fees and costs to be paid by the seller (if both you and the seller agree), and a knowledgeable agent will know this and help you negotiate seller-paid fees. Once you’ve got a signed purchase agreement, you can move forward in the VA loan process.
5. Lender Processes Application
& Orders VA Appraisal
A signed purchase contract is the document you’ll need to finish your initial application. Once your lender has the contract, they will order the VA appraisal. Here again, not just any appraiser will do. Only a professional who is certified to perform appraisals to VA standards can evaluate the home being considered for VA financing. The VA appraiser will make sure the price you’ve agreed to pay for the home corresponds with the current value. Another very important part of the VA appraisal is to inspect the home to make sure it meets the VA minimum property requirements (VA MPRs). However, the VA appraisal does not take the place of a home inspection, which focuses on code violations, defects and the condition of the property. While many borrowers have heard horror stories about the length of the VA appraisal process, the Department of Veterans Affairs gives the appraisers 10 days from order to completion barring extenuating circumstances. While you’re waiting for appraisal documents, you’ll be busy submitting documents of your own to your VA-approved lender to show you have the ability to qualify for the loan. If the home passes appraisal for value and VA minimum property requirements, and it’s verified by the lender that you qualify for your loan, the underwriter will give his or her stamp of approval.
6. Close on Your Loan and Move In
After being approved by the underwriter, all that is left to do is close and move in. During closing, the property legally transfers from the former owner to you. Closing is a step that requires you to sign documents that confirm you understand and agree to the terms of the loan. You will need to provide proof of homeowners insurance and, if required, pay closing costs. Once you’ve signed all your closing documents, you’ll get the keys to your new home.
While these steps may not happen in the order above or be a required part (such as prequalification)*, they represent the typical process for the applicant in obtaining a VA purchase loan. Your lender may need to take other steps. For more information about VA loans, contact an experienced VA-approved lender.
My best advice to you is to call Bill Rapp, the Mortgage Viking, today to discuss your options 281-222-0433.
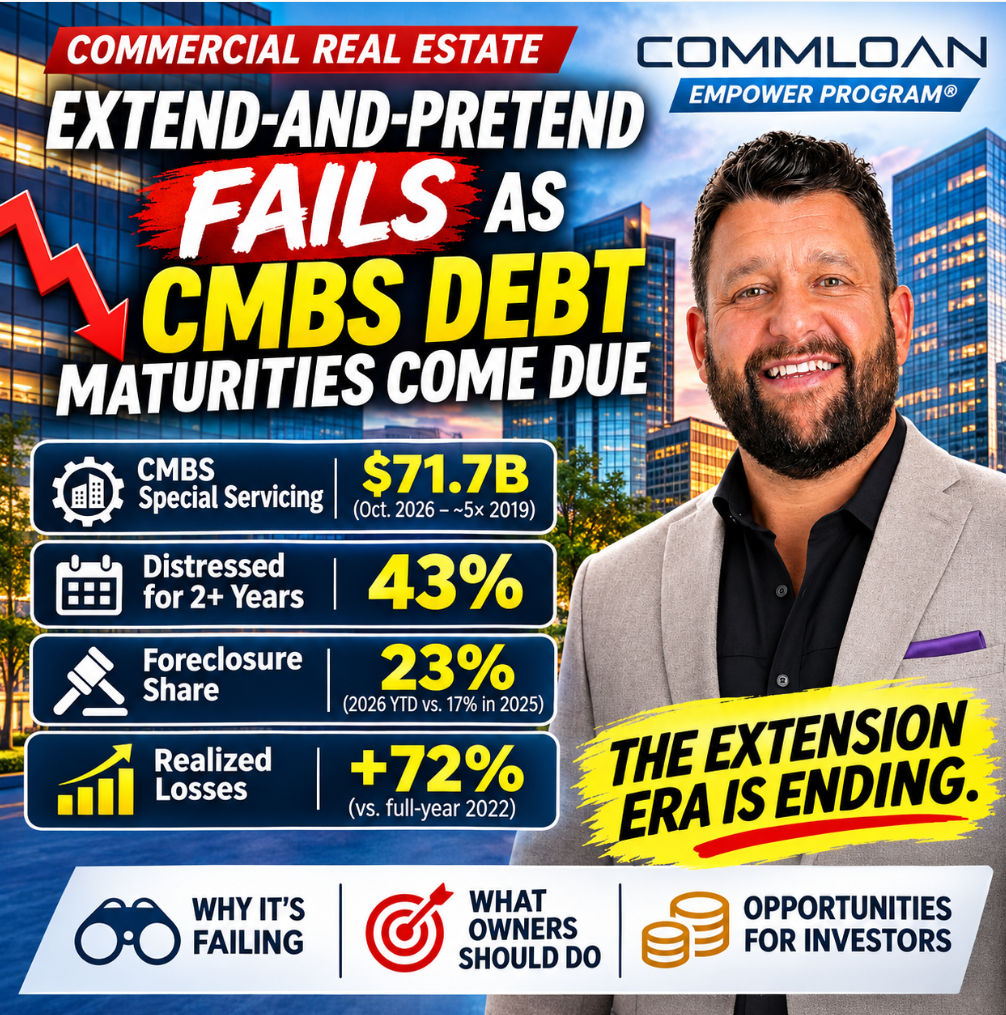
🚨 CMBS Loan Maturities: Extend-and-Pretend Fails! 📉
🚨 CMBS Loan Maturities: Extend-and-Pretend Fails! 📉
🏢 Commercial Real Estate Debt Crisis: 2027 Outlook ⚠️
_________________________________________________________________________
CMBS Loan Maturities: Why Extend-and-Pretend Is Failing Heading Into 2027
With $71.7 billion in CMBS loans under special servicing, commercial real estate owners face mounting refinancing pressure. Learn why loan extensions are losing effectiveness and what investors should do next.
The Commercial Real Estate Debt Problem Is Getting Harder to Ignore
For the past several years, commercial real estate lenders have relied on a relatively straightforward strategy for troubled loans: extend the maturity date, modify the terms, and give property owners additional time to recover.
The industry calls this approach extend-and-pretend.
The expectation was that interest rates would eventually decline, property values would stabilize, and borrowers would refinance their loans under more favorable conditions.
But what happens when those improvements never fully materialize?
According to Trepp CMBS research discussed in a November 18, 2026 GlobeSt article by Erik Sherman, the effectiveness of these loan modifications is deteriorating.
The consequences could extend well beyond the borrowers directly involved.
Commercial property investors, lenders, and business owners may face an increasingly active market for distressed asset sales, refinancing shortfalls, recapitalizations, and loan restructurings heading into 2027.
What Is the Extend-and-Pretend Strategy?
Extend-and-pretend is an informal industry term describing situations in which lenders extend troubled commercial mortgages rather than immediately pursuing foreclosure or another final resolution.
Consider a commercial office property with a $5 million mortgage approaching maturity.
The property was originally financed when borrowing costs were lower and valuations were stronger.
Today, the building might have higher vacancy, declining net operating income, and a lower appraised value.
If the borrower cannot refinance the existing mortgage, the lender may agree to extend the maturity date.
That extension can be reasonable when the property has a credible recovery plan. However, if the underlying cash flow and valuation remain insufficient, the extension may simply postpone an eventual loss.
The critical distinction is whether the loan modification creates a sustainable path to repayment or merely delays recognizing the problem.
The Numbers Behind the CMBS Distress
$71.7B
CMBS special servicing
October 2026
43%
Distressed for 2+ years
Share of specially serviced debt
23%
Foreclosure share
2026 year to date
+72%
Realized loan losses
2026 through October vs. 2022
Source: Trepp CMBS research, as summarized in the supplied November 18, 2026 GlobeSt reporting. These figures describe different populations and periods.
These statistics highlight a market in which distressed commercial mortgages are taking longer to resolve and more loans are reaching adverse outcomes.
1. Loan modifications are declining
Modifications as a share of special-servicing exits
Percentage of balances exiting special servicing through modifications
0%15%30%45%60%202420252026 YTD
In 2024, loan modifications represented 54% of balances exiting special servicing. That declined to 49% in 2025 and 37% in 2026.
The decline suggests that fewer troubled loans are finding resolution through modifications.
Importantly, this does not mean every modification failed. It indicates a changing mix of resolutions, with a greater role for other workout outcomes.
2. Foreclosures are increasing
Foreclosures accounted for 17% of special-servicing exits in 2025, compared with 23% during 2026 year to date.
Foreclosure resolutions averaged approximately 40 months, versus 10 months for loans successfully cured.
Longer resolutions can increase legal expenses, servicing costs, property deterioration risks, and uncertainty over ultimate recoveries.
3. Repeat distress is becoming more common
Approximately 26% of loans cured in 2025 returned to special servicing within 12 months, compared with 17% in the 2022 comparison cohort.
This is particularly important.
A loan leaving special servicing does not necessarily mean the property's financial problems have been permanently resolved.
A property might obtain temporary relief but continue struggling with tenant departures, inadequate cash flow, or refinancing constraints.
4. The distressed loan backlog is aging
Approximately 43% of the $71.7 billion in specially serviced CMBS loans had remained unresolved for at least two years.
That compares with 28% at year-end 2024.
The growing proportion of long-term distressed loans raises questions about collateral recovery, future asset sales, and the timing of price discovery.
5. Realized losses are rising
The research also indicates that realized CMBS losses through October 2026 were approximately 72% higher than the full-year 2022 comparison.
Separately, the proportion of non-payoff special-servicing exits resulting in losses increased 78% since 2022.
These are different measures: one concerns realized loss amounts, while the other concerns the frequency of loss-producing resolutions.
Both point toward greater pressure on distressed loan recoveries.
Why Commercial Mortgage Refinancing Is Becoming More Difficult
Commercial mortgage approval is not determined solely by the borrower's payment history.
Lenders also evaluate the property's ability to support new debt.
Three underwriting metrics are particularly important.
Debt-Service Coverage Ratio (DSCR)
DSCR compares net operating income with annual debt service.
\[ DSCR=\frac{NOI}{Annual\ Debt\ Service} \]
For example, a property generating $400,000 in annual NOI with $320,000 in annual debt service has a DSCR of 1.25.
If NOI falls or refinancing debt service rises, the ratio deteriorates.
Loan-to-Value Ratio (LTV)
LTV measures the loan relative to the property's appraised value.
\[ LTV=\frac{Loan\ Amount}{Property\ Value} \]
A $4 million loan against a $5 million property represents 80% LTV.
If the property's valuation falls to $4.5 million, the same loan represents approximately 88.9% LTV.
Debt Yield
Debt yield measures NOI relative to the loan balance.
\[ Debt\ Yield=\frac{NOI}{Loan\ Amount} \]
A property generating $400,000 in NOI against a $4 million loan produces a 10% debt yield.
At a 12% required debt yield, the same property would support approximately $3.33 million in debt, before considering other underwriting constraints.
This illustrates why a loan that worked several years ago might no longer qualify for the same proceeds.
Real-World Example: A $5 Million Loan Approaching Maturity
Consider an illustrative office or retail investment property.
Underwriting factor | Original position | Current position |
Property value | $7,000,000 | $5,500,000 |
Annual NOI | $500,000 | $400,000 |
Mortgage balance | $5,000,000 | $5,000,000 |
LTV on existing debt | 71.4% | 90.9% |
Debt yield on existing debt | 10.0% | 8.0% |
Now assume a refinancing lender requires a 12% minimum debt yield and a maximum 70% LTV.
Illustrative refinance proceeds
Debt yield limit
$3.33M
70% LTV limit
$3.85M
Binding constraint: debt yield
$1.67M
Potential refinancing shortfall
Before closing costs, reserves, and any additional DSCR restrictions.
Even though the borrower owes $5 million, the lender may only offer approximately $3.33 million.
The owner must address a shortfall of approximately $1.67 million.
Potential solutions include contributing additional equity, negotiating a principal reduction, obtaining subordinate capital where permitted, selling the asset, or pursuing another lender or restructuring solution.
An extension alone does not eliminate that shortfall.
What This Means for Commercial Real Estate Investors
For investors with sufficient liquidity, distressed commercial real estate can create acquisition opportunities.
However, buying a distressed property is not automatically the same as buying an undervalued property.
Investors should carefully evaluate:
Sustainable NOI rather than optimistic projections.
Deferred maintenance and future capital expenditures.
Lease expirations, tenant credit, and rollover exposure.
Property taxes, insurance, and operating expenses.
Realistic exit capitalization rates and refinancing assumptions.
Whether the acquisition price provides an adequate risk-adjusted return.
A discounted acquisition can still produce disappointing results if the property requires substantially more capital than originally anticipated.
What Commercial Property Owners Should Do Before Loan Maturity
Owners approaching commercial mortgage maturity should begin evaluating their options well before the payoff date.
A practical starting point is 12–24 months ahead of maturity for complex or potentially distressed transactions.
Review the loan documents for maturity provisions, extension options, covenants, prepayment restrictions, and any required notices.
Next, update the property's financial package.
Lenders will typically want current rent rolls, trailing operating statements, historical financials, borrower financial information, and relevant lease documentation.
Owners should also obtain realistic refinance estimates based on today's property performance.
If the available proceeds will not cover the existing debt, identifying that gap early creates more options.
Waiting until the final months before maturity can severely limit negotiating flexibility.
Houston, Katy, and West Houston: What Investors Should Watch
National CMBS distress trends deserve attention across the Houston commercial real estate market.
However, national CMBS statistics should not be interpreted as direct evidence that Houston has identical distress levels.
Potentially vulnerable assets include office properties with elevated vacancy, retail centers with weakening tenant performance, multifamily properties facing operating-cost pressure, and industrial properties with concentrated tenant rollover.
In Katy, Fulshear, Brookshire, the Energy Corridor, and West Houston, investors should examine local lease demand, property-specific NOI, financing structures, and upcoming maturity schedules.
Properties with strong locations, durable tenant demand, and conservative leverage may remain attractive even as weaker assets face restructuring pressure.
For well-capitalized buyers, lender-driven sales or ownership recapitalizations could create opportunities.
For existing owners, the priority should be preserving flexibility before a maturity becomes a crisis.
How CommLoan Helps Commercial Borrowers Evaluate Financing Options
Commercial real estate financing is rarely a one-size-fits-all process.
Different lenders can reach different conclusions about the same property's risk, loan structure, amortization, and available proceeds.
Through CommLoan's commercial financing marketplace, borrowers can explore financing alternatives across participating lenders and loan programs.
Depending on the property and borrower, potential financing paths may include conventional commercial mortgages, bridge financing, CMBS alternatives, or eligible SBA financing for owner-occupied properties.
A financing review should examine not only the interest rate but also loan proceeds, debt-service requirements, recourse, reserves, maturity structure, and total transaction costs.
The 2027 Outlook: Prepare for More Price Discovery
The central issue facing commercial real estate is no longer simply the volume of loans reaching maturity.
It is whether current property values and operating income can support the amount of debt that needs to be refinanced.
As extensions expire, some owners may refinance successfully, others may contribute additional capital, and some properties may be sold or transferred through foreclosure.
The outcomes will differ by asset class, geography, sponsorship, and loan structure.
The key lesson for 2027 is that time alone does not repair a capital structure. Sustainable property cash flow, realistic valuations, and adequate liquidity remain essential.
Work With Bill Rapp, CCIM — CommLoan
If your commercial mortgage is approaching maturity, your refinancing proceeds are uncertain, or you are evaluating a distressed property acquisition, an early financing review can help clarify the available options.
I'm Bill Rapp, CCIM, and I help commercial real estate investors and business owners evaluate financing structures and lender alternatives through CommLoan.
Disclaimer: This article is educational and does not constitute a loan commitment, investment recommendation, or legal or tax advice. All financing is subject to lender underwriting, property eligibility, and program requirements.
Source attribution: Erik Sherman, GlobeSt, November 18, 2026, reporting on Trepp CMBS special-servicing and loan-resolution research. Statistics above reflect the supplied research summary.
Top of Form
Bottom of Form
Bill Rapp, CCIM
Director | CommLoan
📞 281-222-0433
📧 [email protected]
🌐 https://billrapp.commloan.com/
🌐 https://HoustonCommercialMortgage.com/
Commercial Real Estate Financing Nationwide
https://billrapp.commloan.com/
https://author.billrapponline.com/
https://www.amazon.com/dp/B0F32Z5BH2
https://veed.cello.so/FOmzTty6oi9
https://buymeacoffee.com/vikingente3
https://creplaybookseries.billrapponline.com
https://creplaybook.billrapponline.com/
©Bill Rapp, CCIM - Director - CommLoan
Main Office:
Medallion Funds
[email protected]
11920 Southern Highlands PKWY Suite 302Las Vegas, NV 89141
Texas Complaint and Recovery Fund Notice
All Rights Reserved Copyright © 2021 - Bill Rapp The Mortgage Viking | NMLS #228246