ATTENTION: For Those who are serious about Getting Pre-Qualified FAST!
Bill Rapp, Mortgage Originator: NMLS 228246
"Brokers Are Better.
Better Pricing, Better Service!"
Subscribe To My List Below To Get Your Mortgage Quote Now!
Simply enter your name and email below:
WITH PROVEN STRATEGIES & PROVEN RESULTS
HERE'S WHAT MY CLIENTS SAY:
What People Are Saying:
Excellent Service
Bill is an exceptional loan officer. He helped us to purchase our home with very personal and professional service. He helped us navigate the whole process from start to closing without any problems. We didn't think we're qualified to purchase a house, but Bill went above and beyond to find a way to help us achieve our goal. He always responded very quickly with our requests, he would come back with different options with comparison chart to clearly indicate how much we need for down payment, monthly payments, interest rates, closing costs etc.
We would highly recommend Bill to anyone in need of lending services. In fact, we have already recommended Bill to one of our friends on purchasing a house.
--- David Chan - Houston, TX
Bank Statement Lending!
William Rapp of Network Funding, L. P. was very professional and I felt comfortable in dealing with him. I will definitely recommend him to family and friends.
--- Ian F - Missouri City, TX
Professionalism - Expert In Home Style Loan
Bill is an expert in the topic, his explanations and online material make a difference and he is always there from the beginning to the end. He is committed to make thing happen.
--- Felipe Caldern & Carolina Angel Gutierrez
Great Service!
Bill Rapp's handling of our loan (even though out of state) was unparalleled to any service I have been through prior, including 3 different real estate transactions and multiple refinances. Extremely quick close, with great options and flexibility for my families needs. All around A+
--- Chris & Beth Sheehan - San Jose, CA
Knowledgeable and Responsive!
Bill was a pleasure to work with and he made the loan process fairly easy. He answered all questions I had very quickly and was straight forward in doing it. I would recommend Bill to others.
--- Wes Brady - Richmond, TX
Very professional and always returned our calls!
Bill takes a lot of pride in his job and is very dependable. They were very patient and understanding. He went out of his way and explained all my questions and concerns. They were very professional and returned my phone calls and emails. He did a great job and I fully recommend him.
--- Therese, Malcom & Shirley Teixeira - Katy, TX
Great Job!
Bill helped us out from beginning to end of loan process. The loan closed in a timely manner as Bill worked hard with bank to get our to the final steps.
--- Kamal & Theresa Wilson - Hartford, CT
Avid Problem-Solver and Absolute Pleasure to Work With!
Bill Rapp worked very hard to ensure that we closed our loan and were able to move into our new home. He always had alternatives to any problems we encountered while closing. He worked with us from the beginning identifying solutions to any problems that we were having. He was an absolute pleasure to work with!
--- Nikita Rayani & Sanit Tejani - Houston, TX
Awesome to work with!
Being a first-time buyer I came in with lots of questions and concerns. Bill was always available for any questions I had and answered everything to my satisfaction. Bill made the loan process so painless that I could still concentrate on other things. We ended up closing early which made things even better. If you are in need of a lender and want someone who is very approachable and stays on top of your loan then Bill is your guy.
--- Cesar Raya - Richmond, TX
Loan Declined by my bank, and he saved the day!
Bill, did an amazing job helping me close on my house. He took the reigns and reassured me the best route to take to help close. He was accountable, thorough and trustworthy. I will continue to work with Network Funding, L.P. when it comes to home buying in the future because of the quality of service Bill gave.
--- Jacob Smith - Boerne, TX
Bill Rapp Will Definitely Make It Happen!
Bill is the most kind, patient and helpful person I have ever known. He answers his phone calls and emails promptly. You can ask him a million questions, and he will answer each and every one of them. Before I started working with Bill, I had been turned down for a home loan, because of some past credit issues I had, plus I was a single mother. However, once I started working with Bill, he was able to quickly get me a home loan, with a good interest rate. I would recommend that you call him, as he will help you.
--- Corinne Wilson - Roselle, NJ
Knowledgeable, Honest, Trustworthy, and Reliable!
"I will definitely keep you in mind. If anyone I know needs financing, I will send them your way!"
--- Jon & Andrea Saleem, CRPC Financial Advisor - Houston, TX
Best Dam Mortgage Guy a man could know!
"Hands down the best loan experience to date!"
--- Gabe & Chelsea Jackson - Pearland, TX
Phenomenal, Hard Working and Never Quits!
Had a stupid foreclosure that could have been avoided if ex’s attny would have sent my buy out offer. So Bill was able to push this through with a 4 year foreclosure. He worked his butt off, was very diligent with his communication; and was very professional talking to me even when I was screaming and/or crying at him. Highly recommend this lender. He really go to the ends of the earth to help you!
--- Liz Keeter - Harlingen, TX
Exceptional customer service!
Bill is the most kind, patient and helpful person I have ever known. He answers his phone calls and emails promptly. You can ask him a million questions, and he will answer each and every one of them. Before I started working with Bill, I had been turned down for a home loan, because of some past credit issues I had, plus I was a single mother. However, once I started working with Bill, he was able to quickly get me a home loan, with a good interest rate. I would recommend that you call him, as he will help you.
--- Isha Lopez & Mauricio Garcia - Houston, TX
Service with a capitol S
Bill went above and beyond at every turn. He worked late on Saturday, he worked late all the time. We wanted to close ASAP and he really helped make it happen for us.
--- Jeff & Wendy Heger - Houston, TX
Best Buying Experience!
I would would highly recommend going with Network Funding LP. As a first time home buyer I didn't know what to expect. Bill Rapp was very helpful in answering all my questions and guided me through all ghe steps. I couldn't have asked for a better buying experience!
--- Tabitha Turner - Humble, TX
Would recommend him and use him again!
Very involved and professional . Kept me informed and up to date on everything that was going on Went with me closing and was very helpful and knowledgeable.
--- Kathy Ward - Houston, TX
Great experience!
Well I meet bill back in December 2016 he got recommended by my real estate agent we had a house in sight and started the process to get approved but we fail due to my work history and credit bill told me not to give up and put me in contact with a credit repair company they help me bring my score up and bill walk me thru the process of getting a new line so this time around we got approved before looking for our house after we found it we still had a couple of hick up but with bills help on Sunday 6-18-17 to be exact Father's Day bill called me to give me the great news that we had got approved and the closing date was as scheduled bill was more than just a lender to my family he became a friend and I'm alway going to have him in mind for any other financial situation.
--- Alejandres Felimon - Richmond, TX
I really liked his attitude!
I wouldn't usually say this but the way he had handled my mortgage was really pleasant. I personally enjoyed the time spent with him while we discussed feasible rates. He's a great man with a great personality and he offered really low interests as well. Definitely recommend him to others.
--- Tom Troiano - Atlantic City, NJ
He's nothing short of a miracle!
I'm a self-employed businessman and had him figure out the mortgage of the house after 30% down payment. The interest rates I received were incredibly low given what I had thought of earlier. One other important thing to note was that I hadn't really taken any loans earlier, so I had no credit history. He helped me out with all that as well so I can't really call him anything else but a miracle.
--- Fran Suarez - Cleveland, OH
He's really helpful!
I made a bid to him and the very same day he gave me an offer which I couldn't resist. It was too intimidating with those incredibly low interest rates and all, thoroughly recommend him.
--- Kenny Mickle - Houston, TX
Expeditious!
Bill was very expeditious and made it real easy going through the loan process. I felt he was on top of things.
I deal with investment properties and will more than likely call on him again.
--- Wayne King - Pensacola, FL
Bill was great!
Bill made us feel like a friend all the way thru the process. He was patient and explained everything he needed clearly. He was available ANYTIME we had questions or needed more information. Hopefully we won’t go thru this process again anytime soon, but if we do - we’d choose Bill! =)
--- Barbra & Nick Grimmer - Austin, TX
Great broker!
Bill was a great broker to work with. As first time home buyers we had many questions about the process, Bill took the time to help us even calling us back on weekends with answers. I would not hesitate to recommend him to anyone looking for a broker to work with.
--- Murray & Lisa Turner - Pensacola, FL
Outstanding service!
I couldn't have been more pleased with Bill's level of service. He made what is typically a lengthy, arduous process far quicker and easier at every turn. I'm extremely comfortable recommending Bill to friends and family, and will definitely utilize his services again!
--- Jim Lipari - Austin, TX
Step-by-Step Guide to the VA Loan Process
6 Easy Steps to a VA Loan
For many borrowers, applying for any kind of mortgage may seem daunting.
But, when broken down, this rundown of 6 steps to getting a VA loan is easy to understand.
1. Select a VA-approved Lender
On the surface, it might appear that any lender will do. However, if you dig a little deeper, you may discover that not all lenders are the same. First, only lenders approved by the U.S. Department of Veterans Affairs can originate VA mortgages. Secondly, some lenders focus primarily on conventional loans, while others concentrate almost exclusively on the VA loan program for military clients. Using a VA specialty lender with extensive knowledge about the VA loan process vs. a lender who only funds a few VA mortgages a year may translate into an easier and quicker loan process. To connect with a VA specialty lender, please click here.
2. Obtain a Certificate of Eligibility (COE)
An experienced lender can help you obtain what’s called a Certificate of Eligibility (COE). The COE will prove that you meet initial eligibility standards for VA loan benefits. It will also let the lender know how much entitlement you can receive, which is the amount the Department of Veterans Affairs will guarantee on your VA loan. To get your COE, you’ll need to give your lender a bit of information about your military service. Usually, a COE can be acquired online instantly through a lender’s portal or through the eBenefits portal on the va.gov website. Those servicemembers or surviving spouses whose COEs cannot be obtained online will have to get theirs by mail. A VA lender or the VA can help direct you to the right resource for your specific situation.
3. Pre-Qualify for Your Loan Amount
Pre-qualifying is important, but not required. By choosing to complete this step you can save some time and potential surprises later in the process. To pre-qualify for your loan amount, you’ll have a candid conversation with your VA loan professional about your income, credit history, employment, marital status and other factors. Giving your lender complete details during the pre-qualifying step can help prevent surprises later during underwriting. The pre-qualifying step can also reveal areas that need improvement before you can be approved, such as credit or debt-to-income ratio. While a prequalification letter gives you a ballpark price range for house hunting, it does not guarantee that you will be approved for a loan, and your lender will later have to verify the information you provide. To get a loan requires later final approval by underwriting once all documents have been received and reviewed (see Step 5).
4. Go House Hunting & Find Home
The fourth step is usually one borrowers enjoy because they get to look at homes they might consider buying. Working with a real estate professional who specializes in the VA process can help you get the most out of your benefits. This is true because the VA allows certain fees and costs to be paid by the seller (if both you and the seller agree), and a knowledgeable agent will know this and help you negotiate seller-paid fees. Once you’ve got a signed purchase agreement, you can move forward in the VA loan process.
5. Lender Processes Application
& Orders VA Appraisal
A signed purchase contract is the document you’ll need to finish your initial application. Once your lender has the contract, they will order the VA appraisal. Here again, not just any appraiser will do. Only a professional who is certified to perform appraisals to VA standards can evaluate the home being considered for VA financing. The VA appraiser will make sure the price you’ve agreed to pay for the home corresponds with the current value. Another very important part of the VA appraisal is to inspect the home to make sure it meets the VA minimum property requirements (VA MPRs). However, the VA appraisal does not take the place of a home inspection, which focuses on code violations, defects and the condition of the property. While many borrowers have heard horror stories about the length of the VA appraisal process, the Department of Veterans Affairs gives the appraisers 10 days from order to completion barring extenuating circumstances. While you’re waiting for appraisal documents, you’ll be busy submitting documents of your own to your VA-approved lender to show you have the ability to qualify for the loan. If the home passes appraisal for value and VA minimum property requirements, and it’s verified by the lender that you qualify for your loan, the underwriter will give his or her stamp of approval.
6. Close on Your Loan and Move In
After being approved by the underwriter, all that is left to do is close and move in. During closing, the property legally transfers from the former owner to you. Closing is a step that requires you to sign documents that confirm you understand and agree to the terms of the loan. You will need to provide proof of homeowners insurance and, if required, pay closing costs. Once you’ve signed all your closing documents, you’ll get the keys to your new home.
While these steps may not happen in the order above or be a required part (such as prequalification)*, they represent the typical process for the applicant in obtaining a VA purchase loan. Your lender may need to take other steps. For more information about VA loans, contact an experienced VA-approved lender.
My best advice to you is to call Bill Rapp, the Mortgage Viking, today to discuss your options 281-222-0433.
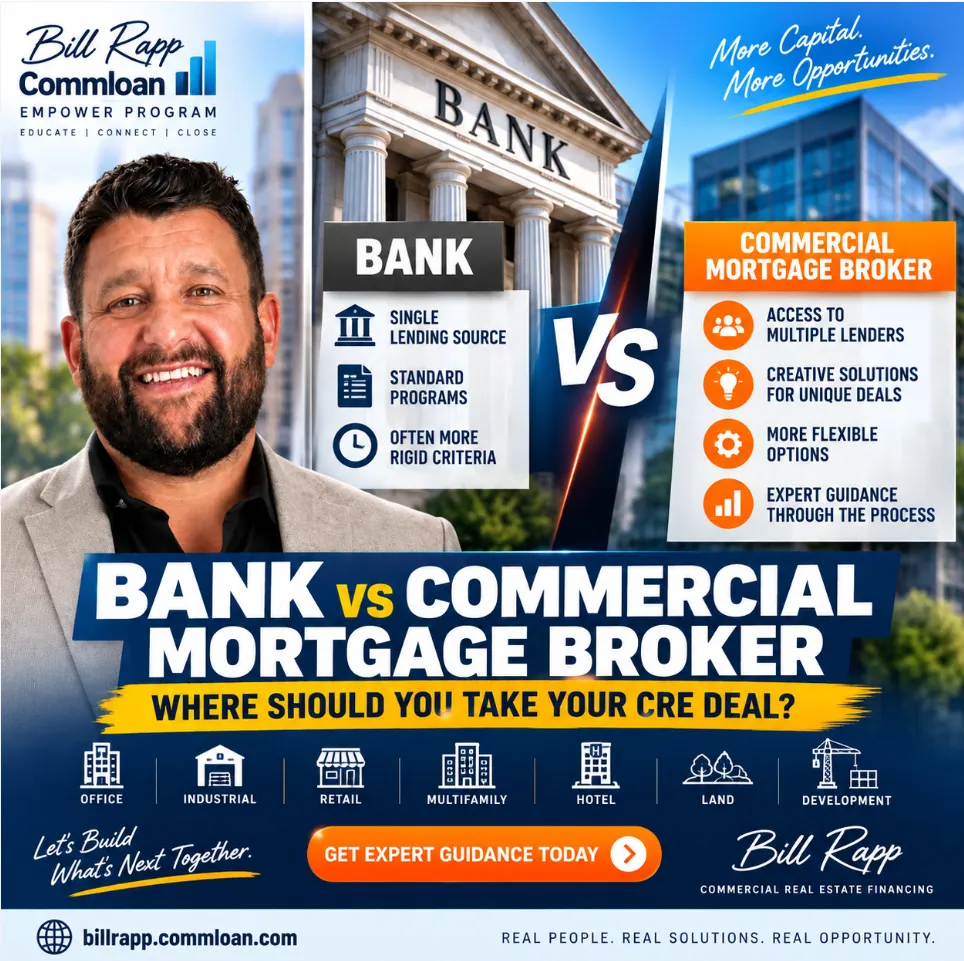
🏦 Bank vs. Commercial Mortgage Broker: Where Should You Take Your CRE Deal? 🏢
🏦 Bank vs. Commercial Mortgage Broker: Where Should You Take Your CRE Deal? 🏢
💰 Commercial Real Estate Financing: Bank Loan or Commercial Mortgage Broker? 🔑
________________________________________________________________________________
Bank vs. Commercial Mortgage Broker: Where Should You Take Your CRE Deal?
When you need commercial real estate financing, one of the first decisions is where to take the deal.
Do you walk into your existing bank and apply for a commercial real estate loan?
Or do you work with a commercial mortgage broker who can evaluate the transaction and seek financing from multiple potential capital sources?
There is no universal answer. Banks and commercial mortgage brokers serve different functions, and the right approach depends on the property, borrower, transaction structure, timing, leverage, cash flow, and overall financing objective.
The key is understanding the difference before you commit to a financing strategy.
What Happens When You Take a CRE Deal Directly to a Bank?
A bank evaluates your commercial real estate transaction against its own lending criteria.
That can include:
·Property type
·Loan size
·Loan-to-value ratio (LTV)
·Debt service coverage ratio (DSCR)
·Borrower liquidity
·Net worth
·Credit history
·Guarantor strength
·Geographic footprint
·Deposit relationship
·Industry concentration
·Loan concentration
·Amortization and maturity requirements
If your transaction fits the bank's credit box, a direct bank relationship can work very well.
This can be especially true when you already have a strong banking relationship, the property and borrower fit conventional underwriting standards, and the bank is actively lending on that particular type of transaction.
But there is an important distinction:
A bank can generally offer you the financing solutions available from that bank.
That is different from evaluating the deal across a broader commercial lending market.
What Does a Commercial Mortgage Broker Do?
A commercial mortgage broker or capital advisor approaches the transaction from a different direction.
Rather than asking:
"Does this deal fit our bank?"
The question becomes:
"What type of lender and financing structure best fits this transaction?"
Depending on the deal, potential capital sources can include:
·Banks
·Credit unions
·SBA lenders
·Agency lenders
·CMBS lenders
·Debt funds
·Bridge lenders
·Life insurance companies
·Private lenders
·Specialty finance companies
·Other commercial real estate capital sources
That broader perspective can become particularly valuable when a transaction doesn't fit neatly inside one lender's underwriting box.
Bank vs. Commercial Mortgage Broker: The Fundamental Difference
Think about the difference this way.
A bank is a source of capital.
A commercial mortgage broker is a source of potential capital relationships and financing strategies.
That does not automatically make one approach better than the other.
A strong local bank may provide exactly the financing you need.
But when the transaction is complicated—or when you want to understand alternatives—a commercial mortgage broker can help determine which lenders may be appropriate for the opportunity.
When Going Directly to a Bank Can Make Sense
A direct bank relationship can be attractive when you have a relatively straightforward transaction.
For example, imagine a business owner purchasing the building their company has occupied for several years.
The business has strong historical cash flow, the borrower has excellent liquidity and credit, leverage is conservative, and the borrower already has a substantial relationship with a local bank.
That may be an excellent bank transaction.
Existing relationships can matter in commercial lending. A bank that understands your business, financial history, deposits, and management team may be comfortable underwriting a transaction that fits its credit standards.
When a Commercial Mortgage Broker Can Add Value
Now consider a different transaction.
An investor is purchasing a property with:
·Significant vacancy
·Near-term lease rollover
·Planned renovations
·An aggressive closing deadline
·Transitional cash flow
·A request for higher leverage
One bank might decline the transaction because of occupancy.
Another lender might consider it but reduce proceeds because of DSCR.
A bridge lender might evaluate the transaction based on the stabilization strategy.
Another institution might have an attractive program but require different reserves or sponsorship strength.
This is where commercial mortgage brokerage and capital advisory can become particularly useful.
The problem isn't necessarily that the transaction cannot be financed.
The challenge may be identifying the right capital source for the transaction.
Commercial Real Estate Financing Is More Than Finding the Lowest Rate
Borrowers naturally focus on interest rates.
Rates matter.
But the lowest advertised rate does not automatically produce the best financing structure for a particular transaction.
Commercial borrowers should also evaluate:
Loan proceeds. How much will the lender actually advance?
Amortization. Is the loan amortized over 20, 25, or 30 years?
Maturity. Is the loan due in five, seven, or ten years?
Recourse. Will personal guarantees be required?
Prepayment provisions. Is there a declining prepayment penalty, yield maintenance, defeasance, or another restriction?
Reserves. Will the lender require replacement, tax, insurance, tenant improvement, or leasing commission reserves?
Covenants. What ongoing financial requirements will apply?
Closing timeline. Can the lender realistically meet the transaction deadline?
A slightly lower interest rate can lose much of its appeal if the structure doesn't accomplish the borrower's actual objective.
Why Lender Fit Matters
Commercial lenders do not evaluate every property type equally.
A lender that aggressively finances stabilized multifamily properties may have little appetite for hotels.
A bank comfortable with owner-occupied industrial buildings may not want a partially vacant retail center.
A lender interested in $2 million loans may have little interest in a $20 million request—and vice versa.
Lending appetite can also change.
Banks manage concentrations. Capital markets move. Credit policies change. Property types move in and out of favor.
That means a lender that financed your last transaction may not necessarily be the right lender for your next one.
The Three Numbers That Can Limit Your Loan
Commercial real estate investors should understand three particularly important underwriting metrics:
Loan-to-Value Ratio
LTV = Loan Amount ÷ Property Value
A lender offering 75% LTV does not necessarily mean you will receive 75% financing.
Debt Service Coverage Ratio
DSCR = Net Operating Income ÷ Annual Debt Service
Even when the property's value supports the requested loan, cash flow must generally support the associated debt service under the lender's underwriting requirements.
Debt Yield
Debt Yield = Net Operating Income ÷ Loan Amount
Debt yield allows lenders to evaluate property income relative to loan exposure without relying directly on interest rate or amortization.
Depending on the lender and transaction, one of these tests may become the binding constraint on proceeds.
That is why asking "What's your maximum LTV?" is often only the beginning of the financing discussion.
Should You Shop Your CRE Loan Yourself?
You certainly can.
But commercial financing isn't always comparable to requesting three identical mortgage quotes.
Different lenders may underwrite NOI differently, offer different amortization periods, require different reserves, calculate DSCR differently, or have completely different appetites for the same property.
Submitting a transaction indiscriminately to numerous lenders can also create unnecessary confusion.
Effective commercial mortgage brokerage isn't simply sending a loan request everywhere.
It is matching the transaction to lenders whose programs and credit criteria make sense for the deal.
What Information Should You Prepare?
Whether you approach a bank directly or work with a commercial mortgage broker, preparation matters.
For an investment property, lenders commonly want information such as:
·Purchase contract or loan statement
·Current rent roll
·Historical operating statements
·Property financial projections when applicable
·Personal financial statement
·Schedule of real estate owned
·Borrower liquidity information
·Organizational documents
·Property information
·Sponsor experience
For owner-occupied properties, underwriting may also require:
·Business tax returns
·Interim profit-and-loss statements
·Balance sheets
·Business debt schedules
·Ownership information
·Business projections when applicable
The cleaner the financing package, the easier it becomes to identify potential problems before they threaten the transaction.
Financing Should Start Before the Purchase Contract
One of the biggest mistakes commercial buyers make is treating financing as an afterthought.
A property may appear affordable based on purchase price alone.
But lender requirements for DSCR, LTV, liquidity, reserves, debt yield, guarantor strength, and property condition can materially affect how much capital is available.
Understanding those constraints before making an offer can improve your negotiating position and reduce the chance of discovering a financing gap after going under contract.
Bank or Commercial Mortgage Broker?
The better question may be:
How straightforward is the transaction, and how much of the commercial lending market do you need to evaluate?
A strong bank relationship can be extremely valuable.
A commercial mortgage broker can be valuable when you need broader lender access, help evaluating structures, a solution for a more complicated transaction, or assistance navigating the commercial financing process.
And these approaches aren't necessarily mutually exclusive.
A qualified capital advisor may ultimately determine that a bank is the appropriate destination for your transaction.
The objective isn't to avoid banks.
The objective is to get the right CRE deal in front of the right capital source.
Start With the Deal, Not the Lender
Before deciding where to take your next commercial real estate transaction, start with the fundamentals:
What are you buying or refinancing?
How much financing do you need?
What does the property's cash flow support?
How much equity and liquidity do you have?
What is your timeline?
What are you ultimately trying to accomplish?
Once those questions are answered, you can build the financing strategy around the transaction instead of trying to force the transaction into a predetermined lending box.
I'm Bill Rapp with the CommLoan Empower Program. If you're buying, refinancing, or repositioning commercial real estate, let's evaluate the deal and determine what financing strategy may fit the opportunity.
Top of Form
Bottom of Form
Bill Rapp, CCIM
Director | CommLoan
📞 281-222-0433
📧 [email protected]
🌐 https://billrapp.commloan.com/
🌐 https://HoustonCommercialMortgage.com/
Commercial Real Estate Financing Nationwide
https://billrapp.commloan.com/
https://author.billrapponline.com/
https://www.amazon.com/dp/B0F32Z5BH2
https://veed.cello.so/FOmzTty6oi9
https://buymeacoffee.com/vikingente3
https://creplaybookseries.billrapponline.com
https://creplaybook.billrapponline.com/
©Bill Rapp, CCIM - Director - CommLoan
Main Office:
Medallion Funds
[email protected]
11920 Southern Highlands PKWY Suite 302Las Vegas, NV 89141
Texas Complaint and Recovery Fund Notice
All Rights Reserved Copyright © 2021 - Bill Rapp The Mortgage Viking | NMLS #228246